


FactSet Research Systems (FDS) is back in focus after announcing a new collaboration with Hamilton Lane that will pipe extensive private markets data directly into FactSet’s portfolio analytics platform.
Those product moves are landing against a sharp rebound in the FactSet Research Systems share price, with a 30 day share price return of 25.0% and a 90 day gain of 19.6%. However, the 3 year total shareholder return is down 23.1%, so momentum has recently picked up but long term holders are still under water.
Spot similar momentum plays in data and analytics by scanning our curated list of 19 high quality undiscovered gems, which combine strong fundamentals with under-the-radar market interest.FactSet Research Systems has just sprinted higher, which puts anyone on the sidelines in a familiar spot. Should investors lean into the current price or wait and see what the valuation math indicates first?
Most Popular Narrative: 29% Overvalued
At a last close of $332.59, the most followed narrative on FactSet Research Systems puts fair value at $258.69, which frames the recent price surge as rich against that reference point.
Guidance for organic ASV growth in the year ahead, 5% to 6.5% represents a declared deceleration from the 7% just delivered. Management’s assembled response: no pull-forward, robust pipeline, guidance that is “higher and tighter than what FactSet has provided in the last two years.” The frame positions deceleration as conservative prudence. Whether that framing holds will be visible in the first quarter, where management acknowledged ASV is second-half weighted and noted Q1 pipeline confidence.
See why 1 investors see FactSet Research Systems as 29% overvalued.
Result: Fair Value of $258.69 (OVERVALUED)
Still, two obvious pressure points could flip the FactSet Research Systems story quickly. Any credibility hit around AI partnerships or slower MCP monetisation would challenge the current overvaluation case.
Find out about the key risks to this FactSet Research Systems narrative.
Another View on FactSet Research Systems Valuation
The first narrative pegs FactSet Research Systems at $258.69, which frames today’s $332.59 share price as stretched. A different lens tells a very different story. The SWS DCF model estimates the future cash flow value at $450.54, which implies the stock is undervalued rather than expensive.
That split between fair value estimates raises a simple question for you as an investor. Which set of assumptions about FactSet’s cash generation do you trust more: the shorter term earnings multiple view, or the longer term cash flow model that underpins our DCF work?
Look into how the SWS DCF model arrives at its fair value.
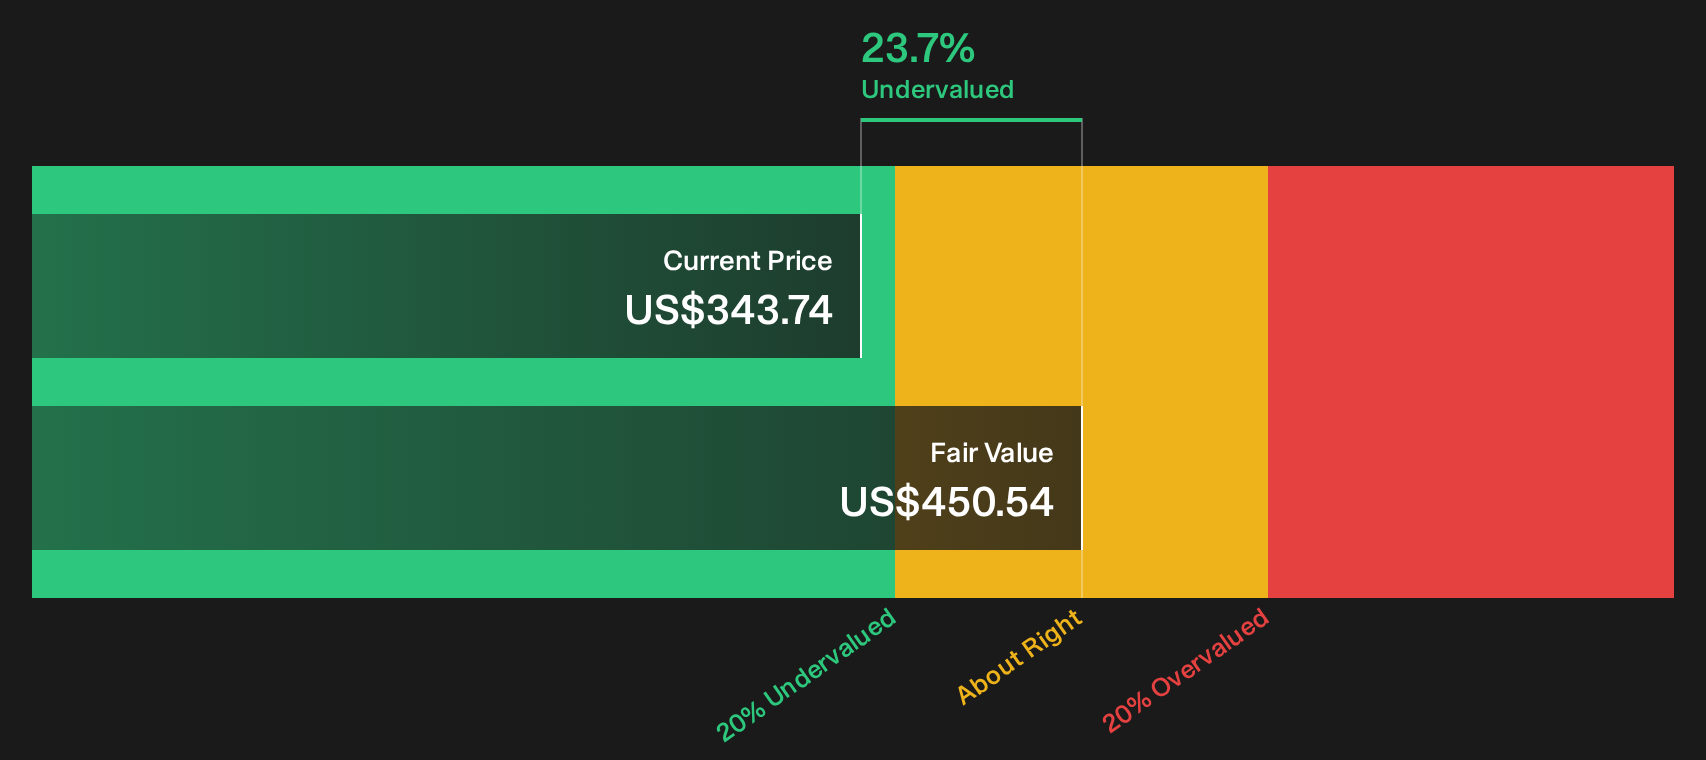
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FactSet Research Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Debate around FactSet Research Systems is clearly split, which is exactly when fresh eyes on the data matter most. Move quickly, stress test the bullish and cautious cases side by side, and ground your stance in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond FactSet Research Systems?
If you stop with FactSet Research Systems, you risk missing other opportunities. Put a few more high quality prospects on your radar using targeted screeners now.
- Target stability first by checking companies that show resilient fundamentals and lower risk profiles through our 29 resilient stocks with low risk scores.
- Build income potential by scanning a curated set of reliable payers using the 4 dividend fortresses.
- Get ahead of the crowd by searching for under-followed opportunities with strong financials using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com