


HealthStream shareholders took a hit today. The stock dropped 8.4% to US$31.67 as investors reacted to fresh Q3 2026 numbers that paired solid top line performance with a clear squeeze in profitability.
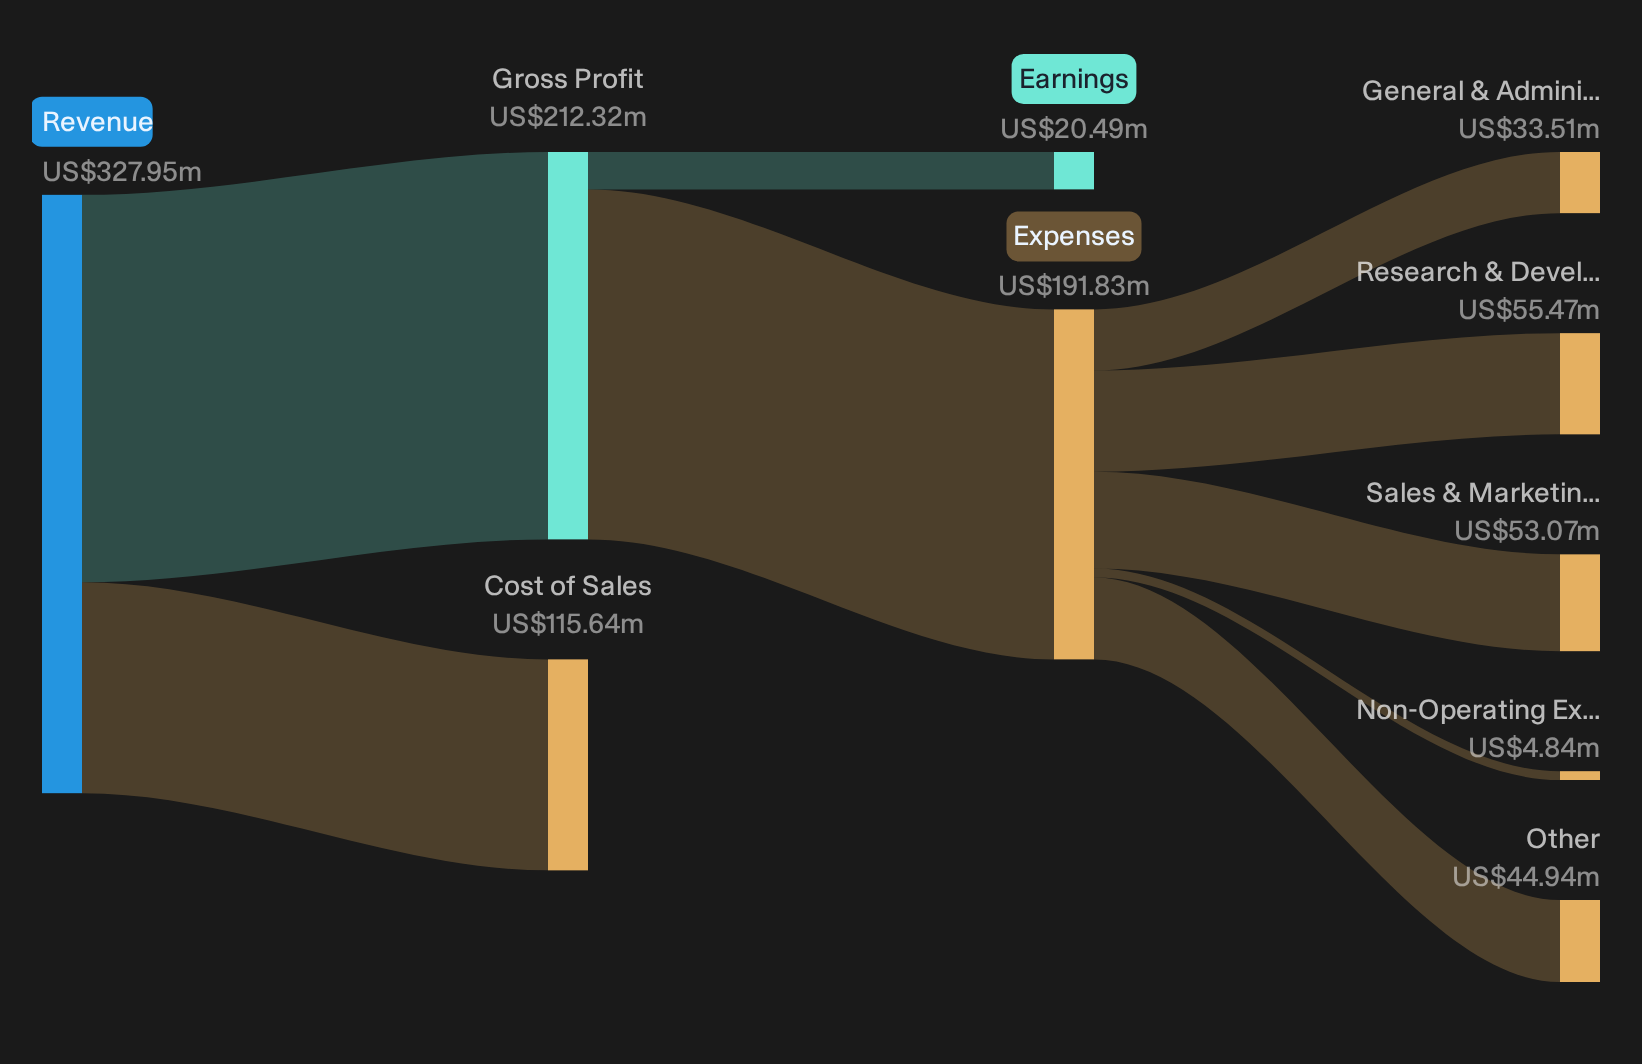
The headline reads like a classic short term versus long term clash. Quarterly revenue landed at US$83.3m, net income came in at US$5.4m, and adjusted EBITDA margin sat at 23.2%. On a longer view, trailing twelve month earnings, cash strength, and raised full year guidance now matter more than a single quarter of pressure on margins.
Like the cash position and raised guidance from HealthStream but uneasy about the squeeze in profitability this quarter? Compare that mix of strengths and pressure points with our screener of financially resilient stocks through the list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$83.3m vs. US$76.5m (up 8.9%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$5.4m vs. US$6.1m (down about 11.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.18 vs. US$0.20 (lower year on year)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 23.2% vs. prior year level not specified (profitability appears under pressure even as sales increased)
HealthStream raised guidance again as its platform strategy ramps. Ask Charlie what HealthStream’s new suites mean for growth.
HealthStream’s Bull Case Meets Mixed Execution
Supporters argue HealthStream can lean on contracted revenue while newer products reshape earnings quality over time.
"Remaining performance obligations of about US$685 million to US$687 million at the end of Q1 and Q2 2026, with roughly 39% to 40% expected to turn into revenue in 12 months and about 67% to 68% in 24 months, give HealthStream room to layer new products and price points onto an already contracted base and potentially smooth earnings growth as the mix shifts toward modern platforms."
Q3 showed that anchor working. Subscription sales increased alongside higher professional services, legacy offerings shrank to about 10% of turnover, and guidance moved higher. At the same time, extra spend and softer gross margin meant net income declined, so earnings are not yet smoothing in the way supporters describe.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
HealthStream Bear Case: Legacy Drag Now Hitting Earnings
Bearish investors argue that HealthStream’s legacy erosion will blunt the impact of newer suites and keep profitability under strain.
"Despite growth in core SaaS suites such as CredentialStream and ShiftWizard, revenues from legacy credentialing and scheduling products continue to fall at double digit rates. If this drag persists for longer than expected, it could offset gains from the migration to modern offerings and limit overall revenue growth and operating leverage."
Q3 results back up that concern. Legacy and sunsetting products fell 15% and now sit at roughly 10% of turnover. Organic revenue growth of 4.7% and lower gross margin, alongside a decline in operating income and net income, signal that the legacy headwind is already weighing on operating leverage, even as guidance moves higher.
Hunt For Mispriced Earnings Power
HealthStream just showed how a solid balance sheet can sit alongside pressure on profitability. The real opportunity could be spotting stocks that look mispriced before the market closes the gap.
- Company 1 - 43% below our estimate - sell large-format LED systems as sports, transport and youth venues shift to digital scoreboards and signage.
- Company 2 - 28% below our estimate - grow fee and lending income as digital channels deepen engagement with underbanked customers and support broader financial services cross-selling.
- Company 3 - 45% below our estimate - enable large merchants to accept and send local payments as transaction volumes consolidate onto a single integrated platform.
Three companies from the same screener. Open all 35 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com