


Central banks have hit pause, inflation is cooling, and short-term rates suddenly matter a lot more to anyone parking cash instead of riding long-term bets. That mix creates an opening and a risk for investors looking at asset managers tied to money-market and short-duration strategies that can react quickly as policy twists again. This article breaks down three stocks exposed to that macro story and explains why their positioning around ultra-short cash management might deserve a closer look right now.
The stocks covered below are just a starting sample, and the wider screen surfaced 23 more large, cash-focused asset managers with equally compelling stories that are not unpacked in this article. To go straight to the source and analyze, compare, and shortlist your highest conviction ideas, head into the Global Short-Duration Cash & Money-Market Asset Managers screener.
UTI Asset Management (NSEI:UTIAMC)
UTI Asset Management plugs neatly into the short-duration and money-market theme as a pure-play Indian fund house that earns fee income for running mutual funds and cash-focused portfolios. This makes it a direct way to watch how investors position their spare cash when rate expectations move again.
UTI Asset Management manages Indian mutual funds across money-market, fixed income, and equities, earning around ₹17,160 million from asset management services and carrying a market value of roughly ₹103.0 billion.
"The company’s earlier push into technology-led tools such as Salesforce and UTI HART is now reinforced by a 234% increase in digital revenue, 33% more digital transactions, and a 31% lower cost per transaction."
What happens to that fee stream if a single key assumption about how efficiently those digital gains translate into lower costs and sturdier margins breaks?
If that assumption matters to your thesis, read the full narrative for UTI Asset Management to see how those digital gains could reshape fees, resilience, and cash-flow risk.

EFG International (SWX:EFGN)
EFG International taps directly into the short-duration and cash-management theme because many wealthy clients hold sizeable cash and ultra-short bond positions inside broader portfolios that also need advice, lending and long-term investment support.
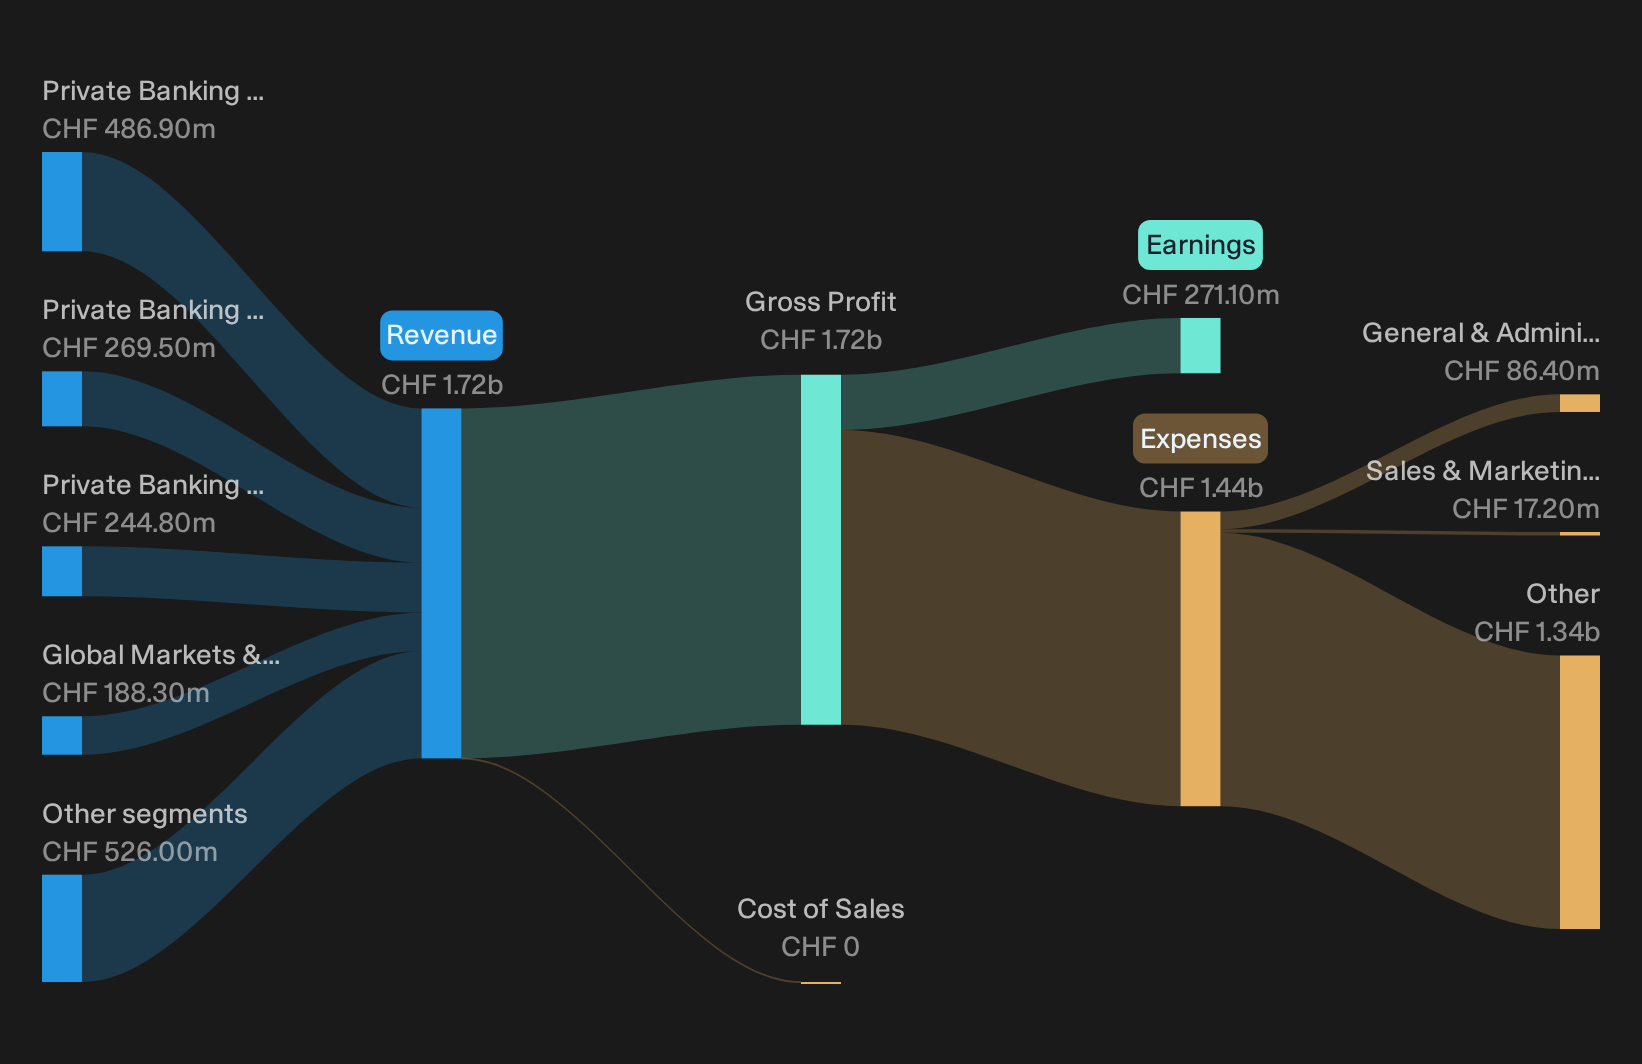
EFG International runs private banking, wealth and asset management services that naturally bundle cash and short-duration solutions with longer-term investing across Switzerland, Europe, Asia Pacific and the Americas, with CHF 486.9 million from Switzerland and Italy, CHF 269.5 million from Asia Pacific, CHF 244.8 million from Continental Europe and Middle East and CHF 160.8 million from the UK, on top of CHF 188.3 million from Global Markets & Treasury and CHF 140.9 million from Investment and Wealth Solutions, and the stock carries a roughly CHF 5.0b market value.
"EFG International continues to report positive net new assets across all regions, with 6.2% annualized growth in H1 2026 and strong contributions from Asia Pacific and Continental Europe or Middle East, which supports the view that further client inflows can add to fee income and revenue."
What happens to EFG International’s earnings power if one still developing pressure on credit quality and one-off costs shifts the margin story again.
If that margin risk is what you are wrestling with, read the full narrative for EFG International to see how EFG International’s cash flows and capital story might be decoupling.
Investec Group (JSE:INL)
Investec Group links neatly to this short-duration and cash-management theme because it combines specialist banking with wealth and treasury services that depend heavily on client deposits, liquidity and ultra-short funding lines in both South Africa and the U.K.
Investec Group earns about £903 million from Corporate and Investment Banking and Other in the UK and other regions, £578 million from that segment in Southern Africa, £335 million from Southern African Private Banking and £158 million from Southern African Wealth & Investment, with a market value of roughly ZAR112.6 billion.
Investec Group’s toolkit for short-term cash hinges on how it funds itself. This is where the recent commentary around mix, deposit gathering and balance sheet flexibility becomes important for anyone watching short-duration exposure.
"Scaling transactional banking and operational deposit gathering in both South Africa and the U.K. is improving the funding mix away from wholesale deposits. This should lower the cost of funds and underpin net interest margins and earnings resilience."
What happens to that resilience if one unseen pressure on credit quality and capital deployment pulls against those funding gains at the same time?
Those cross currents deserve context. Read the full narrative for Investec Group to see whether Investec Group’s funding shift is quietly building an overlooked earnings engine.

Seeking Alternatives Before Everyone Else
Fresh ideas move first, prices move next. Spot potential breakouts, fading laggards and under the radar strength while it still matters, then get in early.
- Spot early momentum in cash generative businesses by scanning the curated 197 high quality undervalued stocks before that quality shows up on every fund manager’s radar.
- Track where robotics demand could be flying next by reviewing the hand picked 94 robotics and automation stocks while prices still reflect old expectations instead of future workflows.
- Position ahead of possible power grid upgrades by reviewing the focused 42 power grid technology and infrastructure stocks before those infrastructure stories are fully priced into the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com