


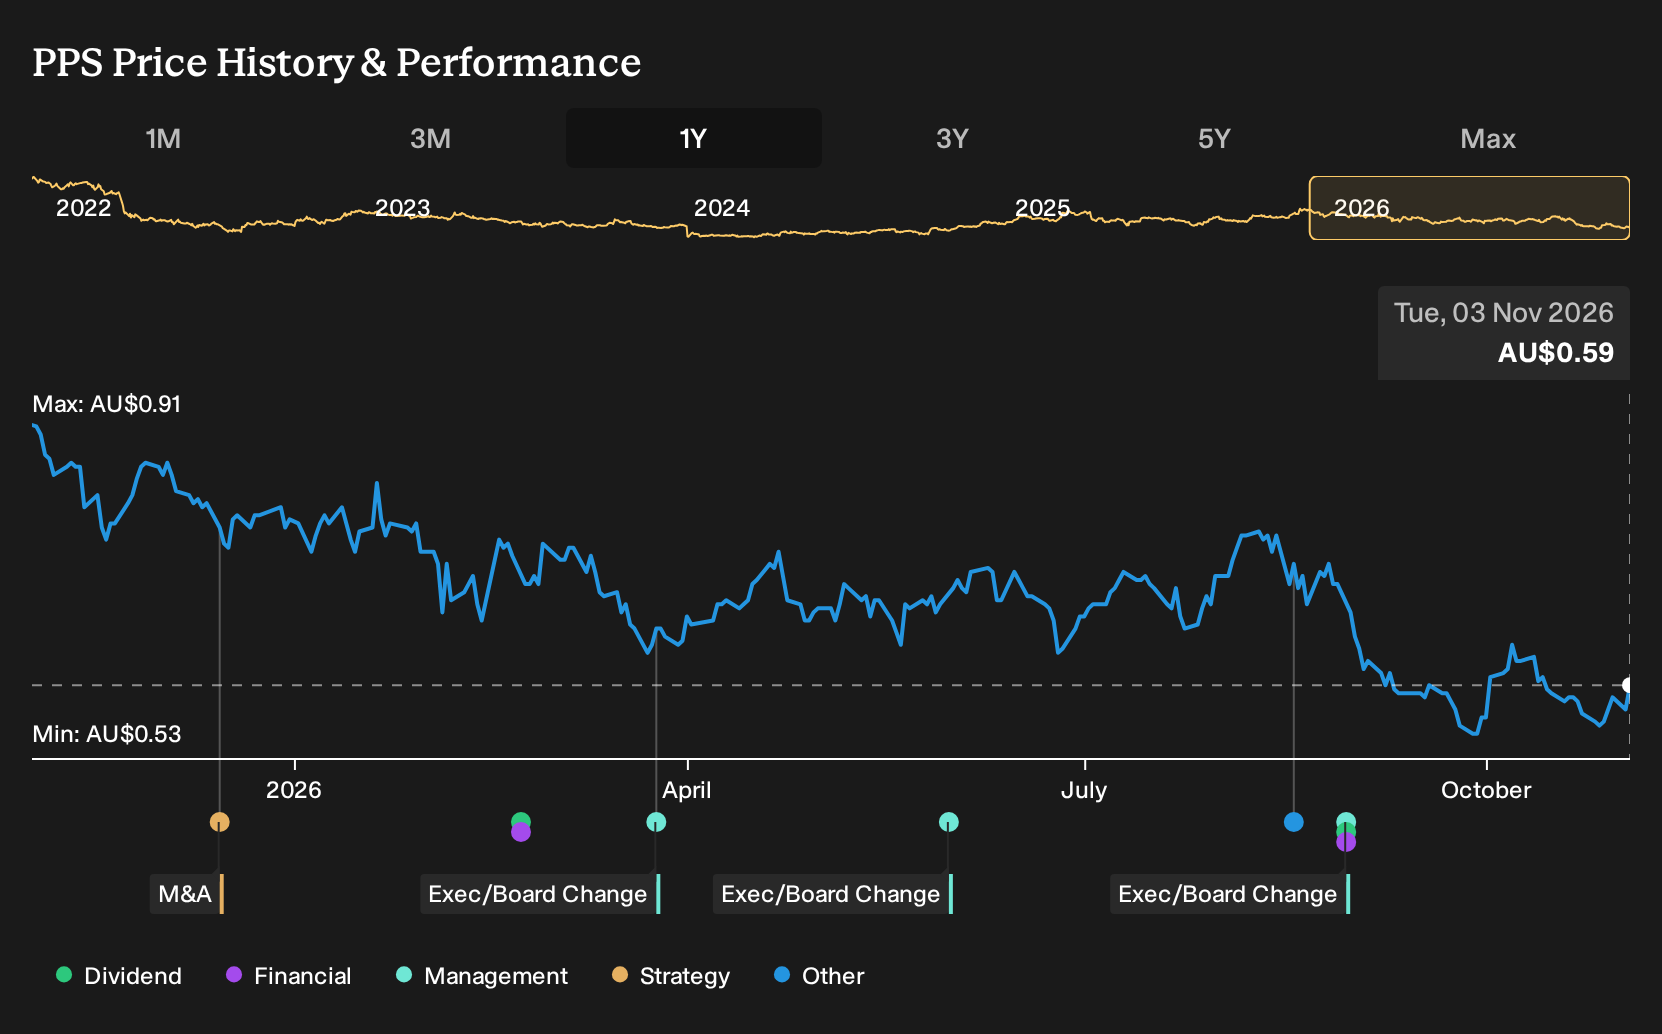
Praemium’s latest half year result landed with a jolt. Revenue was similar to a year earlier, yet profit swung from a gain to a loss and net margin moved from 11.9% in H2 2025 to a negative 6.5% in H2 2026. Investors who held Praemium over the past year are down 32.0%, including dividends. If you were deciding whether to buy at the start of that year, how much weight would you have put on that kind of profit risk?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Praemium. Zero in on 3 high quality undervalued stocks for companies trading below our estimates.
The Two Praemium Stories Investors Had To Weigh
The shares cost A$0.91 at the start of the period, so anyone looking at Praemium then was choosing between two very different stories.
The bullish Narrative put Fair Value at A$1.01, built on assumed revenue growth of 9.3% and profit margins rising to 17.7%. Supporters focused on Spectrum’s rollout, stronger client retention and expected cost synergies from OneVue.
The bearish view anchored Fair Value at A$0.78 and still assumed 7.6% revenue growth with margins of 16.2%. That camp fixated on rising regulatory costs and the risk that losing major clients could unsettle future revenue.
What The Results Changed For Praemium
The key fact was simple. Praemium booked total revenue of A$51.333m in H2 2026, similar to H2 2025, while profit moved from A$6.115m to a loss of A$3.314m and net margin shifted from 11.9% to a negative 6.5%. That outcome challenged the optimistic case for rising profitability and supported the more cautious narrative.
The lesson to carry across is about margins. When a thesis leans heavily on profit expansion, track reported net margin each period and test whether it is actually moving toward the assumption.
What Praemium’s Lower Price Asks You To Believe
Praemium now trades at A$0.59, and the selected Narrative’s Fair Value sits above that level based on its own assumptions rather than any proven fact.
The argument centres on high net worth advice, Scope+ administration and the technology overhaul. For the fall to look like an opportunity rather than a warning, a buyer would need confidence that cost savings translate into sustained cash EBITDA and margin strength.
"The main thing that has to go right is that Praemium turns its technology rebuild, OneVue integration, and about $12 million of targeted annual EBITDA and cost savings into durable cash EBITDA and margin strength despite lower reported free cash flow and platform revenue margins of 27 basis points."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 29% below our estimate - supplies hard to source truck and bus parts while solving fleet operators' maintenance problems.
- Company 2 - 17% below our estimate - sells cloud aligned software, security and AI solutions that large institutions bundle into managed IT deals.
- Company 3 - 32% below our estimate - expands multi brand electronics and appliance retail while folding installation and support into one transaction.
That is three of the list. See the full list of 12 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com