


Former IMF economist Gita Gopinath is warning that interest rates may stay higher for longer as the AI boom drives heavy investment and keeps inflation pressures alive. If money is no longer cheap, every dollar going into artificial intelligence hardware and software has to justify itself on price, not hype. This article highlights three listed businesses that our tool flags as potentially underpriced AI beneficiaries.
The three stocks below are a small sample, and the full screen on Simply Wall St surfaced 132 more listed AI companies with equally compelling stories that are not covered here. To go deeper into this opportunity set, head straight into the Undervalued Artificial Intelligence/ AI Stocks screener to identify, filter, and analyze the highest conviction ideas for your watchlist.
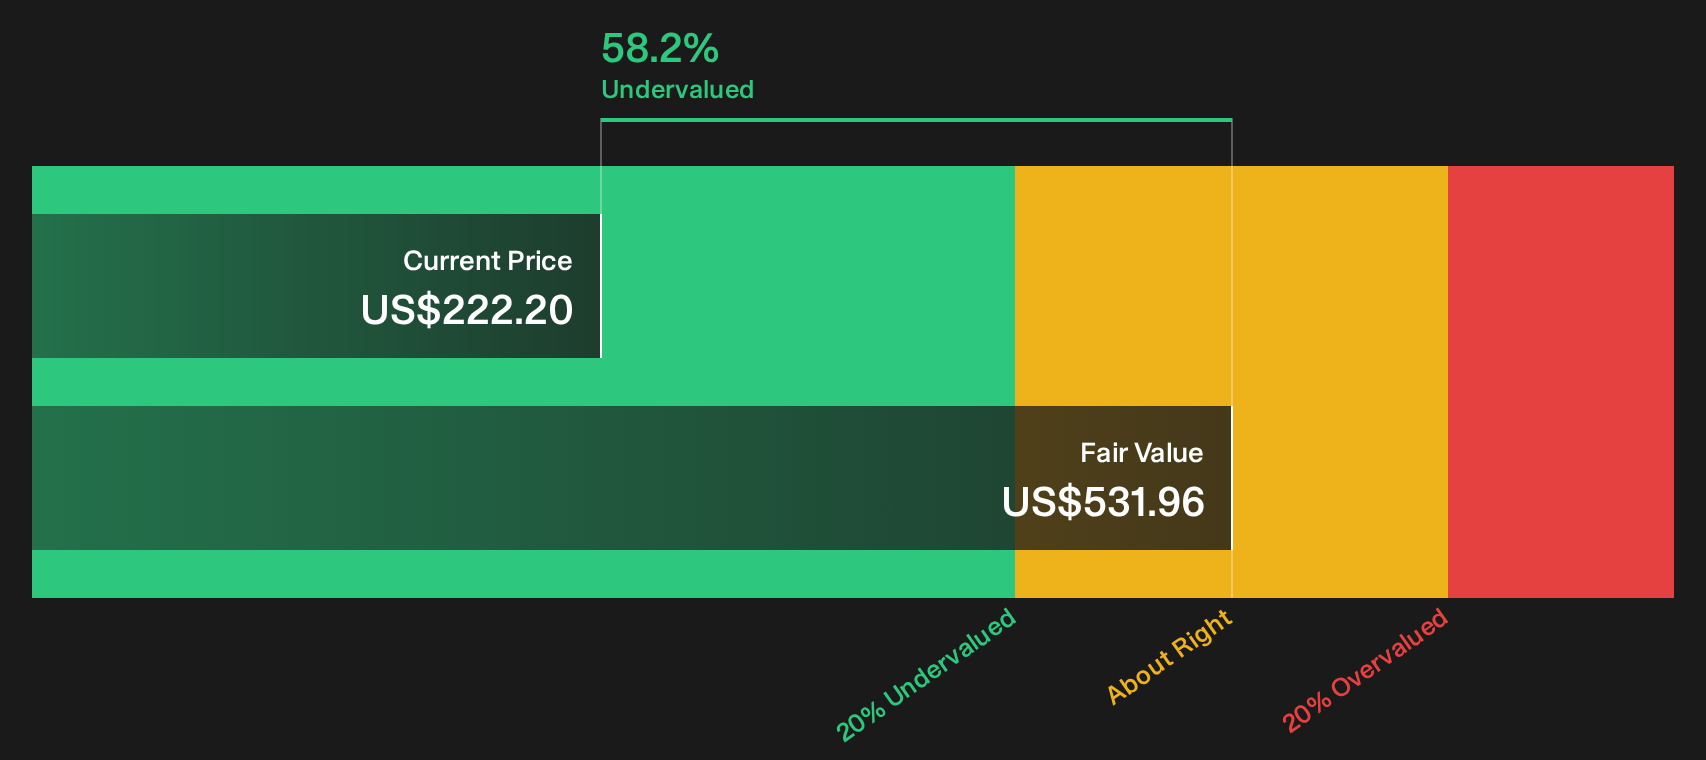
Salesforce (CRM)
Salesforce is a heavyweight in customer relationship management software, now wiring AI directly into those customer workflows through its Agentforce platform. This is why it appears in an AI-focused screen like this.
Salesforce runs a broad cloud-based CRM and data platform that now includes Agentforce AI agents, Data 360 as a context engine, and Slack as a conversational layer. It generates about US$43.9b from a single enterprise cloud segment and carries a market value near US$186.1b.
"If AI agents become the new interface for work, Salesforce can still win, but only if it becomes the system those agents rely on to operate safely within companies."
The real swing factor is how one subtle shift in how large customers choose to pay for that AI-driven work ends up feeding through to long term margins.
That margin question is exactly what the full narrative for Salesforce unpacks, showing where Salesforce could be accelerating value creation and where agent economics might quietly cap returns.
Broadcom (AVGO)
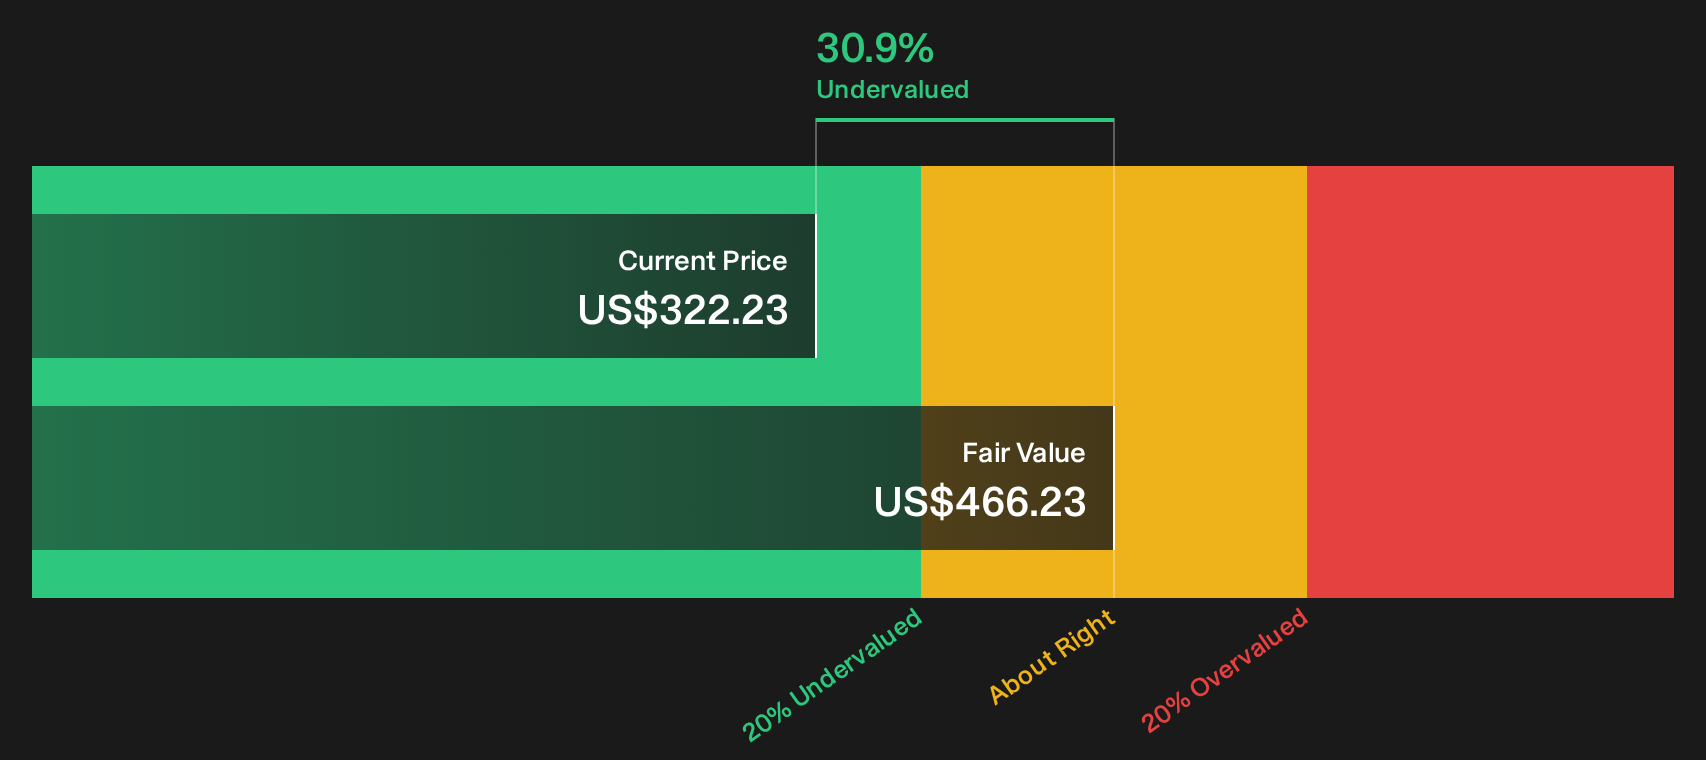
Broadcom is on this AI-focused list because its chips and software help large data centers run ChatGPT-style models at scale, yet the business is broader than that headline suggests.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
What happens if a single assumption about long-term AI infrastructure spending proves too optimistic and high-margin projects slow more quickly than expected?
That risk is only half the story, and the full narrative for Broadcom shows how Broadcom's AI, networking, and software engine could still be quietly accelerating value.
Super Micro Computer (SMCI)
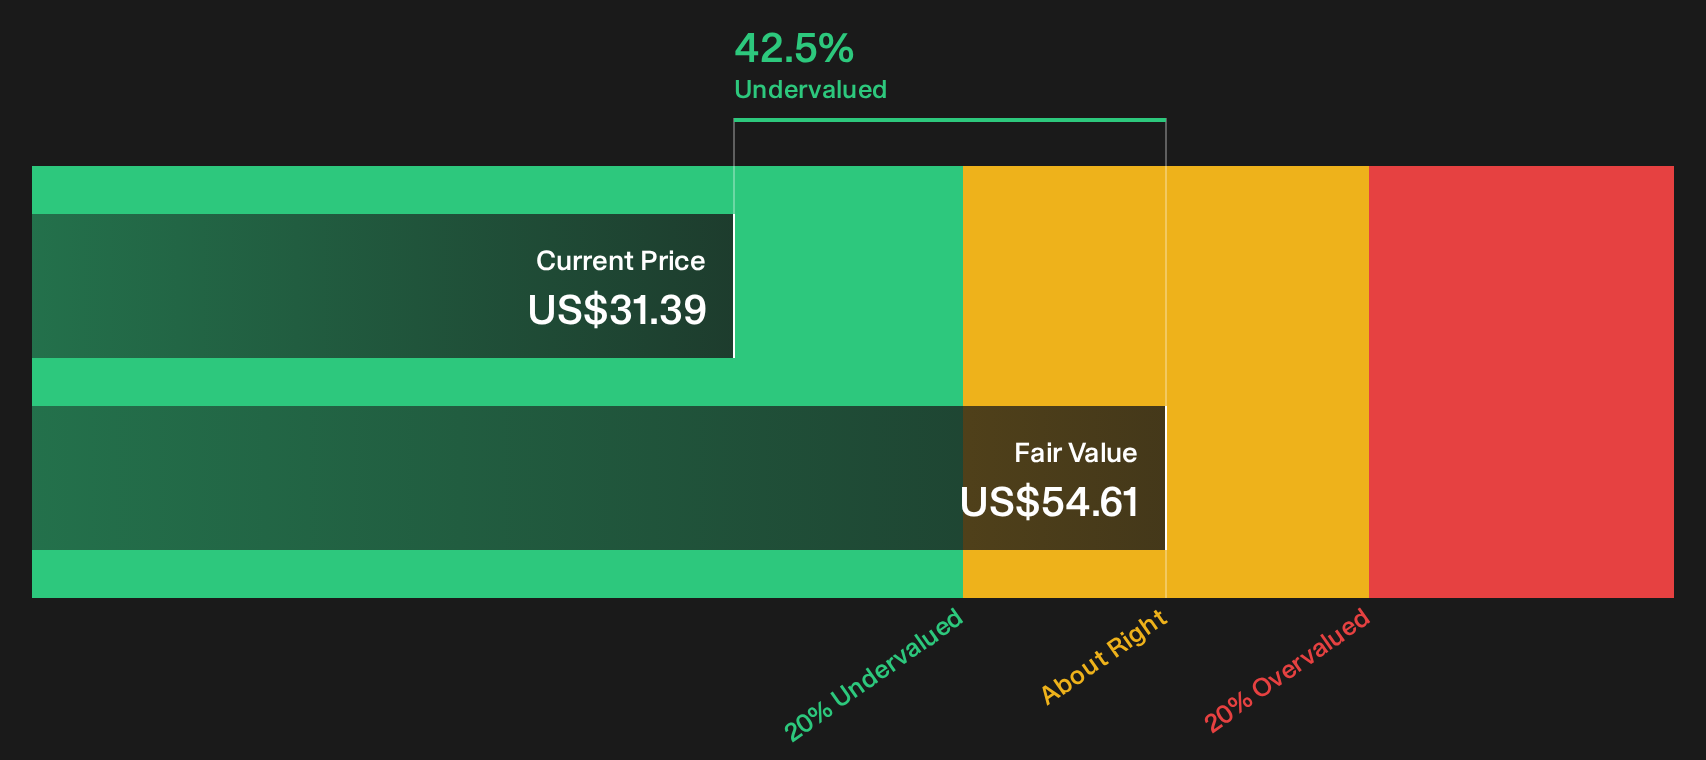
Super Micro Computer is another key pick for this AI-focused screen because its hardware is the physical kit that powers many GPU-heavy training and inference clusters behind ChatGPT-style workloads.
Super Micro Computer develops high performance server and storage platforms, with all US$39.1b of revenue coming from a single server solutions segment, and a roughly US$20.0b market value.
"The accelerating global adoption of AI and analytics continues to drive demand for high-performance, scalable server and data center solutions. This positions Super Micro Computer for multi year revenue growth as enterprises and nations build out AI infrastructure, which can support higher long term revenue and earnings."
The real test will be how one subtle shift in AI rack pricing filters through to long term margins and investor returns.
That pricing pressure is exactly what the full narrative for Super Micro Computer unpacks, separating short term rack volatility from where Super Micro Computer’s AI positioning could still be accelerating value.
Seeking Fresh Alternatives Before They Fly
Fresh AI stories are not the only place momentum can build. Before the crowd catches on and ideal entry ranges get caught in a breakout, scan these under the radar for now and consider adding them to your watchlist.
- Target resilient cash generators by running the list of solid balance sheet and fundamentals (23 results) and focus your watchlist on businesses built to handle tougher funding conditions.
- Spot early-shifting trends in medical technology through the 34 healthcare AI stocks and track companies using AI to reshape diagnostics, treatment planning, and hospital efficiency while it still matters.
- Position ahead of capital flowing into power infrastructure by reviewing the 42 power grid technology and infrastructure stocks and find operators tied to long term grid upgrades and reliability projects.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com