


Why Toromont Industries Stock Is Back In Focus
Toromont Industries (TSX:TIH) just paired strong third quarter 2026 results with a fresh dividend affirmation, a combination that gives investors new information on both earnings power and ongoing cash returns.
The strong third quarter update and dividend affirmation arrived alongside an 8.46% 1 day share price gain to CA$209.40, after a stretch where the 30 day share price return declined 11.53% and the 90 day share price return fell 7.62%. Toromont Industries still carries a 24.78% year to date share price return and a 30.25% 1 year total shareholder return that caps off a 101.86% 3 year total shareholder return, suggesting recent momentum had cooled before this latest rebound caught investors’ attention again.
Scan beyond Toromont Industries and line up other equipment and industrial operators showing strong fundamentals and recent momentum with the curated list of solid balance sheet and fundamentals (6 results)
Bulls see Toromont Industries pairing rising earnings with a steady dividend and treating the pullback as a clean entry point. Bears see a rich multiple after a long run. Which case does the valuation actually support?
Most Popular Narrative: 16% Undervalued
The prevailing narrative puts Toromont Industries fair value at about CA$247.91, comfortably above the last close at CA$209.40. This frames the current debate around whether the market is fully pricing in its earnings power.
The rapid ramp-up of AVL's production capacity, ongoing integration, and accelerated facility expansion in the U.S. positions Toromont Industries to capitalize on growing North American data center power demand. AVL revenues have scaled from $57 million in Q2 2025 to $171 million in Q2 2026, and a $1 billion AVL order for 2027 delivery supports future revenue and earnings.
See why 18 investors see Toromont Industries as 16% undervalued.
Result: Fair Value of CA$247.91 (UNDERVALUED)
Still, the narrative can crack if CIMCO's weaker profitability lingers, or if ongoing AVL related purchase commitment expenses keep depressing reported earnings and investor confidence.
Find out about the key risks to this Toromont Industries narrative.
Another View: Toromont Industries Through The P/E Lens
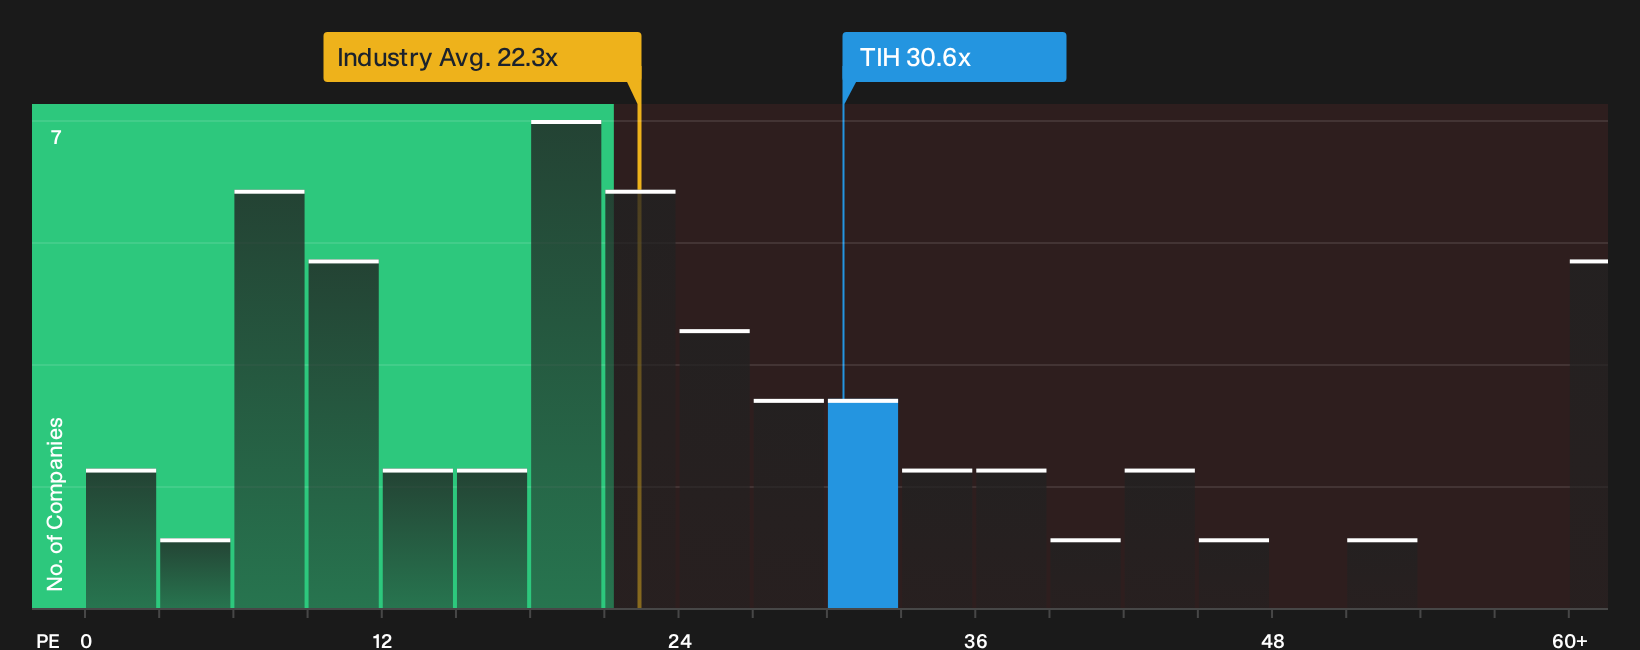
A second check on Toromont Industries leans on the P/E ratio rather than future cash flows. The shares trade at 30.2x earnings, which is higher than both the North American Trade Distributors industry at 22.3x and the peer average at 19.9x, yet still below an estimated fair ratio of 33.9x.
That mix points to a stock priced at a premium to sector and peer groups, while still carrying some room for re rating if the market moves closer to the fair ratio. This setup leaves investors weighing valuation risk against perceived quality and growth support.
To see how this pricing gap fits into a fuller breakdown of earnings power and risk, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Whether you are optimistic or cautious about Toromont Industries after these moves, you do not have to sit on the sidelines and wait for a verdict. Take a closer look at what the market is pricing in by reviewing the 3 key rewards
Looking For More Investment Ideas Beyond Toromont Industries?
Do not stop with Toromont Industries. Use this momentum to widen your watchlist with ideas that match your goals and risk comfort.
- Target robust payouts by scanning for income opportunities through 3 dividend fortresses that may suit a yield focused portfolio.
- Hunt for mispriced quality and see which companies line up in the 4 high quality undervalued stocks before other investors catch on.
- Prioritise resilience by checking the 9 resilient stocks with low risk scores and see which businesses score well on stability and risk controls.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com