


TETRA Technologies jumped 7.6% to US$5.95 after reporting Q3 2026 results, a sharp move for a stock that had fallen almost 30% over the past three months. Traders focused on the headline beat in energy services revenue and solid earnings per share; yet the real story sits on the income statement. Net margin over the last 12 months is just 1.5% compared with a much higher level a year earlier, and that squeeze, combined with a rich trailing P/E, puts the pressure point squarely on profitability.
Love the revenue beat at TETRA Technologies, but worried about thin margins and a rich P/E? Scan 35 high quality undervalued stocks to find businesses that pair stronger profitability with sturdier balance sheets.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$167.951m vs. US$153.239m (+9.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$6.848m vs. US$4.151m (+65.0%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.0462 vs. US$0.0311 (+48.5%)
- Trailing 12-Month Net Margin (Q3 2026 vs. Q3 2025): 1.5% vs. 19.7% (margin sharply compressed)
Tired of scrolling through dense earnings releases and walls of numbers? Get a clear visual read on TETRA Technologies with a full financial breakdown that highlights its profitability profile inside the company report for TETRA Technologies..
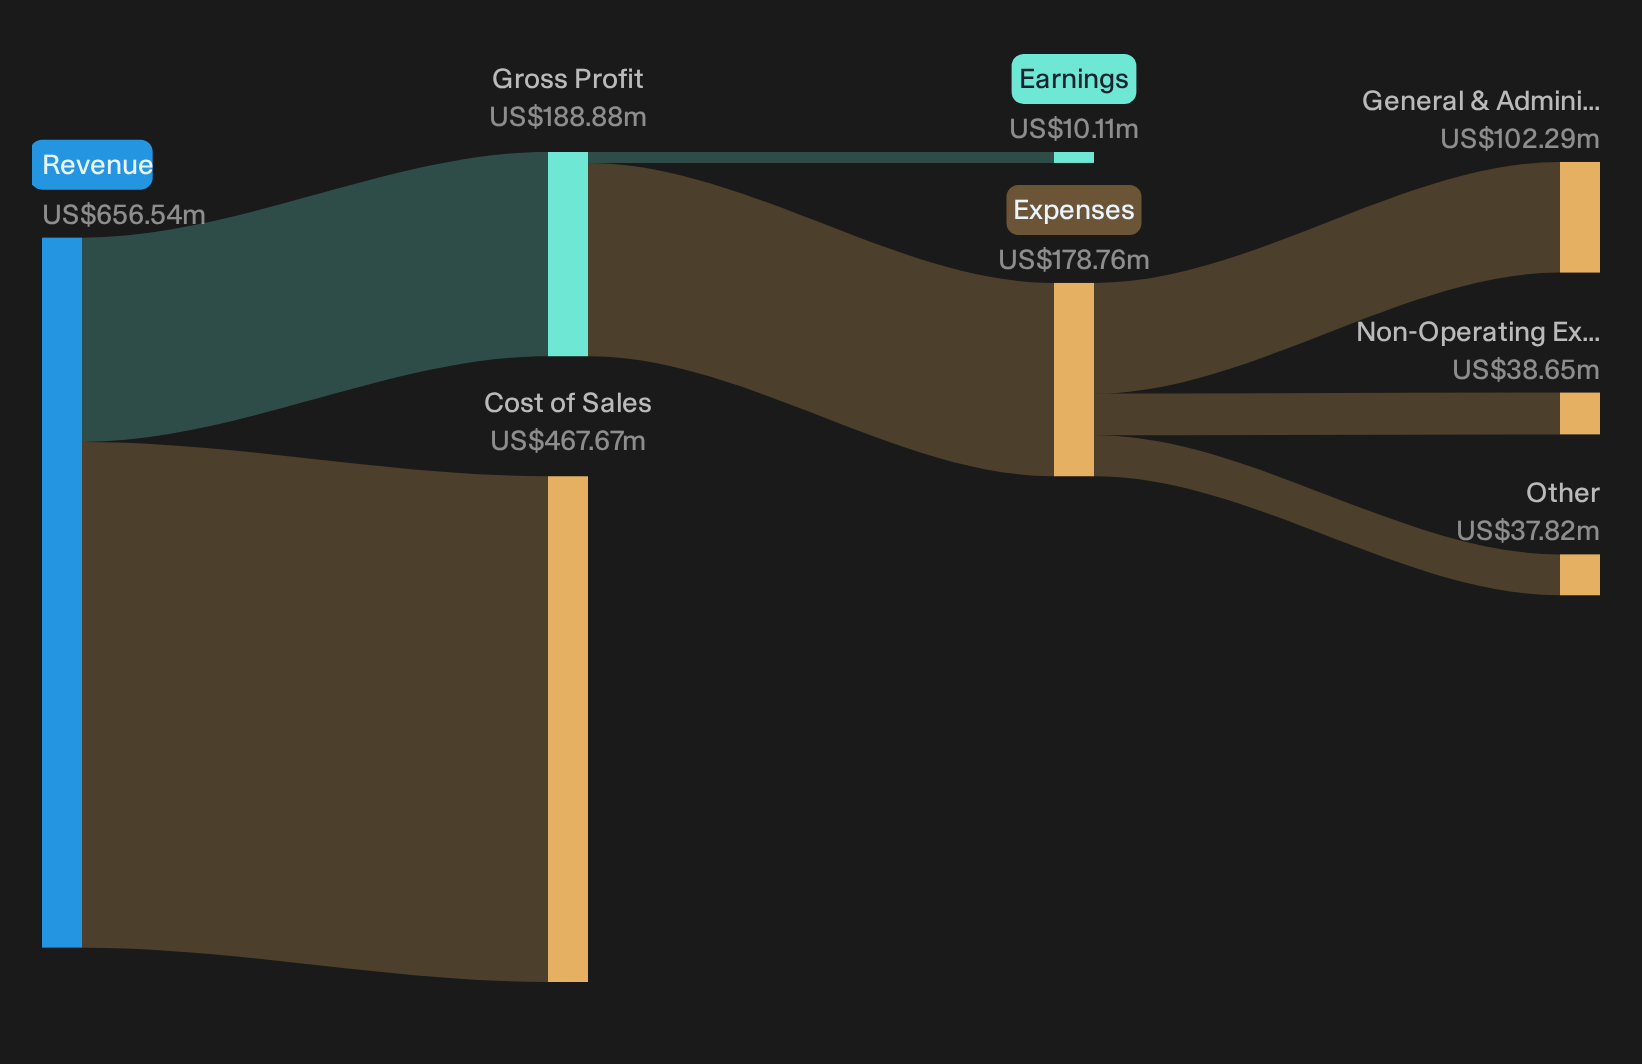
TETRA Technologies Starts To Validate Its 2030 Ambitions
Optimistic research hinges on TETRA Technologies turning long lead projects into dependable cash engines rather than just stories on a slide.
"The main factor that would need to go right is successful execution on the Evergreen bromine project and broader specialty chemicals and minerals plans, including moving produced water desalination and electrolytes from pilots and early contracts into durable cash flow at targeted margins."
Q3 gives concrete progress on that script. Industrial chemicals now exceed half of Completion Fluids & Products revenue, electrolytes and semiconductor wastewater show strong traction, and the Arkansas bromine plant remains on schedule and on budget. Water & Flowback margins improved, which hints that technology led offerings like SandStorm can support the cash flow shift the bullish camp wants.
One Narrative disagrees with today's price. → See where this Narrative says TETRA Technologies should trade.
Evaluating TETRA Technologies’ Execution Risks Against Q3 Reality
Worried that TETRA Technologies will never turn its project pipeline into dependable profit, rather than one off wins that fade quickly?
"Bearish analysts expect TETRA Technologies to struggle to convert its bromine, desalination and electrolyte projects into consistently profitable earnings given structurally low gross margins, subscale operations and reliance on external bromine supply until Arkansas production starts."
Q3 results do not resolve that concern. Industrial chemicals and electrolytes now drive more than half of Completion Fluids & Products revenue, yet group net margin over the last 12 months sits at 1.5%. Arkansas bromine remains at least a year from mechanical completion, so dependence on third party bromine and margin pressure is still present.
Hunt For Mispriced Cash Engines
TETRA Technologies just showed how a lively narrative can still meet the hard wall of slim net margins. The real opportunity sits in finding stocks that could be undervalued before the market corrects them.
- Company 1 - 28% below our estimate - uses digital engagement and financial inclusion tools to convert underpenetrated credit demand into fee and lending income.
- Company 2 - 49% below our estimate - spends heavily on AI infrastructure so ad tools, agents and devices can translate compute capacity into commercial demand.
- Company 3 - 45% below our estimate - co-designs critical hardware with clients under a sketch-to-scale model that embeds know how into industrial and AI systems.
Three companies from the same screener. Open every one of the 35 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com