


TransAlta (TSX:TA) drew fresh attention after its latest quarterly report showed net income of CA$77 million for the third quarter, compared with a loss a year earlier, despite lower sales.
The latest earnings swing back into profit has coincided with a 1-day share price return of 3.99% and a 30-day share price gain of 5.29%. However, the 1-year total shareholder return is still down 20.07%, while the 3-year total shareholder return is up 78.97%. This suggests that long-term holders have seen strong gains even as recent momentum has only started to rebuild.
Scan beyond TransAlta and explore other utilities that may be positioned for the next leg of returns with our curated list of 42 power grid technology and infrastructure stocks
TransAlta has swung back to profit, and the share price has started to respond. The tougher question is whether that improving story is already fully reflected in today’s CA$18.52 market price.
Most Popular Narrative: 21% Undervalued
On the most followed view, TransAlta’s CA$18.52 share price sits at a discount to an implied fair value of CA$23.50. That gap hinges on how convincingly future contracted cash flows and data center related projects materialise.
Ongoing execution of renewable development, repowering and asset optimization, including the planned coal to gas conversion of Centralia Unit 2 targeting a final investment decision in Q1 2027 and expected C$150 million of annual EBITDA from 2029, supports the case that future contracted and semi contracted cash flows could lift overall earnings and free cash flow.
See why 27 investors see TransAlta as 21% undervalued.
Result: Fair Value of CA$23.50 (UNDERVALUED)
Still, the TransAlta story can break if softer Alberta power prices persist or if Centralia conversion costs and project debt reduce cash flow more significantly.
Find out about the key risks to this TransAlta narrative.
Another View: Market Ratio Sends A Different Signal
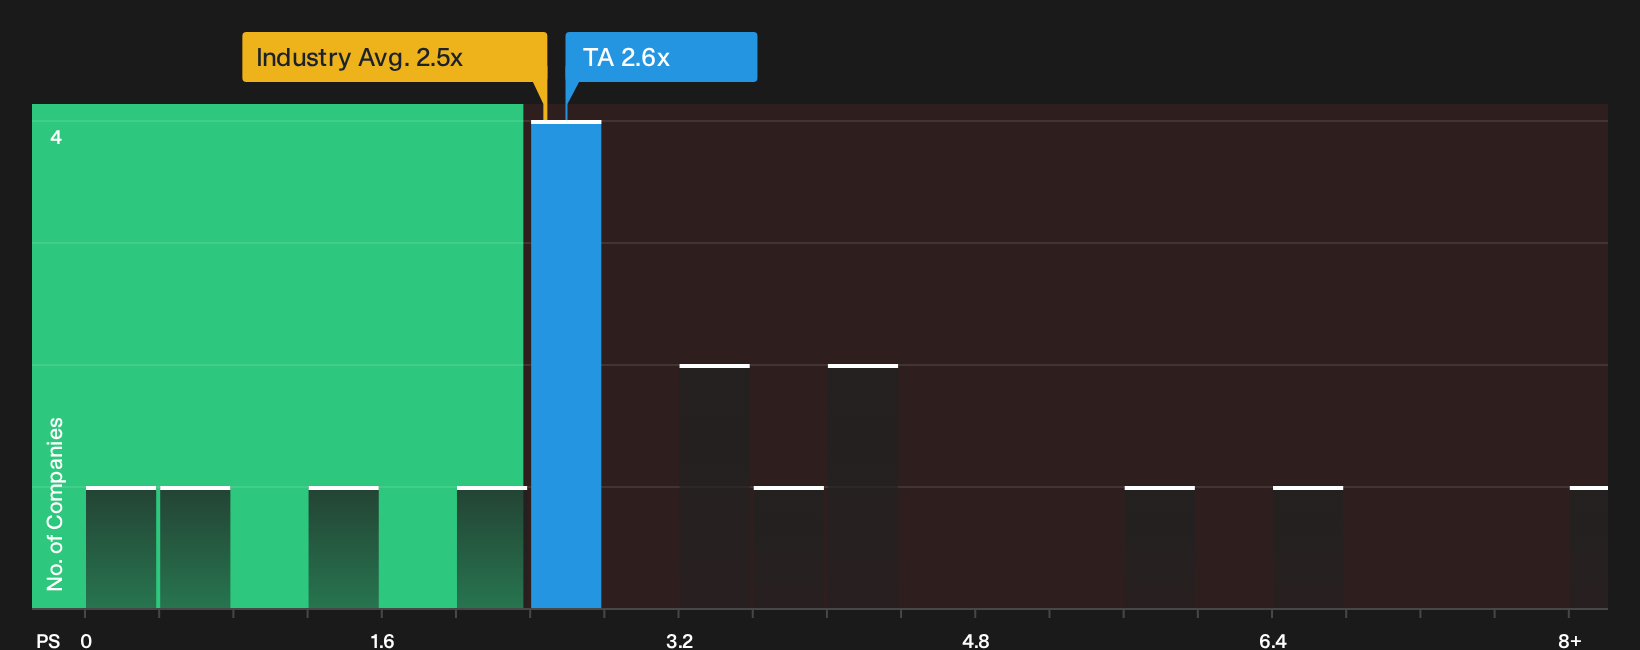
There is a sharp contrast once P/S is used instead of analyst fair value. TransAlta trades on a P/S of 2.6x, compared with both the peer group and North American renewable energy averages at 2.5x. A fair ratio estimate of 1.5x points to valuation risk if sentiment cools.
That spread suggests the market already prices in a fair amount of future execution, leaving less room for disappointment if data center demand or Centralia returns fall short. It is therefore worth asking which metric you trust most when expectations are this loaded.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split sentiment around TransAlta leaves you torn, move quickly and examine the numbers yourself before the narrative changes. To balance the risks with what investors already view as potential upside, review the 3 key rewards.
Looking for more investment ideas beyond TransAlta?
If TransAlta has sharpened your interest, do not stop here. Fresh opportunities emerge constantly, and the right shortlist can tilt the odds in your favor.
- Zero in on dependable cash generators by scanning companies with strong payouts and resilient income streams through 3 dividend fortresses.
- Hunt for mispriced quality where fundamentals and valuation both matter by working through the 4 high quality undervalued stocks.
- Prioritise resilience over drama and focus on balance sheets built to withstand shocks using the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com