


IDEXX Laboratories came into this Q3 2026 report priced for excellence, with the stock roughly flat on the day around US$672 despite a long run of strong returns over the past month. The immediate reaction was a shrug. The results were anything but.
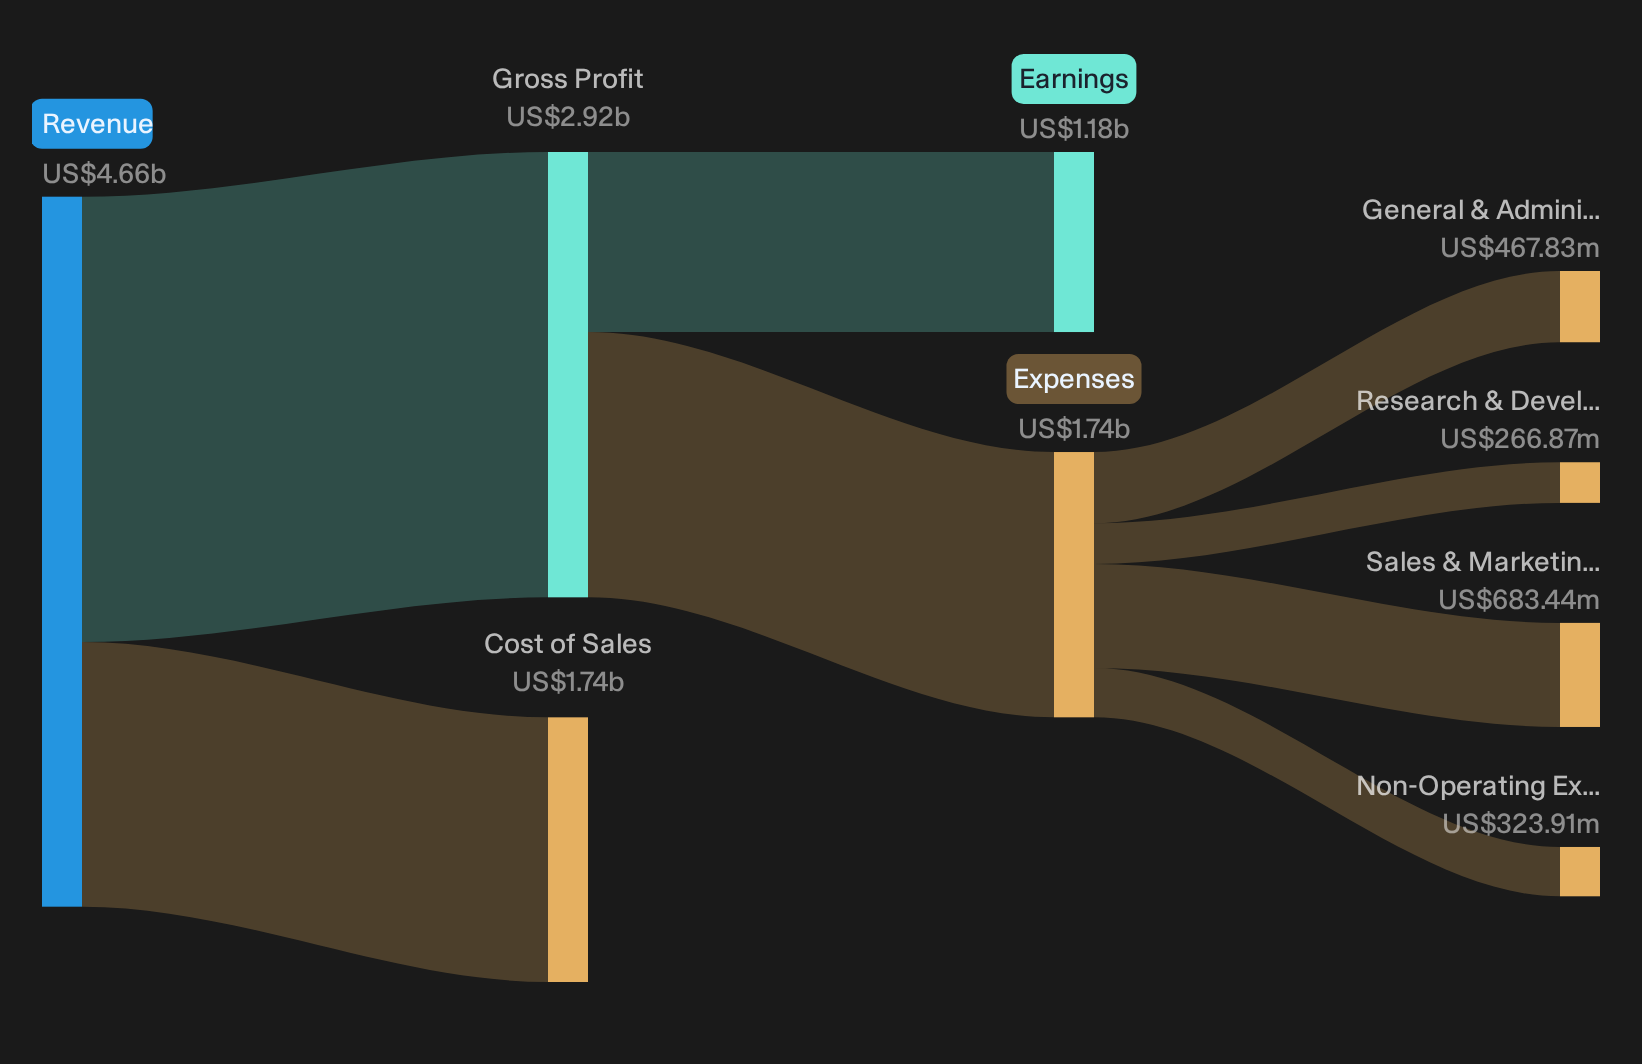
The veterinary diagnostics giant posted Q3 revenue of about US$1.21b and basic earnings per share of US$4.02, alongside free cash flow of US$421m in the quarter. For a business already trading on a rich P/E multiple, that kind of cash generation sits at the center of the story investors now need to weigh against the lofty valuation.
Love IDEXX Laboratories cash generation but worried about paying up for a premium P/E multiple? Screen for companies that pair strong free cash flow with more grounded valuations in our 35 high quality undervalued stocks.
IDEXX Laboratories Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,214.2m vs. US$1,105.2m (up about 9.9%)
- Net Income (Q3 2026 vs. Q3 2025): US$317.1m vs. US$274.6m (up about 15.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$4.02 vs. US$3.43 (up about 17.4%)
- Operating Margin (Q3 2026 vs. Q3 2025, reported): approximately 33.1%, with the prior-year quarter not specified (management highlights improvement on a comparable basis)
Cancer Dx is now a multi-cancer panel at routine-test prices. Ask Charlie what makes IDEXX’s Cancer Dx a tipping point.
Evaluating Whether IDEXX Is Really Winning On Per‑Visit Testing
The bullish story hinges on IDEXX Laboratories turning each vet appointment into a richer diagnostics event, not just selling more boxes.
"The main thing that has to go right is that IDEXX Laboratories continues to increase diagnostic utilization per visit globally, despite recent declines in U.S. wellness and clinical visit volumes, while successfully scaling its direct commercial and software-led model in underpenetrated markets."
Q3 data gives concrete support. Same store clinic visits in the U.S. slipped about 1.8%, yet CAG diagnostics recurring revenue grew roughly 11% organically, more than 1,000 bps ahead of traffic for the fourth straight quarter. Cancer Dx attach rates, VetLab consumables at 15% organic growth, inVue Dx analyzers at around 11,000 installed and double mass checks for early FNA users all point to more tests per visit, particularly as nearly half of inVue Dx placements and faster international CAG growth highlight progress in underpenetrated markets.
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for.
IDEXX bearish test: intensity risk still unproven
The key worry is that IDEXX Laboratories eventually hits a wall on how much testing each appointment can realistically support.
"...this growth premium depends on continued mix shift into higher value testing and may be hard to sustain if visit weakness persists or clinics reach practical limits on test intensity per visit, which could eventually restrain revenue growth and compress operating margin expansion."
Q3 shows the strain point has not arrived yet. Same store U.S. clinic traffic slipped 1.8%, while CAG diagnostics recurring revenue grew about 11% organically and global reference lab revenue advanced 10%. Operating margin for the quarter was roughly 33.1%. The raised full year revenue and EPS outlook indicates that, for now, test intensity is still outrunning visit softness rather than buckling under it.
Hunt For Underpriced Earnings Power
IDEXX Laboratories just reported earnings that shifted how investors view its underlying earnings power. The real opportunity could sit in stocks that appear misaligned with fundamentals before pricing adjusts.
- Company 1 - 28% below our estimate - positions specialized chips, custom silicon and networking gear for rising data traffic processing, connection and security.
- Company 2 - 30% below our estimate - ties subscription software, AI workloads and usage-based cloud services into infrastructure that deepens customer integration.
- Company 3 - 45% below our estimate - converts a large, long-duration project backlog into higher-margin construction work while resolving legacy legal disputes.
Those are three of them. See all 35 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com