


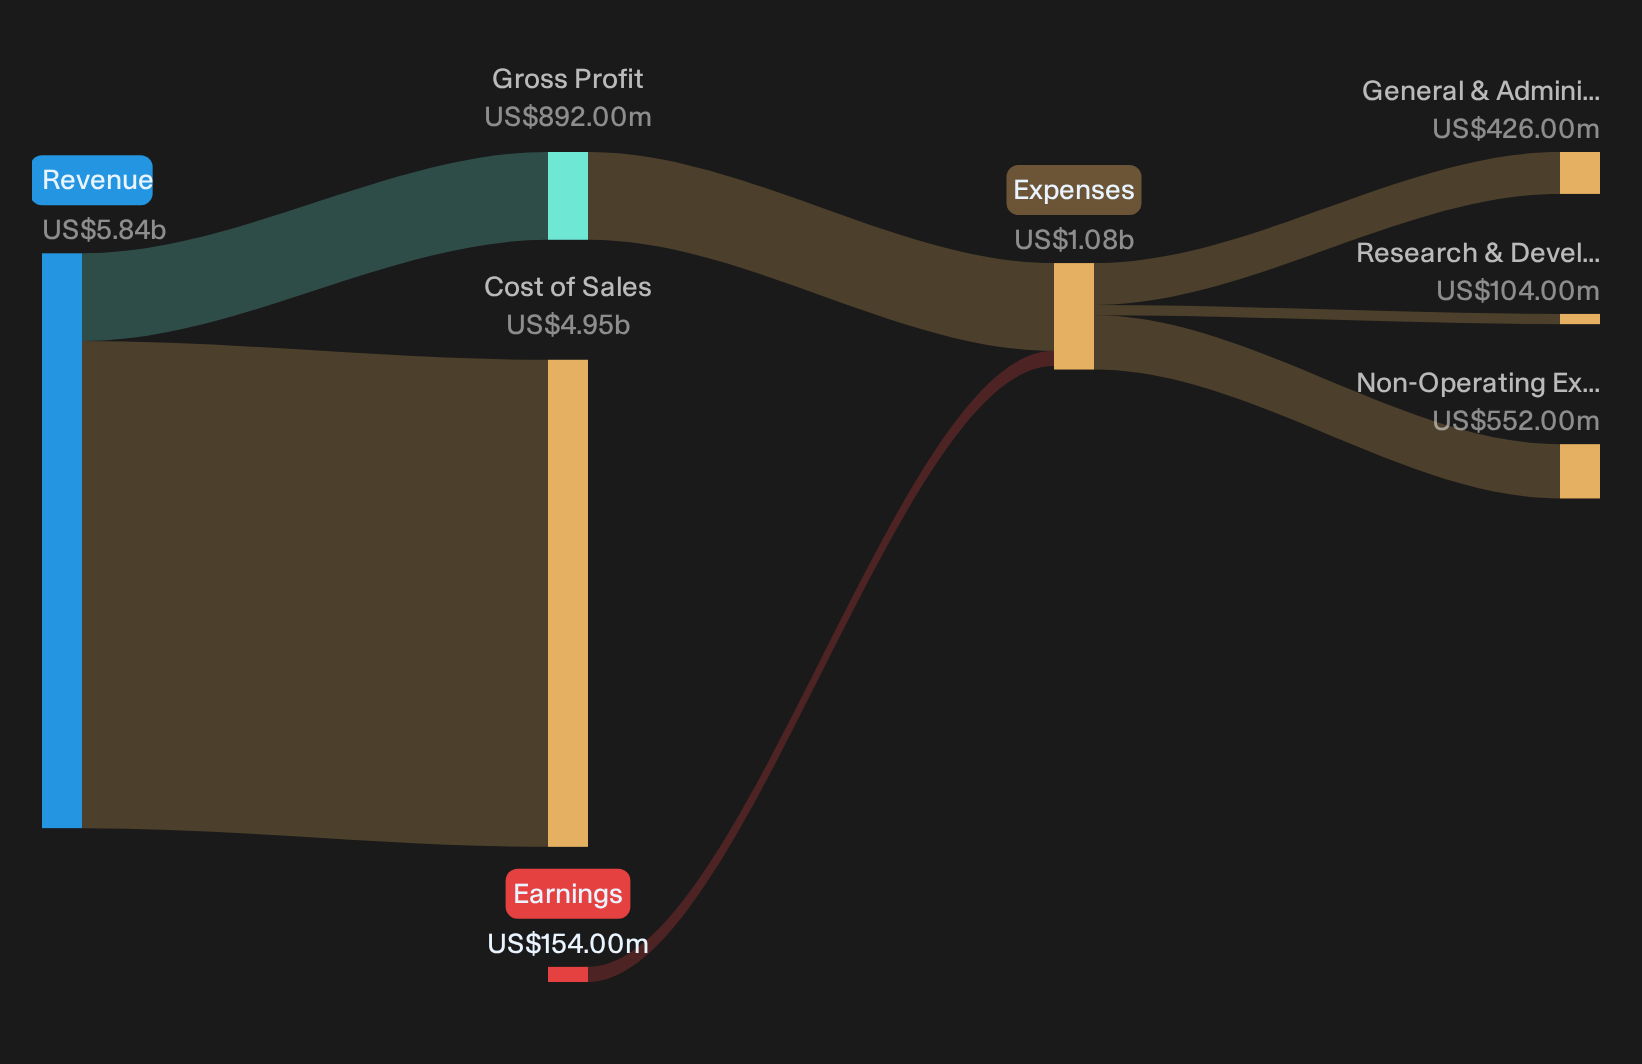
Chemours stock barely flinched after Q3 2026 earnings, slipping just 0.5% to about US$13 even after a sharp rebound in profitability. The headline is simple. The firm swung from heavy losses earlier this year to Basic EPS of US$1.29 on US$1.54b in sales.
Short term traders see a sleepy chart, with the share price down about 10% over the past three months. Long term investors see something different: a chemicals producer that remains loss making over the past year but is priced at a low P/S multiple against an anticipated earnings recovery story.
Impressed by Chemours returning to positive earnings but uneasy that it is still loss making over the past year? Look at our screener of low-debt, cash-generative stocks using the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,540 million vs. US$1,495 million (up about 3%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): profit of US$196 million vs. profit of US$60 million (sharply higher profitability)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.29 vs. US$0.40 (more than tripled per share earnings)
- Trailing 12-Month Net Income (Excl. Extra Items, TTM to Q3 2026 vs. TTM to Q3 2025): loss of US$154 million vs. loss of US$337 million (narrowed full year loss)
Tired of scrolling through walls of Chemours figures and footnotes just to understand what changed this quarter? See the full visual breakdown of Chemours, with a clear view of its earnings profile and overall financial picture, in the interactive company report for Chemours.
Chemours’ AI Cooling Ambition Meets Early Proof Points
Chemours bulls argue the real prize is shifting the portfolio toward higher value cooling and materials tied to AI and electronics.
"The main thing that has to go right is that Chemours continues to grow higher value Opteon and Performance Solutions volumes into data center, semiconductor and advanced electronics uses, while keeping Titanium Technologies positioned as a low cost, price disciplined chloride TiO₂ producer and managing PFAS and regulatory exposures."
Q3 gives partial confirmation. Advanced Performance Materials posted 26% Performance Solutions growth with strong AI and data center demand, and Faizeon and new Opteon grades broaden that footprint. Titanium Technologies pricing was firm and PFAS settlements progressed, although TSS still feels refrigerant destocking and softer aftermarket volumes.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Chemours Bear Case: Weak Refrigerants And Cash Drag
"Although Chemours highlights quota based refrigerant economics and prior strength in Freon and Opteon, the disclosed oversupply in the stationary AC aftermarket with aftermarket Opteon volumes expected to be about 25% lower year over year and roughly US$65 million of 2025 sales pulled into 2026 risks a longer reset in refrigerant demand patterns that could leave revenue and segment margins structurally below what current expectations assume."
Chemours’ Q3 numbers still echo that concern. TSS is guided to another high teens to low 20s % sequential sales drop in Q4, with EBITDA pressured by seasonal volume and lingering destocking. Management also cut 2026 free cash flow conversion to a range of 15 to 20% as PFAS settlements and related cash items absorb liquidity. Net leverage is guided below 4.2x, which helps, but multi year settlement payments keep the cash drag alive. Performance Solutions growth and TiO₂ pricing progress are not yet strong enough to clearly offset these refrigerant and PFAS headwinds.
Hunt For Quiet Mispricings
Chemours recently reported a change in earnings that did not immediately shift its share price. The real opportunity is studying stocks that could be undervalued before broader market pricing adjusts.
- Company 1 - 45% below our estimate - focus on scaling a pure-play aviation aftermarket platform by integrating a major acquisition and deepening engine repair partnerships.
- Company 2 - 17% below our estimate - build on a growing tracker backlog while expanding newer storage and inverter offerings to offset project delays.
- Company 3 - 47% below our estimate - shift the storage controller mix toward enterprise and automotive solutions as AI demand pulls more sales into higher value products.
Three companies from the same screener. Open the full list of 34 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com