


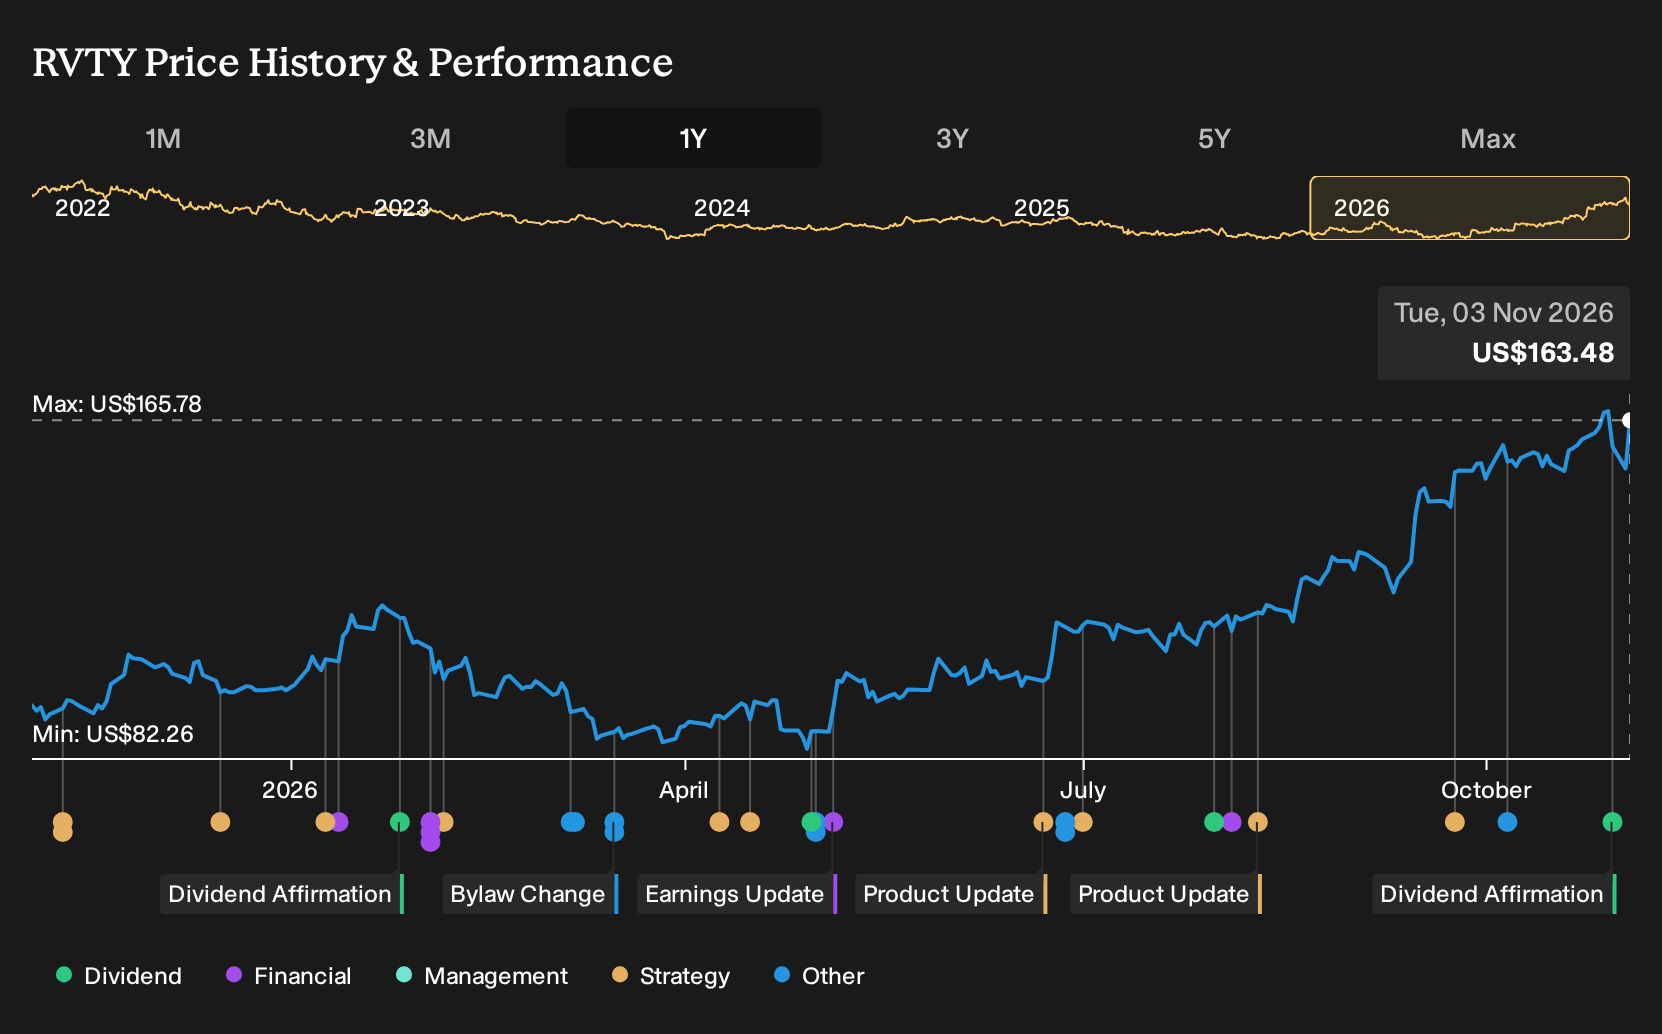
- Revvity reported third quarter 2026 sales of US$728.9 million and net income of US$62.3 million, with diluted EPS from continuing operations of US$0.56, and also raised full year revenue and earnings guidance after stronger than expected performance across Life Sciences and Diagnostics.
- The business paired this earnings beat with a regular US$0.07 per share quarterly dividend declaration, which signals ongoing cash generation priorities even as management invests behind AI related demand, reproductive health programs and ex China immunodiagnostics.
- The next area of focus is how Revvity's raised full year guidance could reshape its investment narrative around margins, software and diagnostics.
Scan beyond Revvity's latest earnings beat and dividend update by reviewing hand picked peers in the 34 healthcare AI stocks that are also tied to rising AI related demand in diagnostics and life sciences.
Revvity Investment Narrative Recap
To own Revvity, you really need to believe the Life Sciences, diagnostics and software mix can turn mid single digit top line progress into healthier earnings and cash generation. The latest quarter supports that narrative, with US$728.9 million in sales and US$62.3 million in profit, plus raised full year guidance pointing to a firmer operating footing.
The most immediate upside catalyst is execution in AI linked lab tools, Signals software and higher value diagnostics as management targets upper 20s margins. The biggest risk sits in that execution bar rising after consistent beats, especially with prior one off items and a rich P/E already in play, so any stumble could matter.
The cleanest news item to focus on is the third quarter 2026 earnings release. Revenue of US$728.9 million and diluted EPS from continuing operations of US$0.56, with adjusted EPS at US$1.38, show the current run rate that management used to support higher full year sales and earnings guidance.
For you as a shareholder, that report ties directly into the key catalysts. AI related demand, Signals ARR growth and reproductive health and ex China immunodiagnostics all sit behind the improved margin outlook. The risk is straightforward: if those engines slow, the raised 2026 expectations and premium valuation could quickly feel stretched.
Revvity's narrative projects US$3.3b revenue and US$540.0 million earnings by 2029. That profile is based on analysts assuming 4.4% yearly revenue growth and an earnings increase of about 2.3x from US$237.4 million today.
Uncover why Revvity's fair value indicates a 10% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Revvity’s Signals and AI tools as the real swing factor. Before this earnings release, that group was modeling revenue of about US$3.4b and earnings near US$725.8 million by 2029, far above consensus. You can treat this as one possible path and compare it with more cautious viewpoints.
Explore 2 other Revvity fair value estimates, including one that suggests as much as 7% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Revvity research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Revvity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Revvity's overall financial health at a glance.
Looking for more investment ideas beyond Revvity?
If Revvity has sharpened your thinking but you want a wider watchlist, use the Simply Wall St Screener to line up other companies that fit the kind of risk, quality and income profile you care about most.
- If you want potential value coupled with quality fundamentals, start by scanning a curated set of 34 high quality undervalued stocks that may warrant a closer look.
- For investors who care most about balance sheet strength and resilience through different cycles, filter for businesses in the list of solid balance sheet and fundamentals (24 results) and see which ones match your risk tolerance.
- If you prefer to hunt for less crowded opportunities, sort through a focused group of 19 high quality undiscovered gems that combine strong financial profiles with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com