


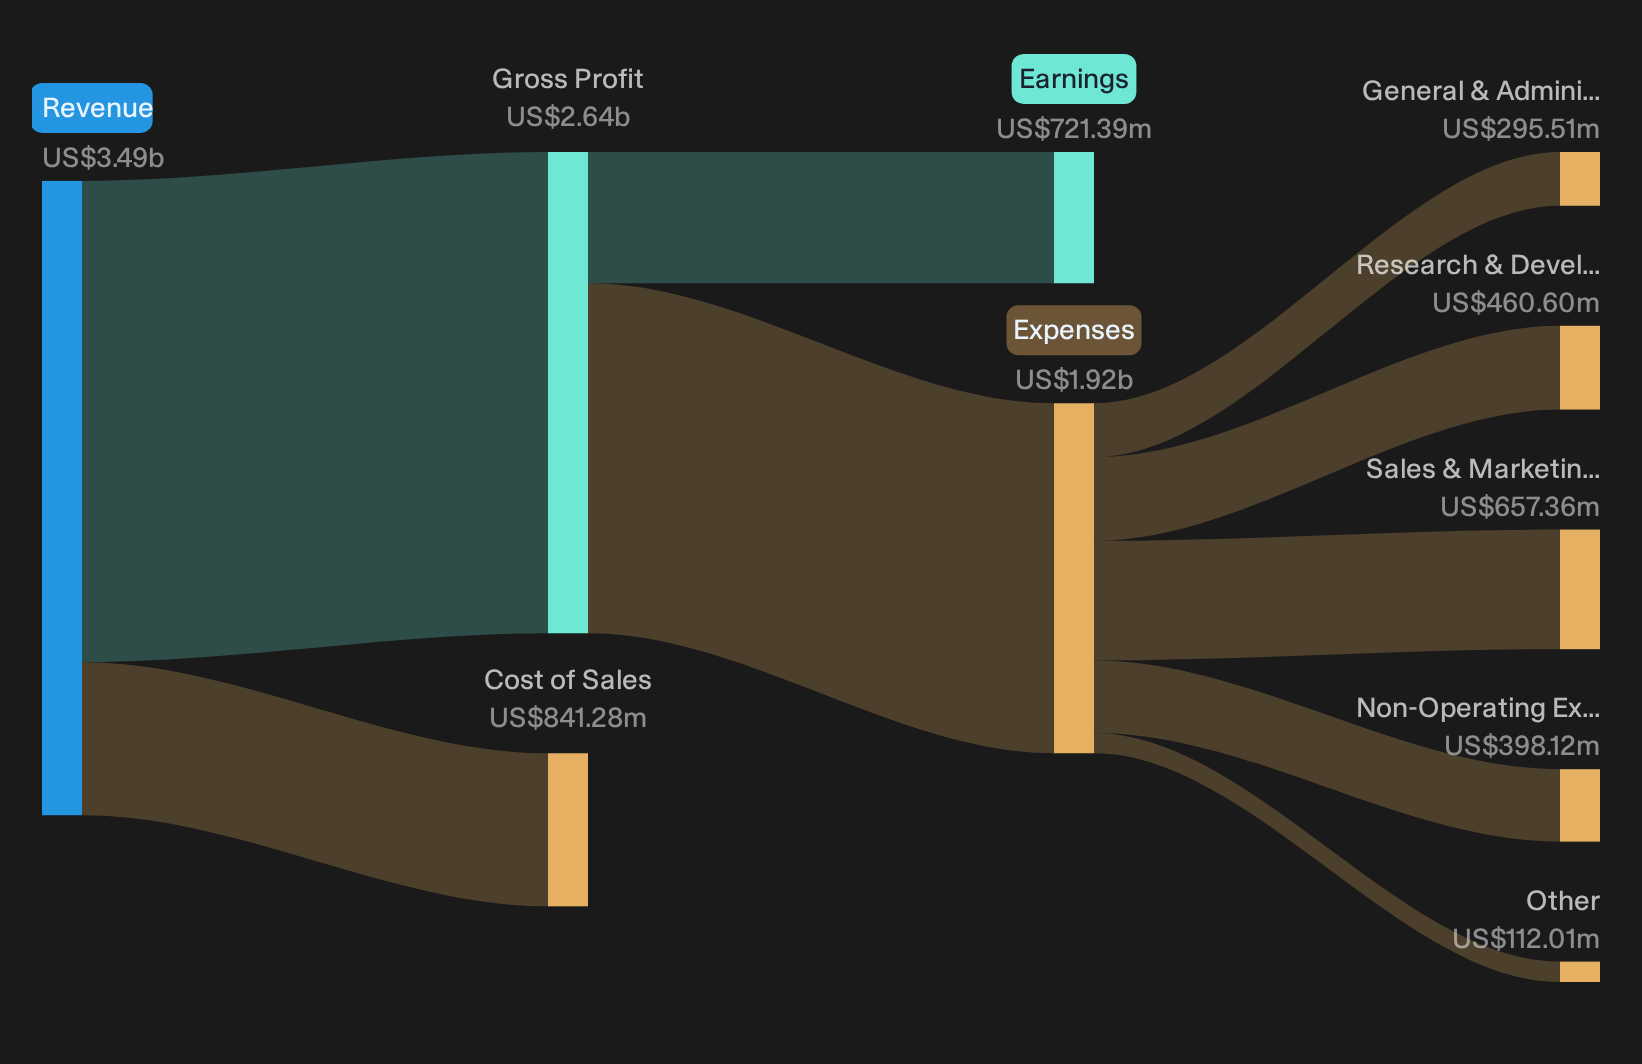
Match Group just took an 8.5% hit, with the stock closing at US$38.50 after investors digested its Q3 2026 report. The reaction looks harsh next to a quarter that delivered US$891.232 million in revenue and basic earnings per share of US$0.76. That move tells you traders are focused on the next few quarters. Over the longer term, the real story is a dating platform operator that has pushed its trailing 12 month net margin to 20.7% and is wrestling with how much future growth those profits can justify.
Like the profitability story at Match Group but uneasy about how much future growth that 20.7% net margin can support after a sharp 8.5% price move? Check out our hand picked list of sturdier peers in the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$891.2 million vs. US$914.3 million (top line declined 2.5%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$174.4 million vs. US$160.7 million (profit increased 8.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.76 vs. US$0.67 (earnings per share increased 13.7%)
- Trailing 12-month Net Profit Margin (Q3 2026 vs. Q3 2025): 20.7% vs. 16.2% (margin improvement of 4.5 percentage points)
Daily active users finally turned positive at Tinder after years of decline. Ask Charlie what’s actually driving Tinder’s Match Group turnaround.
Evaluating Match Group’s User Recovery Milestones
The bullish storyline says Match Group can turn product work into better engagement and more payers, especially at Tinder and Hinge.
"The main thing that has to go right is that Tinder, Hinge and the prioritized Everyone & Everywhere brands keep improving user outcomes and monetization enough to offset ongoing payer declines and pressure on the de prioritized apps."
Q3 hits part of that bar. Tinder finally returned to daily active user growth after more than three years and narrowed payer declines. Hinge delivered about 19% revenue growth with higher global MAU and improving registrations. That said, consolidated revenue still fell and Everyone & Everywhere pressure persisted, which limits how fully this user recovery thesis is playing through today.
The price and this Narrative do not agree. → Uncover what this Narrative says Match Group is actually worth.
Match Group Bear Case: Payer Slide Still Bites
The cautious view argues that Tinder’s product push will not fix payer erosion quickly enough to protect Match Group’s fundamentals.
"Although Match Group is increasing product velocity at Tinder through heavy use of AI generated code and centralized tooling, Tinder payers still fell 5% year over year in Q2 2026 and management only targets a return to payer growth by Q4 2027."
Q3 shows some healing but not a full rebuttal. Tinder daily users finally grew again and payer declines improved to roughly 4%. Yet direct revenue still slipped, total paying users fell 5%, and group revenue declined 2.5%. That mix supports the concern that engagement is recovering faster than spending. This keeps the bearish narrative in play for now.
Hunt For Mispriced Growth Stories
Match Group just reminded investors how quickly sentiment can change around a single quarter. The real opportunity is spotting stocks that could be undervalued before expectations reset.
- Company 1 - 43% below our estimate - uses larger LED boards, transit signage and youth sports upgrades to convert project backlogs into higher margin display and service work.
- Company 2 - 23% below our estimate - converts demand for grid testing gear and aerospace components into higher value diagnostic systems as utilities and defense programs refresh equipment.
- Company 3 - 49% below our estimate - turns heavy spending on AI data centers into ad tools, business messaging and devices that deepen advertiser targeting and user engagement.
That is three of the list. See the full list of 34 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com