


Nippon Light Metal Holdings stock closed at ¥2,612 on 2 November, capping a tough run that saw the share price fall about 10% over the past three months. Then the Q2 2027 results were released, with basic earnings per share of ¥87.08 and net income of ¥5,368m, and the near term story looked very different to the recent chart.
The key issue now is the time frame. Short term price weakness contrasts with a trailing 12 month earnings picture that corresponds to a low 7.4x P/E. At the same time, forecasts that point to declining revenue and profits are pulling longer term expectations in the opposite direction.
At this point Nippon Light Metal Holdings looks like a low P/E story with earnings on the table but a cloudy revenue outlook. If you want stocks where strong profits line up with healthier growth expectations, it is worth comparing this setup against our 17 high quality undervalued stocks.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥171,474m vs. ¥141,580m (up about 21%)
- Net Income (Q2 2027 vs Q2 2026): ¥5,368m vs. ¥3,348m (up about 60%)
- Basic EPS (Q2 2027 vs Q2 2026): ¥87.08 vs. ¥54.39 (up about 60%)
- Trailing 12-Month Net Profit Margin (Q2 2027 vs Q2 2026): 3.4% vs. 2.3% (improved profitability on recent earnings)
Ask Charlie what makes Nippon Light Metal look cheap despite forecasts.
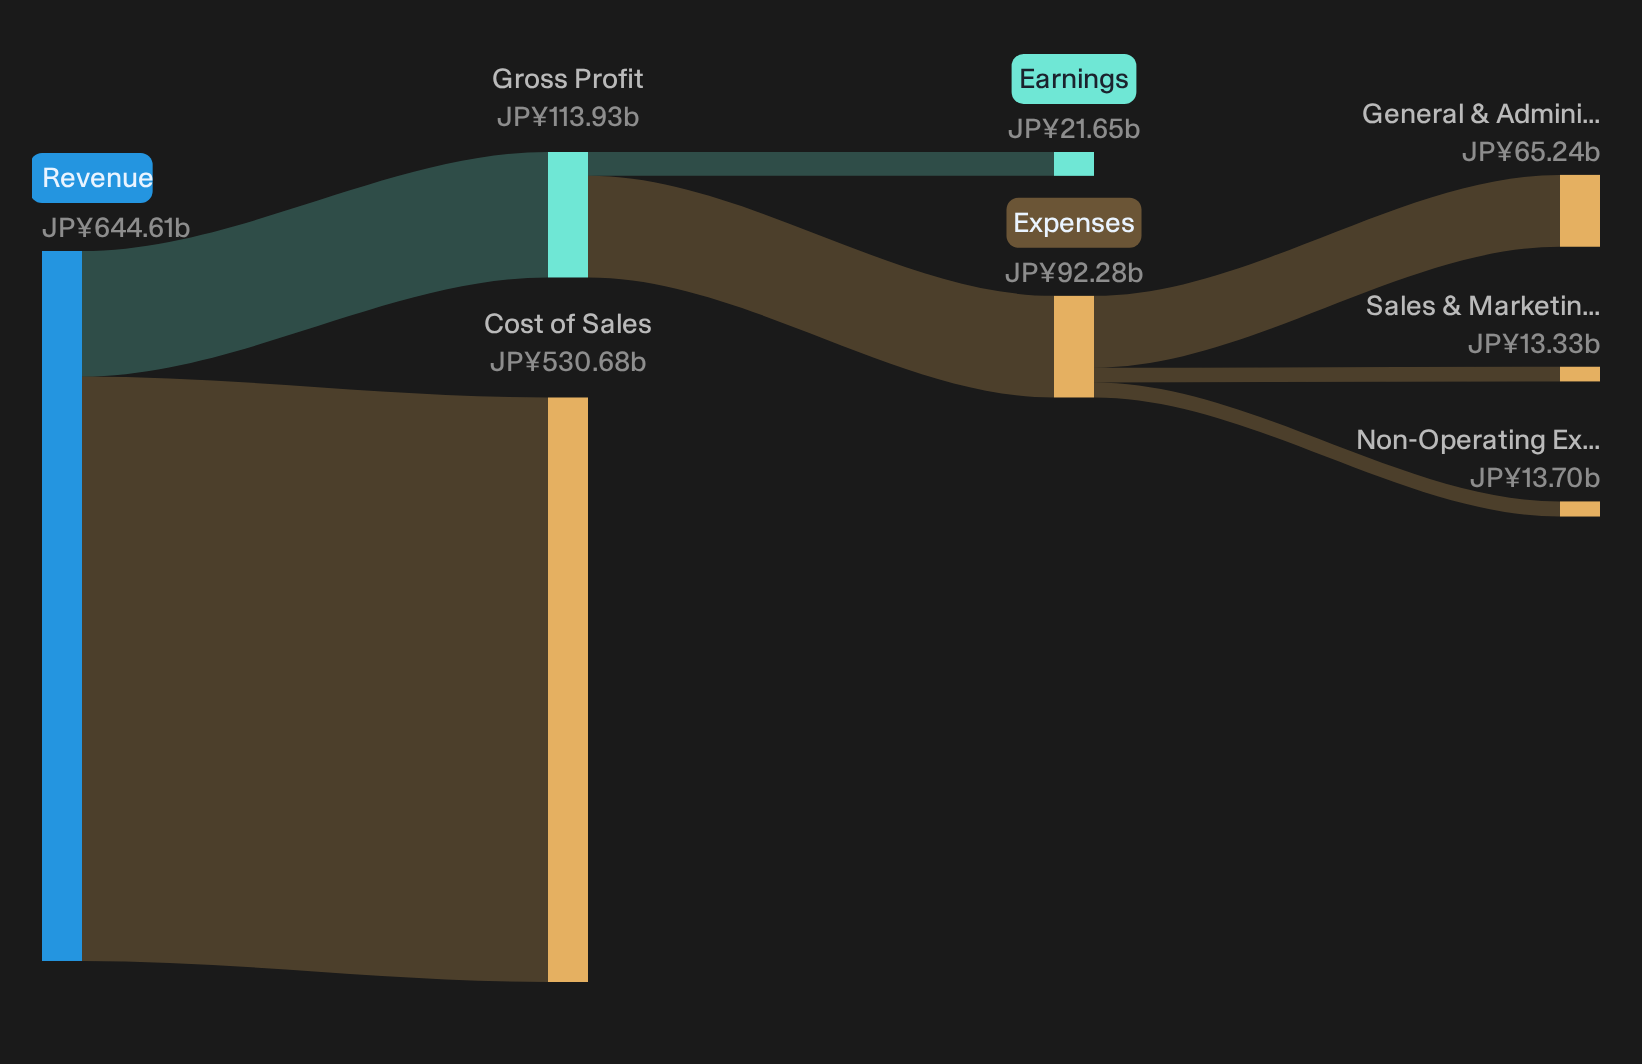
Stronger Earnings Temper Cautious Nippon Light Metal View
Nippon Light Metal Holdings just printed a set of numbers that give the constructive story more weight. Revenue in Q2 2027 was higher than in Q2 2026 and net income and basic EPS also moved up, which points to better monetisation of its diversified aluminum platform. Profit margin over the past 12 months improved compared with the prior year. Management also approved a share buyback of up to 600,000 shares, which signals balance sheet capacity to return capital while the business absorbs a choppy macro backdrop.
Cloudier Outlook Still Matters For Nippon Light Metal
Even with these stronger results, the more cautious framing around Nippon Light Metal Holdings remains in place. Forecasts that indicate softer revenue and profit ahead sit awkwardly against the latest improvement in earnings quality. Recent share price performance, with the stock down over the past 7, 30 and 90 days, suggests investors are still pricing in cyclicality and macro sensitivity. The buyback helps, but it does not erase concerns that earnings power could be pressured if demand across autos, construction or packaging turns weaker.
After a softer revenue outlook, debt not well covered by operating cash flows and a dividend uncovered by free cash can hint at deeper structural weak spots. Review the full Nippon Light Metal Holdings Company risk scorecard and expose any other issues flagged in our risk analysis for Nippon Light Metal Holdings Company which shows 3 important warning signsHunt Balance Sheets Before Consensus
Nippon Light Metal Holdings Company just reported stronger earnings while its share price and outlook stayed cautious. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 40% below our estimate - uses AI hiring and local services matching tools to turn job and consumer activity into higher value transactions.
- Company 2 - 48% below our estimate - pushes an AI-first security platform that ties bundled protection and monitoring into recurring software and services contracts.
- Company 3 - 17% below our estimate - adds maintenance-focused sales staff so elevator contracts deepen recurring service revenue in dense local clusters.
Those are three of them. See all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com