


Fresh quarterly numbers put Himax Technologies (NasdaqGS:HIMX) back in focus for investors. Revenue grew 5.9% year over year, earnings per share climbed 20.2%, and the business reported US$257.8 million in net cash.
Himax Technologies has seen its 1-month share price return fall 29.8%, and the 7-day performance is also lower, even though the stock is still up 25.4% on a year to date share price basis and has delivered a 3-year total shareholder return of about 1.1x. Recent trading suggests investors are reassessing how sustainable the latest earnings and revenue trends are, which affects perceived risk around the current US$10.70 share price.
Scan beyond Himax Technologies and compare its recent swing in sentiment with a curated group of resilient stocks in the 30 resilient stocks with low risk scores.
The question now is whether Himax Technologies’ sharp pullback is simply sentiment snapping back after a strong run, or a signal that the recent earnings and cash profile no longer justify the current valuation.
Most Popular Narrative: 65% Undervalued
Against the latest close at $10.70, the most followed narrative places Himax Technologies’ fair value at $30.20. This frames the recent pullback as a move that, according to that thesis, still leaves a wide valuation gap.
Rising contribution from non driver, AI and optical products, which reached 20.2% of Q2 2026 revenue and are targeted to approach 30% of sales in 2027, gives Himax Technologies more exposure to higher margin categories and can gradually shift the earnings mix away from traditional driver ICs.
See why 60 investors see Himax Technologies as 65% undervalued.
Result: Fair Value of $30.20 (UNDERVALUED)
Still, the bullish Himax Technologies story depends on analyst forecasts holding up, and any reset to the 29.3% revenue growth assumption or 18.1% profit margin target could quickly flip sentiment.
Find out about the key risks to this Himax Technologies narrative.
Another View: What Multiples Say About Himax Technologies
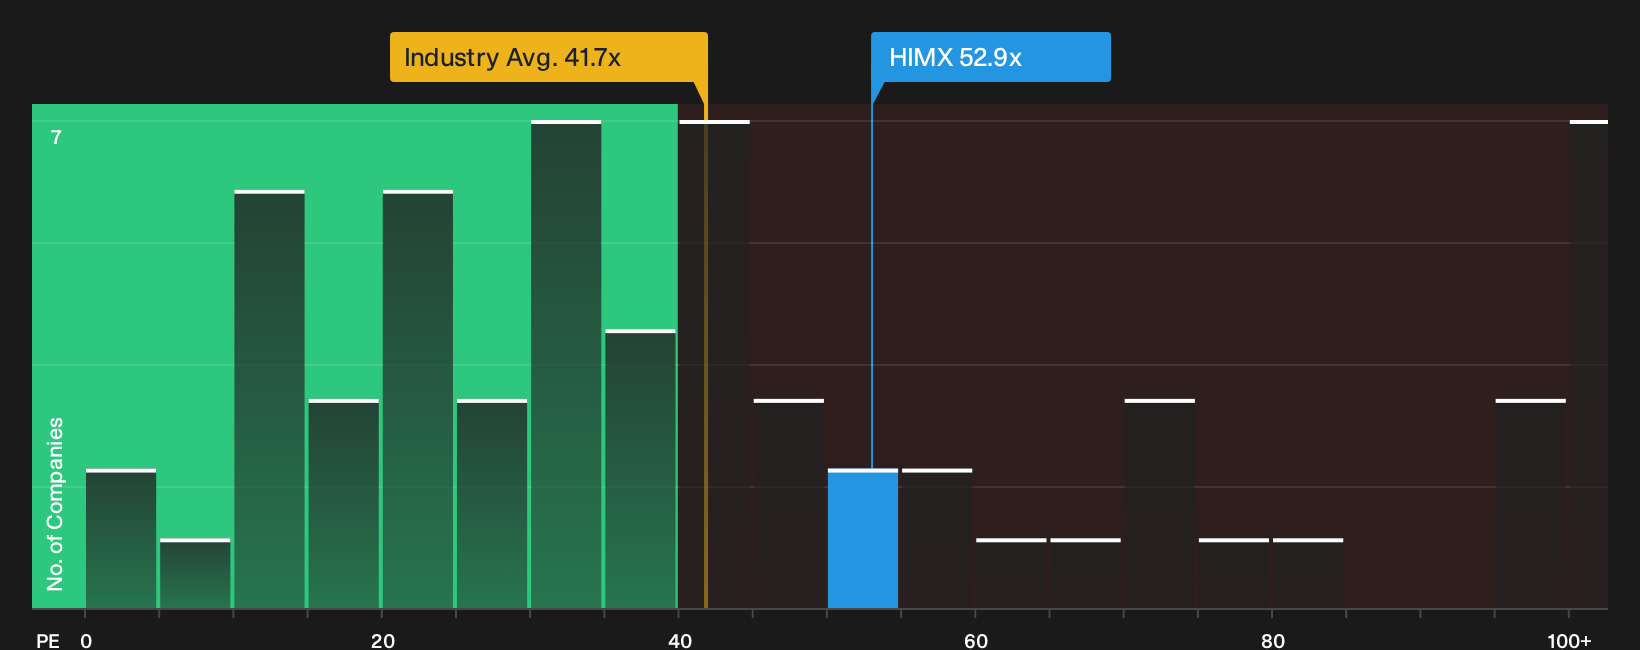
The fair value narrative pins Himax Technologies at $30.20, yet the market is currently valuing the stock at a rich 52.9x P/E. That is higher than both the US Semiconductor industry on 41.7x and a peer average of 47.1x, even though the fair ratio sits slightly higher at 58.5x.
In practice, that means investors are already paying a premium for the earnings stream today. The fair ratio points to a level the multiple could migrate toward over time, either by earnings catching up or the share price adjusting. The key question is whether you are comfortable owning a stock where much of the future optimism is already embedded in the current P/E, or whether that leaves too little room for error.
To pressure test whether this richer P/E still makes sense for you, it is worth going deeper into how the current price lines up with our valuation breakdown, including earnings quality and future expectations, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Himax Technologies is split, so do not wait for consensus to harden before you check the data yourself and stress test the story. Weigh both the 1 key reward and 2 important warning signs.
Looking for more Himax Technologies sized opportunities?
If you only focus on Himax Technologies, you risk missing out on other clear ideas across the market, so put a few more contenders on your radar today.
- Target stronger quality at a fair price by scanning companies highlighted in the 34 high quality undervalued stocks.
- Build a portfolio with staying power by filtering for businesses in the list of solid balance sheet and fundamentals (24 results).
- Hunt for early opportunities with room to grow by reviewing the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com