


PrairieSky Royalty (TSX:PSK) just released a detailed third quarter update, reporting higher revenue and profit figures along with modestly higher production volumes and a confirmed fourth quarter 2026 dividend of $0.265 per share.
Against this earnings backdrop, PrairieSky Royalty’s share price has climbed to CA$36.28, with a 30 day share price return of 9.24% and a year to date gain of 34.07%. The 1 year total shareholder return of 51.06% signals strong momentum supported by rising distributions and solid reported financials.
Compare how PrairieSky Royalty measures up against other income focused opportunities by reviewing our hand picked list of 3 dividend fortresses in today's market.
After PrairieSky Royalty’s sharp move and richer dividend stream, the real tension is simple. Does it make sense to step in at CA$36.28 now, or wait for a more forgiving price before committing fresh capital?
Price-to-Earnings of 30.1x: Is it justified?
PrairieSky Royalty trades on a P/E of 30.1x, which is a rich tag at CA$36.28 when lined up against both its industry and peer group.
The P/E ratio compares the current share price with earnings per share. For an energy royalty business like PrairieSky Royalty, it reflects what investors are willing to pay today for each dollar of reported profit as they weigh factors such as earnings stability, commodity exposure, and capital intensity.
With a 30.1x P/E, compared with 21.2x for the broader Canadian oil and gas sector and 17.4x for its peer set, the market is assigning PrairieSky Royalty a clear premium. That indicates that investors are already factoring in relatively strong profitability and cash flow resilience compared with more asset-heavy producers.
Result: Preferred multiple of Price-to-Earnings of 30.1x (OVERVALUED)
See what the numbers say about this price — find out in our valuation breakdown.
Still, the story around PrairieSky Royalty can shift quickly if commodity prices soften or if regulators change how royalties on Canadian production are treated.
Find out about the key risks to this PrairieSky Royalty narrative.
Another view on PrairieSky Royalty’s value
The rich 30.1x P/E suggests PrairieSky Royalty is priced for quality, yet the SWS DCF model points in a different direction. At CA$36.28, the shares sit below an estimated future cash flow value of CA$48.26, which frames today’s level as discounted rather than stretched. Which signal matters more to you: earnings or cash generation?
Look into how the SWS DCF model arrives at its fair value.
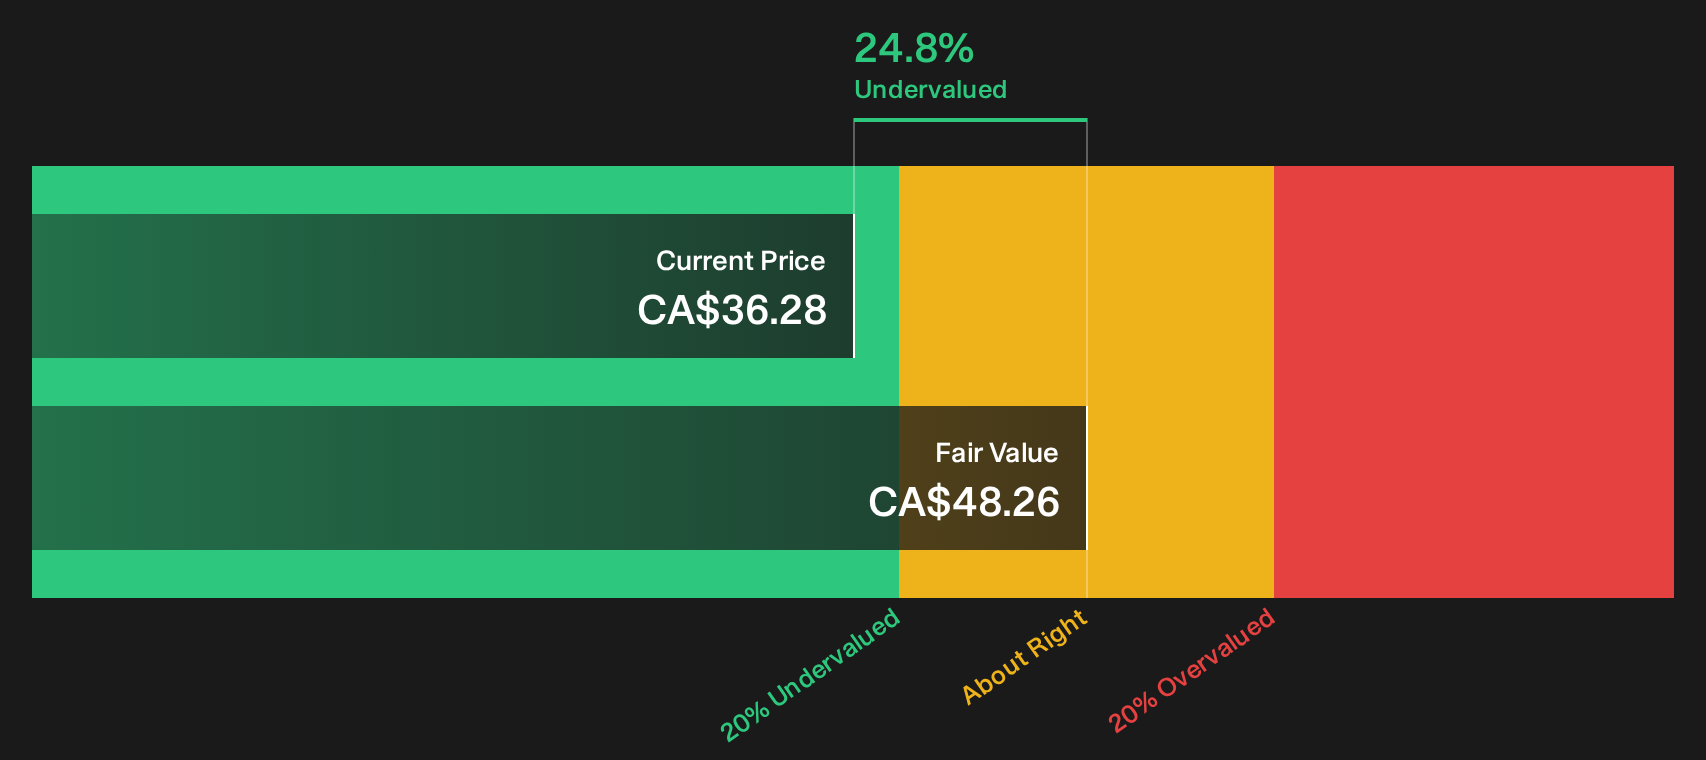
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PrairieSky Royalty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of rich multiples and DCF support around PrairieSky Royalty leaves you undecided, act while the data is fresh and test the numbers yourself. To see why some investors remain optimistic, review the 3 key rewards.
Hunting for more ideas beyond PrairieSky Royalty?
Do not stop at PrairieSky Royalty alone. Broaden your watchlist with other focused ideas that could complement or contrast what you see in this stock today.
- Target resilient balance sheets and steady fundamentals by reviewing our list of solid balance sheet and fundamentals (6 results) tailored for investors who care about financial strength first.
- Zero in on potential mispricings by scanning the 4 high quality undervalued stocks before capital chases them higher and the gap between price and fundamentals closes.
- Spot opportunities the market often overlooks by running through the 8 high quality undiscovered gems and seeing which stories others have not focused on yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com