


The Reserve Bank of Australia just lifted interest rates to 4.85%, the highest since 2008. This puts real pressure on borrowed money and traditional growth stories. Founder-led Australian companies can be different. Leaders with major skin in the game often stay disciplined on capital, costs and risk. This article walks through three founder-run stocks from our screener that show how that mindset can matter when money is no longer cheap.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is heavily aligned with long term performance. However, if you want the pick of this theme, these 7 top founder-led companies are the best of the best.
Flight Centre Travel Group (ASX:FLT)
Overview: Flight Centre Travel Group runs founder-led leisure and corporate travel brands that connect customers with airlines, hotels, cruises and other travel services worldwide.
Operations: Flight Centre Travel Group generates about A$1.43b from Leisure and A$1.18b from Corporate, with A$1.49b earned in Australia and New Zealand.
Market Cap: A$2.46b
Flight Centre Travel Group brings a founder controlled culture directly into its main leisure and corporate travel businesses. This matters when you want leaders whose own wealth is closely tied to how carefully each dollar of cost and commission is managed.
"Although Flight Centre Travel Group reports sizeable productivity gains in corporate travel consultant output, the shift of productive operations costs of about A$12 million into operating expenses in FY27 is set to raise the reported cost base and can limit how much of any future TTV uplift actually reaches EBIT and net margins."
The key question is what happens if that quiet shift in where costs sit on the income statement bites harder into margins than founder discipline can offset.
If that margin pressure is the real story, the full narrative for Flight Centre Travel Group shows how founder discipline could still reshape Flight Centre Travel Group’s earnings mix and capital decisions.

Harvey Norman Holdings (ASX:HVN)
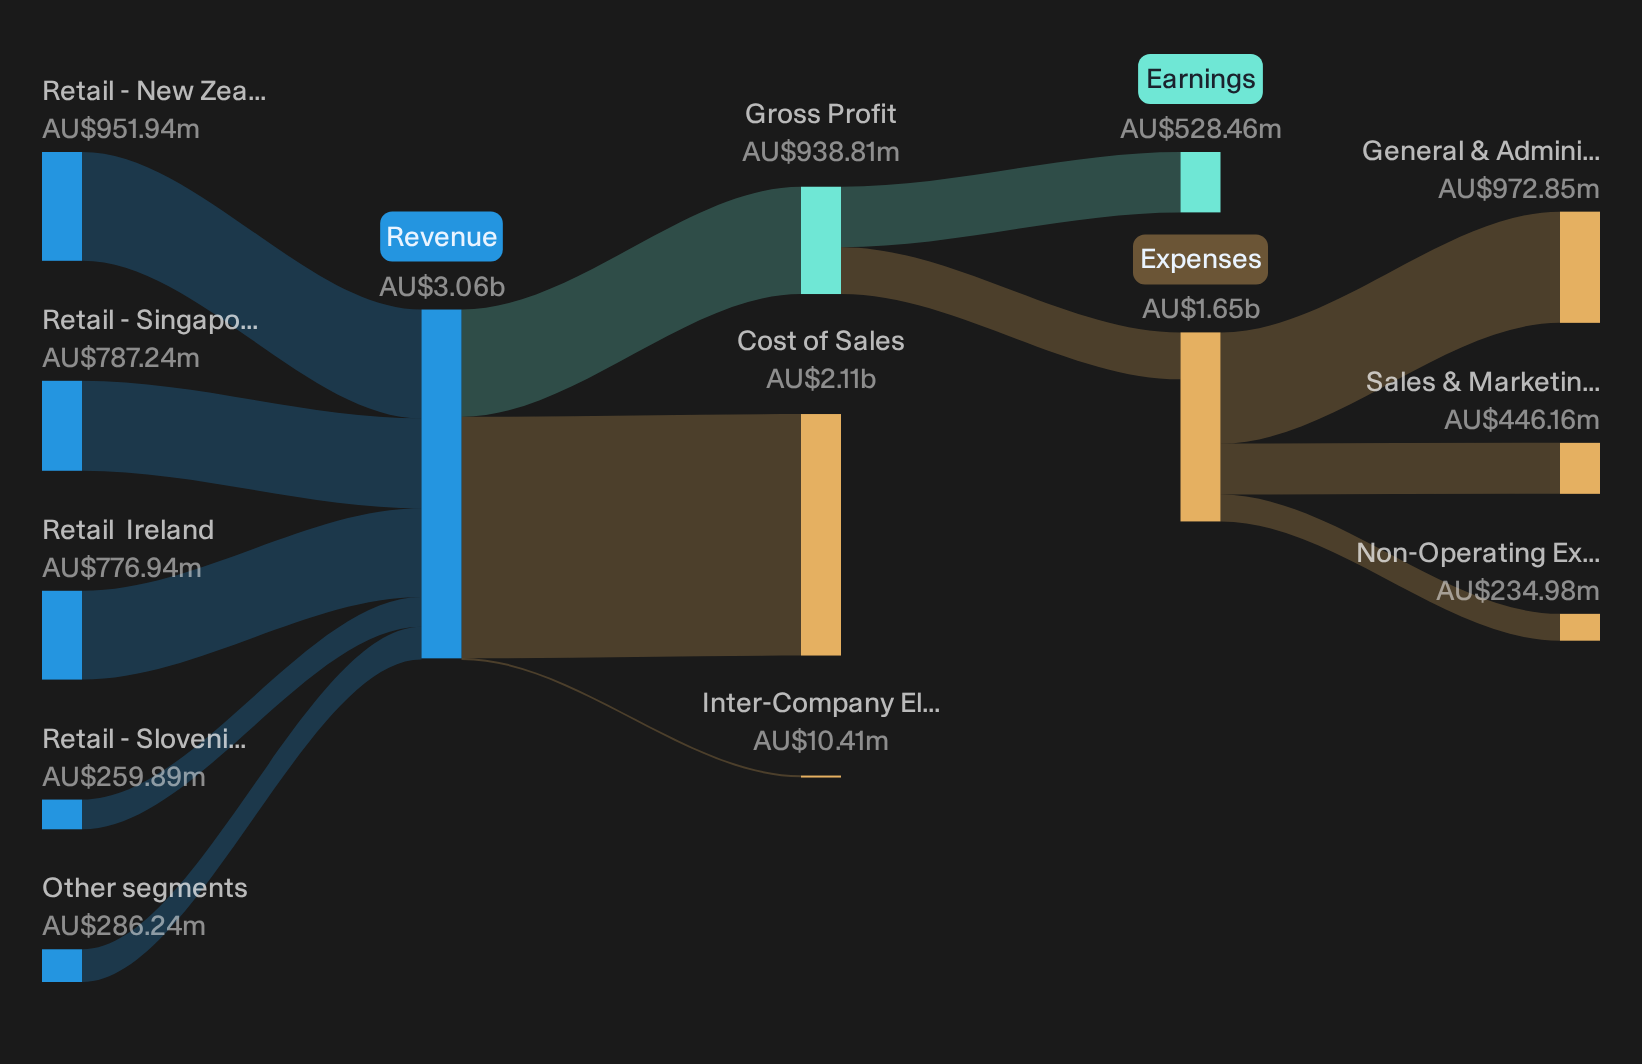
Overview: Harvey Norman Holdings runs founder-influenced retail and franchise chains like Harvey Norman, Domayne and Joyce Mayne, selling household goods alongside property and digital system operations.
Operations: Harvey Norman Holdings earns most of its A$3.05b retail revenue from New Zealand, Ireland, Singapore and Malaysia, with smaller contributions from Slovenia, Croatia, the UK and non-franchised outlets.
Market Cap: A$5.45b
Harvey Norman matters for a founder-led screen because Gerry Harvey still shapes how the retail and franchise network is run. He turns long experience and a large ownership stake into very direct influence over store economics and expansion choices.
"That blue-chip character was challenged in 2025, when Harvey Norman reported net profit growth of 47% year-on-year."
What comes next for Harvey Norman’s founder-guided story hinges on how one quiet shift in its earnings mix plays out.
If that shift is the real hinge, the full narrative for Harvey Norman Holdings reveals how Harvey Norman could see that 47% profit surge masking deeper risks and fresh upside.
GenusPlus Group (ASX:GNP)
Overview: GenusPlus Group builds and maintains power, rail, telecoms and industrial infrastructure across Australia, including high voltage grid and renewable energy projects.
Operations: GenusPlus Group generates about A$837 million from Infrastructure, A$369 million from Energy and Engineering and A$152 million from Services, all in Australia.
Market Cap: A$1.65b
GenusPlus Group matters for a founder led theme because long tenure on complex grid and renewable projects can reward careful execution far more than short term contract wins.
"Although GenusPlus Group points to multi year opportunities in renewables and storage, the move to scale up battery, solar and substation work requires more complex engineering and project management, and the current comment that Energy & Engineering margins are a little bit low suggests execution pressures could restrain segment EBITDA if these projects prove harder to deliver profitably."
What happens if a single pressure inside that growing project pipeline quietly shifts the balance between impressive revenue and the quality of each dollar earned?
That inflection point is exactly where the full narrative for GenusPlus Group explains how GenusPlus Group could turn tougher projects into accelerating, higher quality earnings instead of stalled headline revenue.

Seeking Alternatives Before The Crowd
Fresh ideas tend to move first. By the time momentum headlines appear, many potential entry points may already be out of reach. Scan these under the radar lists now to evaluate opportunities earlier in the cycle.
- Identify potential early breakouts among smaller names backed by solid numbers using the curated 16 elite penny stocks with strong financials before momentum traders react and pricing power shifts.
- Follow structural shifts in global energy as utilities and suppliers adapt by using the focused 16 nuclear energy infrastructure stocks while these infrastructure plays remain relatively under the radar.
- Monitor the wiring behind AI, data and electrification trends by scanning the hand picked 42 power grid technology and infrastructure stocks before grid modernisation stories become more widely highlighted.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com