


- BlackLine partnered with S3NS to offer its Agentic Financial Operations Platform on PREMI3NS trusted cloud infrastructure in France, with Thales as the first customer and Thales’ digital services division running the local deployment.
- The move gives BlackLine a way to serve European enterprises with strict data residency and sovereignty needs while keeping its AI driven finance tools aligned with security, governance and ISO/IEC 42001:2023 AI management controls.
- We will now look at how BlackLine's trusted French cloud deployment with S3NS could reshape the broader investment narrative.
Scan other AI driven finance platforms pressing into regulated markets by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) along with BlackLine's latest trusted cloud move.
BlackLine Investment Narrative Recap
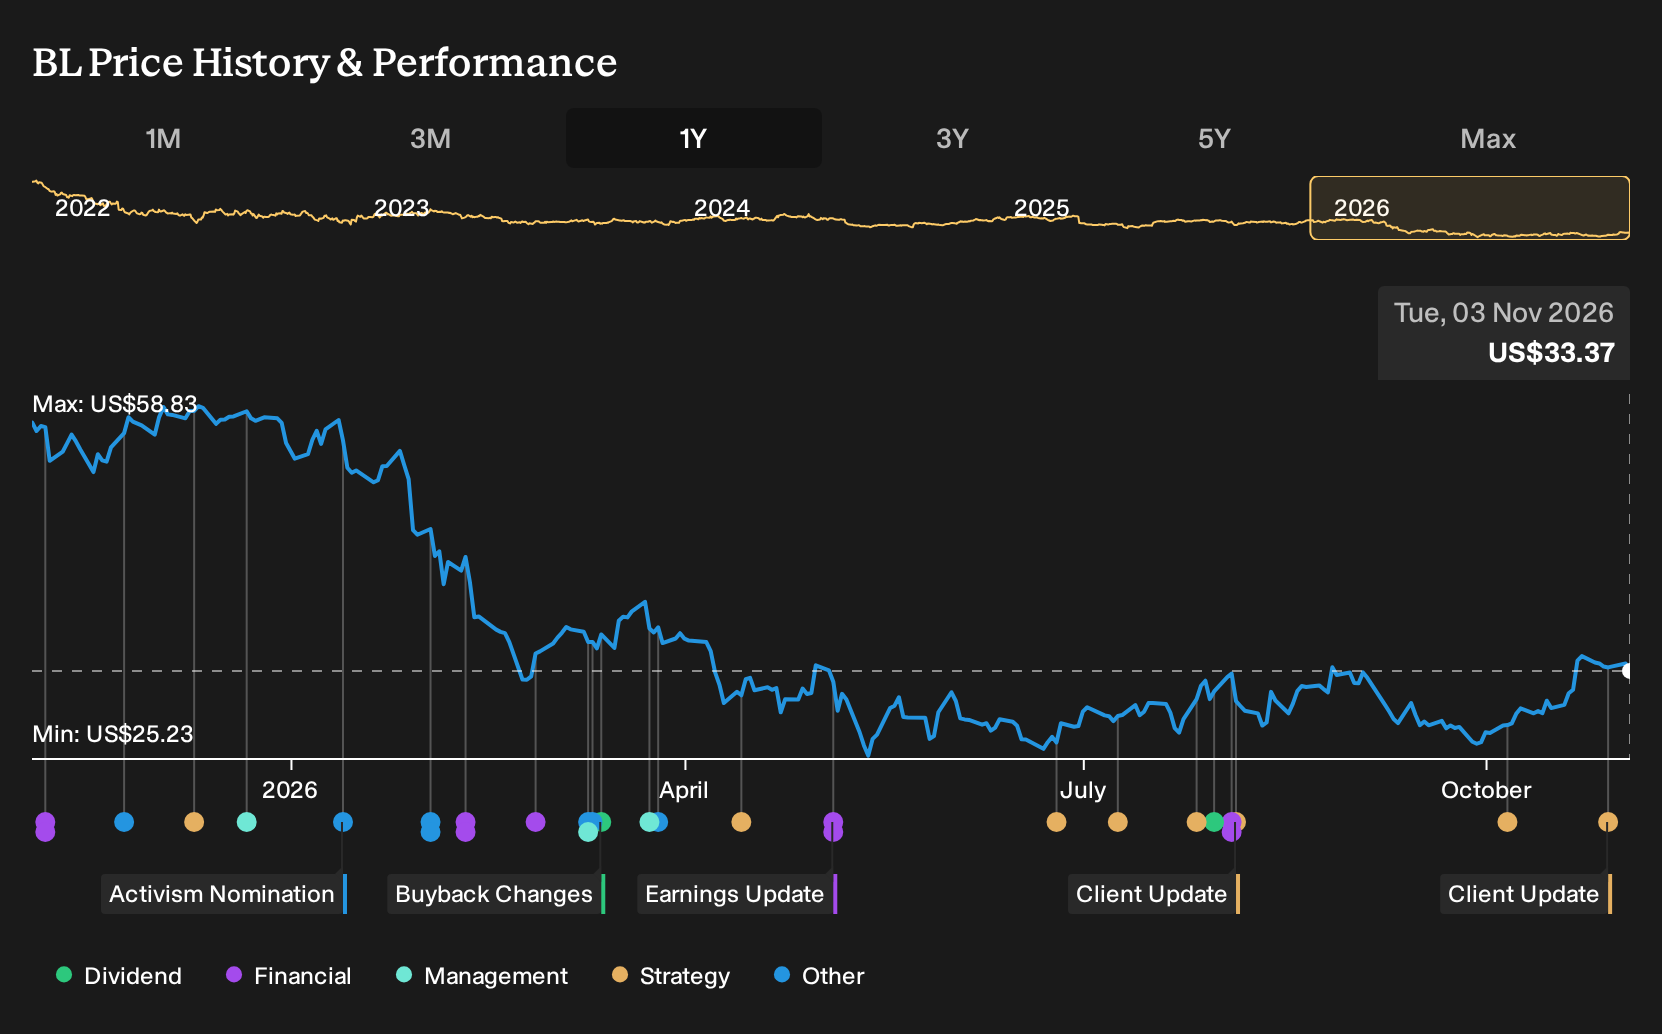
To own BlackLine, you need to believe its shift toward larger, complex enterprises and agentic AI platforms like Studio360 can offset customer losses in the smaller cohort, softer net revenue retention around 102.4% and margin pressure, with current profit margins at 4.7% versus 13.1% last year. The key near term swing factor is whether extended sales cycles and AI risk reviews continue to push out large deal timing.
The French trusted cloud launch with S3NS looks directionally helpful but does not alter that core tension. It supports the long run AI and enterprise thesis, but the biggest current risk still sits in delayed enterprise decisions and churn in the lower mid market, which can weigh on ARR growth and limit operating leverage.
The new S3NS partnership in France most directly connects to BlackLine’s push to be a control and governance layer for AI driven finance through Studio360, Verity agents and the Finance Control Console. Extending that stack into a trusted, sovereignty focused environment gives regulated enterprises another way to adopt AI workflows while aligning with strict governance and ISO/IEC 42001:2023 expectations.
That fits alongside the broader effort to win more mega enterprise accounts, including prior wins with Vodafone and two of the top six U.S. banks and sovereign cloud and FedRAMP projects. Execution across these regulated and partner heavy channels will likely influence how quickly remaining performance obligations above US$1.1b translate into reported revenue and whether net revenue retention can recover from recent pressure.
BlackLine's narrative projects US$1.0b revenue and US$168.4 million earnings by 2029. This assumes 11.9% yearly revenue growth and about a 4.8x earnings increase from US$34.8 million today.
Uncover why BlackLine's fair value indicates a 14% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One bullish twist on BlackLine argues that country bound deployments like the French S3NS cloud could unlock faster adoption in regulated sectors, which those analysts already model with revenue reaching about US$1.0b and earnings near US$216.6 million by 2029. You can treat that as one possible path and compare it with more cautious views that existed before this news and may now evolve.
Explore another BlackLine fair value estimate, including one that suggests potential upside of as much as 285% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your BlackLine research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BlackLine. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BlackLine's overall financial health at a glance.
Looking for more investment ideas beyond BlackLine?
If you want to pressure test your thesis on BlackLine against other opportunities, use the Simply Wall St Screener to scan for companies that fit different risk and return profiles, then compare them side by side.
- For investors focused on stability first, review a 30 resilient stocks with low risk scores that may offer a calmer ride when markets turn volatile.
- If value and quality matter most to you, assess a 34 high quality undervalued stocks that combines stronger fundamentals with potentially mispriced shares.
- For those hunting for less crowded opportunities, check a 19 high quality undiscovered gems that could sit off the usual large cap radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com