


- Astera Labs reported record Q3 2026 revenue of US$584.9 million, up 49% sequentially and very large year over year, driven by high volume Scorpio X-Series fabric switch shipments and contributions from new Aries, Orion and Leo product launches. The company also issued guidance for Q4 revenue of US$730 million to US$750 million with a GAAP gross margin near 72%.
- The results underline how Astera Labs is increasing its dollar content in AI data center builds, as Scorpio X-Series ramps and the broader connectivity portfolio deepens ties with hyperscalers and AI platform partners that had already been central to the consensus long-term thesis.
- Next, the focus turns to how this stronger Scorpio X-Series driven outlook could reshape Astera Labs' investment narrative over the medium term.
Scan beyond Astera Labs and explore other AI infrastructure companies that may be influenced by similar data center demand using our curated 53 AI infrastructure stocks
Astera Labs Investment Narrative Recap
Owning Astera Labs means believing high AI data center spending persists and that this company keeps winning sockets across interconnect, memory and fabric switch roles. The Q3 beat and Q4 guidance support that view in the near term, since Scorpio X-Series and the broader portfolio are now meaningful revenue drivers. The key short term catalyst is continued Scorpio ramp with stable roughly 72% GAAP gross margin.
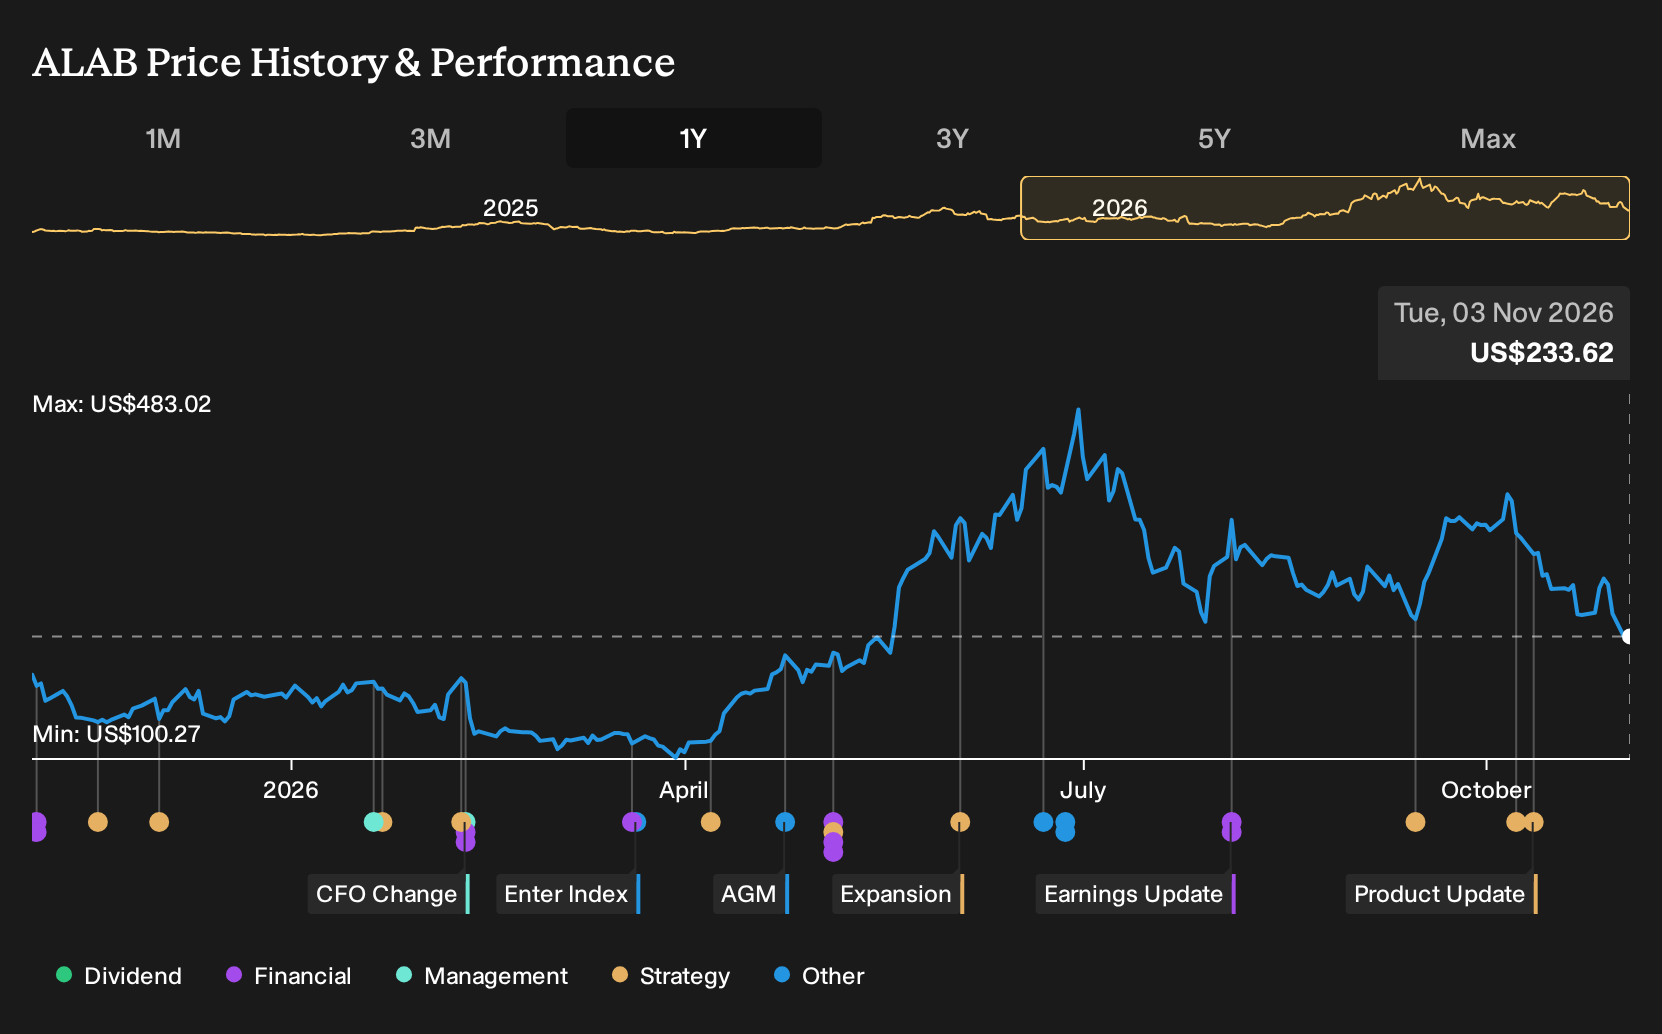
The biggest near term risk sits around hyperscaler spending behavior and competitive responses from larger chipmakers that could affect pricing or design wins. Recent share price volatility and strong expectations embedded in the current P/E also raise the bar for any future quarterly update.
The most relevant fresh datapoint is Scorpio X-Series moving into high volume production and driving record Q3 revenue of US$584.9 million, with Q4 guidance of US$730 million to US$750 million. This shift elevates fabric switches from a promising line item to a central contributor, which matters because it increases Astera Labs’ dollar content per AI rack.
For investors, that Scorpio trajectory ties directly into both upside and risk. Strong execution could support the forecasted revenue growth profile and help offset customer concentration. Any slowdown in orders or aggressive competition in interconnect and switching would hit this product family first, so Scorpio performance becomes a key gauge of operational health.
Astera Labs Long Term Forecasts In Focus
Astera Labs' long term story in the analyst models centers on aggressive expansion in AI oriented connectivity while holding profitability at current levels. Consensus assumes revenue rises at 47.2% a year over the next three years, with profit margins steady at 30.7% as the product mix leans further into Scorpio, Aries, Orion and Leo shipments.
On earnings, the latest forecast points to US$1.2b in profit by 2029 compared with US$369.5m today. That is a little over 3x higher on an absolute basis and sits inside a wide range of outcomes, from US$735.7m on the low end to US$1.7b at the top. Under that central case, the market would be valuing those 2029 earnings at a P/E of 84.1x, down from 121.8x on the current figures and still above the 42.6x multiple cited for the broader US semiconductor peer group.
Astera Labs' narrative projects US$3.8b revenue and US$1.2b earnings by 2029. This assumes 47.2% yearly revenue growth and an earnings increase of roughly US$830m from US$369.5m today.
Share count also features in the setup. Analysts are building in 2.71% yearly expansion in shares outstanding over the next three years, which affects per share outcomes even if total profit tracks the headline target. The discount rate applied in the Simply Wall St report is 11.21%, which sets the hurdle for turning those distant cash flows into a present value that investors can compare with the current price.
Valuation work around Astera Labs then stitches all of these inputs together. The consensus price target sits at US$382.68, against a current share price of US$259.51 and a spread of views that runs from US$190.00 on the cautious side to US$500.00 on the optimistic end. For the target to line up with the models, the reader would need to be comfortable with that US$3.8b revenue and US$1.2b earnings profile in 2029 and a P/E multiple of 84.1x on those profits using an 11.2% discount rate.
The gap between the present quote and the target works out to 32.2%. Rather than treat that figure as a conclusion, it helps to view it as an output of the underlying assumptions on AI data center demand, Scorpio adoption, margin durability and share issuance. The key task for any investor is to pressure test where personal expectations differ most from that framework.
Uncover why Astera Labs' fair value indicates a 64% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Astera Labs puts gross margin drift in the spotlight. Bullish analysts were already baking in revenue of about US$6.1b and earnings of US$1.7b by 2029, yet still expected non GAAP margins to ease toward 70%. With Scorpio X now surprising on scale, that optimistic story could shift again. Treat this as one of several competing narratives to explore.
Explore 6 other Astera Labs fair value estimates, including one that suggests potential upside of up to 169% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Astera Labs research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Astera Labs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astera Labs' overall financial health at a glance.
Looking For More Investment Ideas Beyond Astera Labs?
If the Astera Labs story has sharpened your appetite for AI and high growth opportunities, you can widen the lens and test your thesis against a broader set of companies. Using the Simply Wall St Screener, you can quickly filter for different risk, quality and income profiles that line up with your own goals.
- If capital preservation is high on your list, you can start with companies that score well on resilience by checking out 30 resilient stocks with low risk scores.
- For readers who care most about financial strength, you can look for robust balance sheets and consistent fundamentals through the list of solid balance sheet and fundamentals (24 results).
- If you want ideas that the market may not be fully focused on yet, you can sift through potential under the radar opportunities using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com