


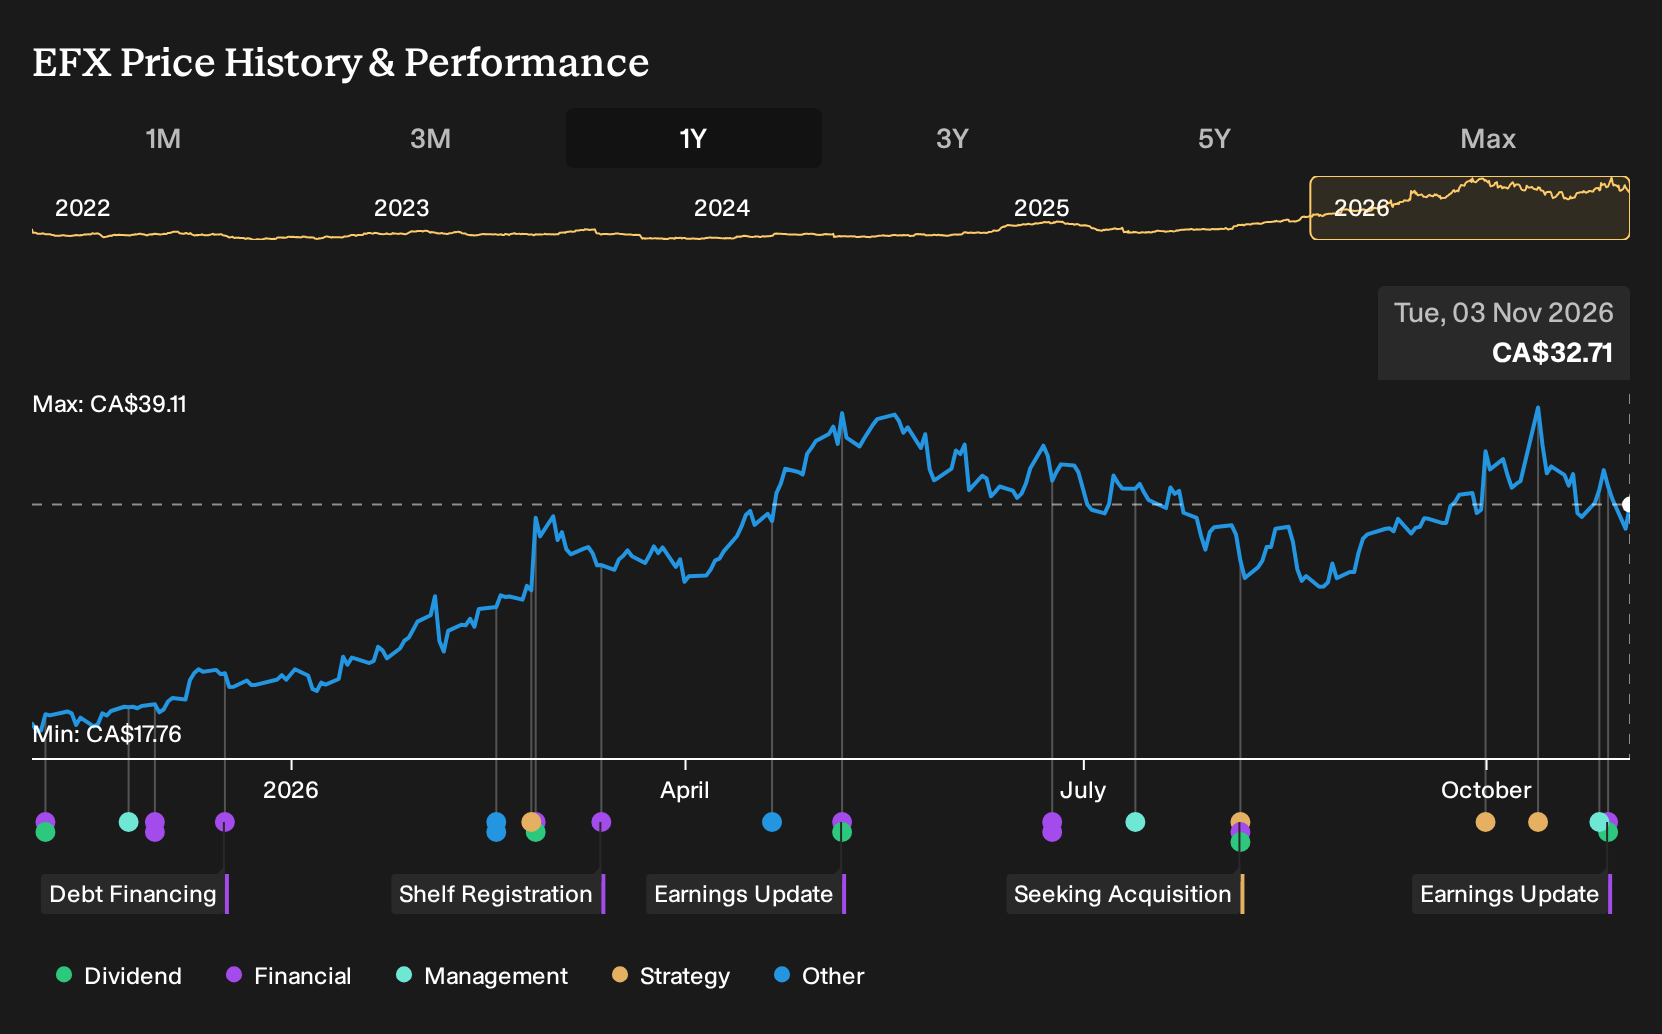
- Enerflex reported third quarter 2026 sales of US$623 million and net income of US$55 million, with basic earnings per share from continuing operations of US$0.45, and paired the results with a 17% increase in its quarterly dividend to US$0.035 per share.
- The combination of lower revenue but higher earnings and a larger dividend points to Enerflex tightening costs while signalling confidence in its cash generation and balance sheet resilience.
- Next, the focus shifts to how Enerflex's improved profitability and higher dividend reshape the existing investment narrative around earnings quality.
Scan how Enerflex's tighter cost control and higher dividend compare with peers by focusing on companies flagged in our list of solid balance sheet and fundamentals (6 results).
Enerflex Investment Narrative Recap
To own Enerflex, you need to be comfortable with a business still heavily tied to natural gas infrastructure, yet working to squeeze more earnings out of existing projects and services. The latest quarter showed lower sales but higher profit, which reinforces a near term catalyst around cost discipline and contract quality rather than sheer volume.
The biggest operational risk remains exposure to traditional gas compression and processing in a cyclical industry where margins can reset quickly. Recent results help at the margin by showing Enerflex can protect earnings, but they do not remove concerns about margin normalization or the need to deepen lower carbon offerings over time.
The dividend increase to US$0.035 per share sits at the center of this earnings story. Management paired stronger net income and higher EPS with a larger payout, which directs attention back to a key catalyst investors already watch: the ability of Enerflex to turn its backlog and service work into consistent free cash generation.
This higher dividend also sharpens the risk discussion. If energy transition policies pressure traditional gas projects or if compression utilization weakens, a richer payout competes with growth spending and balance sheet flexibility. For anyone tracking Enerflex, the question becomes whether future cash flows can comfortably support both expansion plans and this stepped up shareholder return.
Enerflex's narrative projects $3.8b revenue and $315.3 million earnings by 2029. This assumes 14.1% yearly revenue growth and requires about a sixfold increase in earnings from $53.0 million today.
Discover why Enerflex's fair value points to a 53% potential upside to its current price, a gap that could close quickly.
Exploring Other Perspectives
One alternate view on Enerflex leans hard into execution risk. The most cautious analysts were assuming only 8.0% annual revenue growth and earnings of about US$216.5 million by 2029. That is far below the consensus path. These forecasts were set before this earnings beat and dividend lift, so opinions may evolve from here.
Explore 3 other Enerflex fair value estimates, including one that suggests it could be worth just CA$45.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Enerflex research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enerflex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enerflex's overall financial health at a glance.
Looking for more Enerflex investment ideas?
If you want to stress test your view on Enerflex, it helps to see how other companies with different balance sheets, income profiles, and dividend habits line up beside it. Use the Simply Wall St Screener to widen your watchlist and pressure test your thesis in a structured way.
- For investors who like to back smaller companies with room to mature, check out 17 elite penny stocks with strong financials that combine modest share prices with measurable business fundamentals.
- If your focus is skewed toward value and quality, scan the 4 high quality undervalued stocks that pair stronger balance sheets with cash flows the market may be underpricing.
- Income focused readers can compare Enerflex's payout profile against 3 dividend fortresses that offer yields above 5% while still aiming to preserve resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com