


AltaGas (TSX:ALA) drew fresh attention on October 29, 2026, after reporting third quarter results that paired higher sales with another quarterly net loss, while its board reaffirmed cash dividends on both common and preferred shares.
AltaGas shares changed hands at about CA$55.45 after the earnings release, with a 30 day share price return of 4.01% and a 90 day gain of 4.68%, suggesting steady upward momentum. A year to date share price return of 31.46%, alongside a 1 year total shareholder return of 41.46% and 5 year total shareholder return of 163.64%, points to a stock that has already rewarded patient holders, even as the latest quarter keeps attention on earnings quality and dividend support.
Compare AltaGas with a curated group of peers that combine income potential with balance sheet strength by scanning the list of solid balance sheet and fundamentals (6 results) before you decide where fresh capital goes.
AltaGas now trades near its recent highs after a strong multi year run, even as the latest quarter showed another net loss. Investors may wish to consider whether to commit fresh money at the current level or wait for a more favorable price.
Most Popular Narrative: 8% Undervalued
AltaGas trades at CA$55.45 against a widely followed fair value estimate of about CA$60.18. This frames the stock as modestly undervalued and puts the focus on whether its growth projects and balance sheet discipline can deliver the cash flows that narrative assumes.
A balanced utility and midstream model funded within a 4.5 to 5.0x net debt to EBITDA leverage band, with leverage reported at 4.7x by year end 2025 and 4.4x through the first half of 2026 and capacity to invest about US$5b over three years, allows AltaGas to keep directing capital toward projects that target 5 to 7% annual growth in EBITDA, EPS and dividends, which feeds into long term earnings power.
See why 32 investors see AltaGas as 8% undervalued.
Result: Fair Value of CA$60.18 (UNDERVALUED)
Still, the AltaGas story depends on smooth execution at Ridley Island and on regulators allowing enough recovery on that significant utility spending.
Find out about the key risks to this AltaGas narrative.
Another View: What AltaGas’ P/E Is Telling You
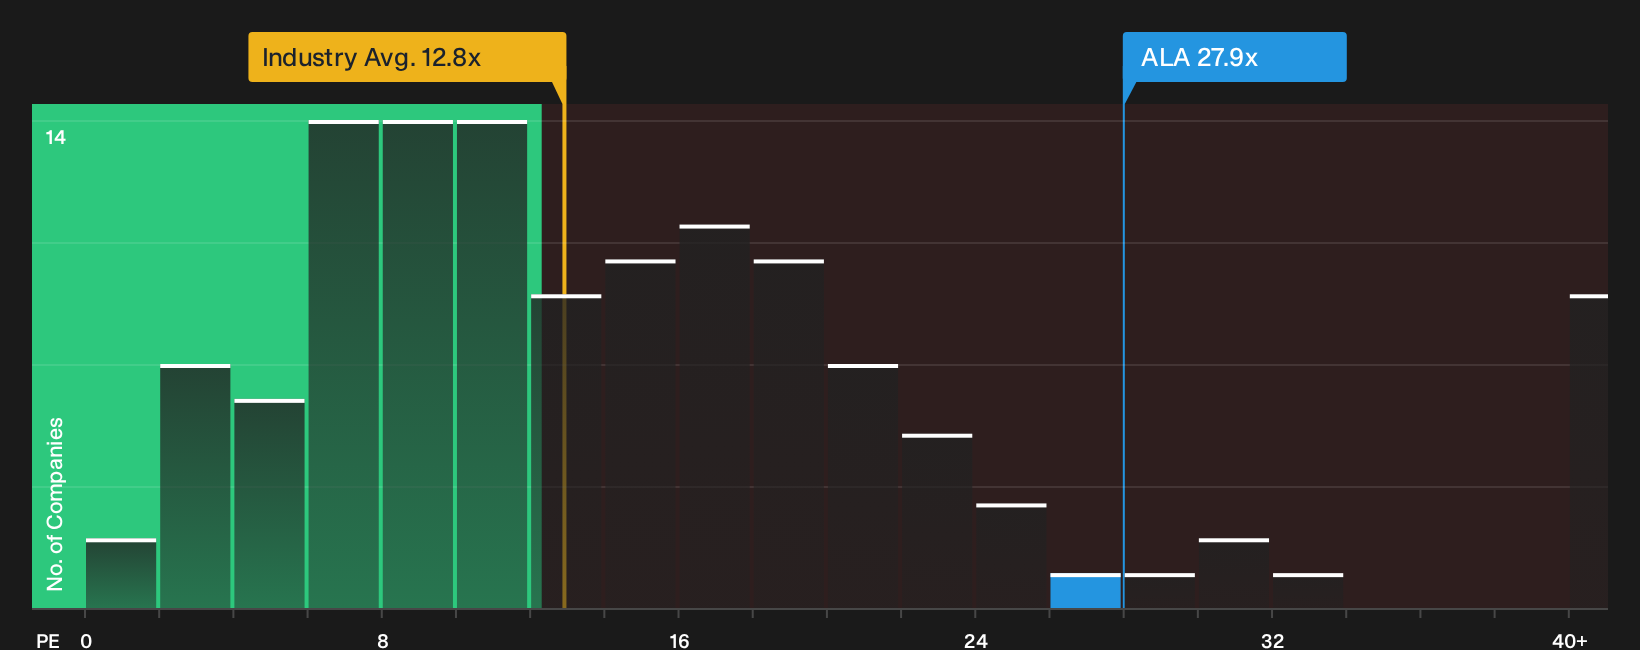
There is a very different message when AltaGas is viewed through its P/E ratio. The stock trades at about 27.9x earnings, more than double the Global Gas Utilities average of 12.8x and below its own fair ratio estimate of 36.1x. This points to both valuation risk and potential upside if sentiment shifts.
Compared with closer peers on 47.3x earnings, AltaGas sits at a discount. Investors are effectively paying less per dollar of earnings than for that group, even though the multiple is still rich versus the wider utility pack. The key question is whether you think future results will justify a higher future ratio or drag this one down.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals from AltaGas so far. If the blend of one or more risks and one or more rewards feels finely balanced, move quickly and pull up the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond AltaGas?
Do not stop with AltaGas alone. The same time you spend tracking one ticker could uncover several others that better match your income, risk and return goals.
- Target rock solid balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (6 results) so excess debt risk does not quietly chip away at your returns.
- Hunt for underappreciated opportunities by running the 8 high quality undiscovered gems before crowded trades absorb the best risk reward setups.
- Prioritise resilient, lower risk profiles by checking the 9 resilient stocks with low risk scores so a single setback in one holding does not dominate your overall portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com