


- Methanex reported third quarter 2026 sales of US$1,387.5 million and net income of US$264.98 million, and issued 2026 production guidance of 9.0 million tonnes of methanol and 0.3 million tonnes of ammonia, along with a new buyback plan for up to 5% of its shares.
- The combination of higher year to date earnings, increased methanol output versus the prior year period, and a share repurchase authorization indicates management’s focus on cash generation, portfolio capacity and capital returns at Methanex.
- We will now examine how Methanex's current profitability, supported by a recently announced buyback plan, may affect its broader investment narrative.
Scan for other potential value stories that mirror Methanex's production scale and cash return focus with our curated list of 4 high quality undervalued stocks.
Methanex Investment Narrative Recap
To stay invested in Methanex, you need to be comfortable with a pure commodity story. Earnings hinge on methanol pricing, gas availability and the firm’s ability to keep plants like Geismar and Chile running close to the production guidance of 9.0 million tonnes of methanol and 0.3 million tonnes of ammonia for 2026.
The key short term swing factor is operational reliability relative to contracted gas risk in Chile, Egypt and New Zealand. The biggest near term risk remains any gas disruption or integration issues with OCI that force curtailments, which could matter more to the thesis than the strong recent profit print.
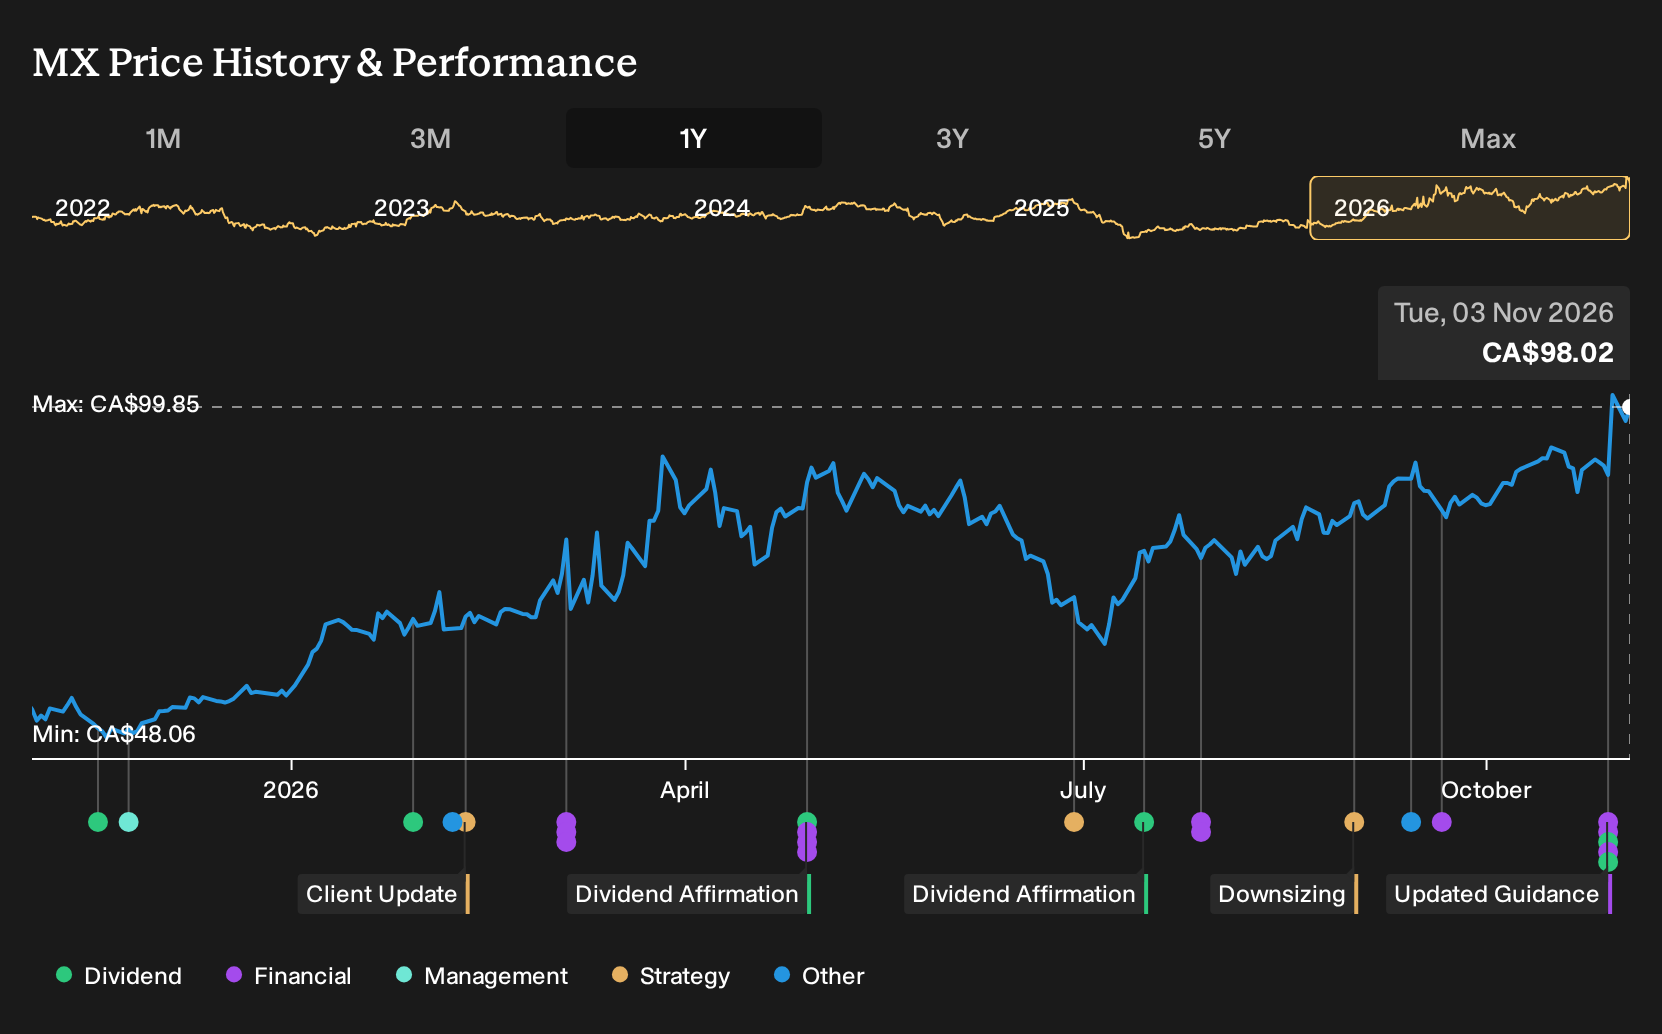
The new share repurchase plan to cancel up to 3,868,213 shares, or 5% of the float, is the announcement most directly connected to this story. It depends on Methanex generating enough free cash flow from its current production base and guidance to fund both buybacks and its balance sheet commitments.
For you as an investor, that plan ties catalysts and risks together. Strong execution on the 2026 production outlook, along with disciplined gas contracting and OCI integration, would support the buyback pace. Any setback on volumes, synergies or input costs could limit how much of that authorization is actually used.
Methanex's narrative projects revenues of US$4.1b and earnings of US$805.2 million by 2029. This assumes revenue growth of 3.9% per year and an earnings improvement of about US$850 million from current earnings of a US$45 million loss.
Uncover why Methanex's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The Simply Wall St Community currently contributes three fair value views on Methanex, stretching from about US$91 to almost US$155 per share. That spread shows how far private investors can disagree. As you weigh those opinions against fresh guidance, buyback plans and gas supply risks, it makes sense to test several alternative viewpoints yourself.
Explore 2 other Methanex fair value estimates, including one that suggests up to 7% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Methanex research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Methanex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Methanex's overall financial health at a glance.
Looking For More Ideas Beyond Methanex?
If you want to apply the same disciplined mindset used to assess Methanex to a wider watchlist, the Simply Wall St Screener can help you quickly narrow the field to businesses that better match your income goals, risk appetite or balance sheet preferences.
- For steadier cash flow potential, you could scan companies that combine higher yields with resilience by using our list of 3 dividend fortresses.
- If capital preservation sits higher on your priority list, you might focus on businesses that score well on risk metrics through a curated set of 9 resilient stocks with low risk scores.
- To widen your opportunity set beyond well known tickers, you can search for under the radar prospects that still show solid fundamentals through a collection of 8 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com