


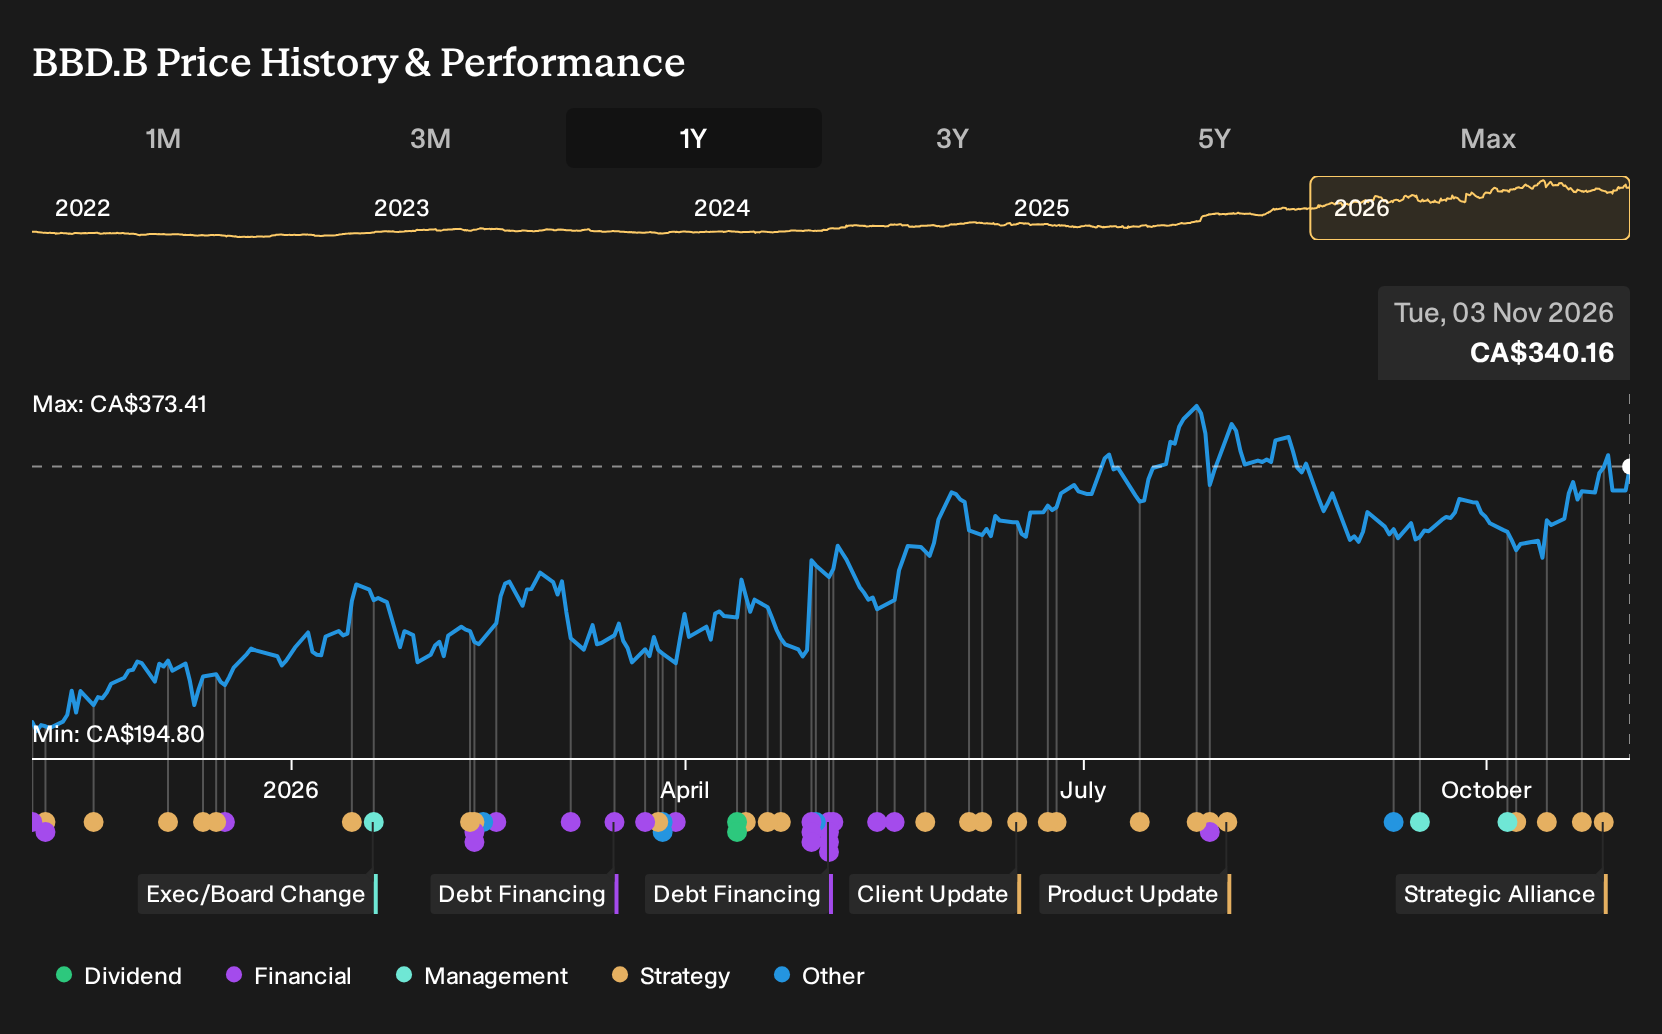
- Bombardier signed a Memorandum of Understanding with UK-based BAE Systems in October 2026 to explore collaboration on future combat air programs, covering research and development, systems integration, industrialization, workforce development and lifecycle support.
- The agreement positions Bombardier’s business jet and defence integration know-how as a potential building block for next-generation combat aircraft programs that align with government priorities and broader defence industrial base objectives.
- The focus now turns to how Bombardier's potential role in future combat air programs could influence its broader investment narrative.
Scan beyond Bombardier and this defence build out by reviewing a curated list of solid balance sheet and fundamentals (6 results) that could also benefit from long-cycle aerospace and defence spending.
Bombardier Investment Narrative Recap
To own Bombardier, you need to believe the focused business jet and defence model can keep turning a growing backlog, higher margin services and defence work into steadier earnings and cash generation. The MOU with BAE Systems touches that thesis but does not materially change the near term story until specific programs, volumes and economics are defined.
In the near term, the key swing factor is execution on deliveries and aftermarket capacity, while managing a still complex supply chain and a high debt load with negative equity. The biggest risk remains a drop in large business jet demand or order activity that would pressure utilization, pricing and the pace of balance sheet repair.
The recent decision to expand the American footprint and hire 800 people is the clearest operational tie in to the BAE Systems news. The Wichita Learning Center and new Fort Wayne service facility increase Bombardier’s ability to support a larger in service fleet and more defence and special mission work if it materializes from the MOU.
For catalysts, that U.S. buildout directly addresses constraints in aftermarket services, which analysts view as a key earnings driver. It also raises execution risk. Management needs to fill those roles, ramp new facilities and keep capital spending disciplined while still working down debt. Your view on how cleanly that expansion is executed will likely shape your conviction most.
Bombardier's current analyst narrative points to $11.8b in revenue and $1.2b in earnings by 2029, built on 6.7% yearly revenue growth and an earnings increase of about $247m from the $953.0m reported today.
Discover how Bombardier's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You have a very different picture if you focus on trade risk instead of the Bombardier Defense opportunity in the BAE Systems news. The most cautious analysts were working off revenue closer to $11.4b and earnings of about $1.1b by 2029. That more pessimistic setup shows how widely views can vary, and why fresh information like this agreement could eventually reshape both narratives.
Explore 4 other Bombardier fair value estimates, including one that suggests as much as 18% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bombardier research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bombardier. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bombardier's overall financial health at a glance.
Looking for more investment ideas beyond Bombardier?
If this Bombardier story has sharpened your appetite for deeper research, cast the net wider using the Simply Wall St Screener. You can scan for different types of opportunities that line up with your risk appetite and income needs.
- If capital preservation and steadier profiles matter most to you, shortlist companies from a 9 resilient stocks with low risk scores that aim to keep downside in check.
- For those hunting for quality at a reasonable price, start with a 4 high quality undervalued stocks that blends robust fundamentals with discounted market prices.
- If income is a key part of your plan, focus on a 3 dividend fortresses that highlights higher yielding payers with the potential to support regular distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com