


- Comfort Systems USA reported third quarter 2026 sales of US$3,766.3 million and net income of US$489.04 million, raised its quarterly dividend to US$1.00 per share, and outlined a planned CFO transition as long time finance leader Bill George retires in 2026 and current Chief Accounting Officer Julie Shaeff steps up.
- The combination of strong earnings, a higher cash payout, and a clear handover from a founding CFO to an experienced internal successor gives investors more visibility into how Comfort Systems USA intends to manage capital, handle its project pipeline and maintain financial discipline.
- We will now look at how Comfort Systems USA's strong third quarter earnings update reshapes the investment narrative investors have been using.
Scan Comfort Systems USA alongside other contractors with strong order books and capital discipline by reviewing the hand-picked list of solid balance sheet and fundamentals (24 results) that share similar financial resilience traits.
Comfort Systems USA Investment Narrative Recap
To own Comfort Systems USA, you need to believe its heavy skew to technology and industrial projects, including AI and data center work, keeps translating into steady backlog conversion and high utilization of its mechanical and electrical crews. The latest quarter shows that the business is currently handling a very large volume of work. The near term swing factor remains execution on complex projects inside that US$14.1b backlog, while the key operational risk is any slowdown or pause in AI data center or semiconductor build programs that would affect awards or timing.
The CFO transition plan does not materially alter that central thesis in the short run, because both Bill George and incoming finance chief Julie Shaeff have long tenures inside Comfort Systems USA. The more immediate watchpoints stay the same: how well the company manages project mix, maintains gross margins in both segments and converts strong earnings into free cash flow while technology customers potentially reassess the pace of new facilities.
The dividend increase to US$1.00 per share is the cleanest new data point that connects directly to the current thesis. A higher cash payout tells you management sees enough balance sheet strength and cash generation to return more capital to shareholders while continuing to fund roughly 5% of revenue into projects and acquisitions that support future activity. That matters for a contractor that relies on capacity investments, especially in modular facilities, to service large technology programs.
For you as an investor, the raised dividend slots in alongside existing catalysts such as the record US$14.1b backlog, the growing share of technology related work and the build out toward about 5 million square feet of modular construction capacity targeted by late summer 2027. The trade off is that returning more cash also raises the bar on execution. Any cooling in AI or semiconductor projects, or any compression in margins as project mix normalizes, could test how sustainable that higher payout really is over time.
Comfort Systems USA's current earnings are US$1.6b and analysts forecast earnings of US$3.4b by 2029, which implies an earnings increase of about US$1.8b, alongside forecast revenue of US$24.2b and an assumed 24.5% annual revenue growth rate over the next three years.
Uncover why Comfort Systems USA's fair value indicates a 63% potential upside to its current price that could narrow quickly.
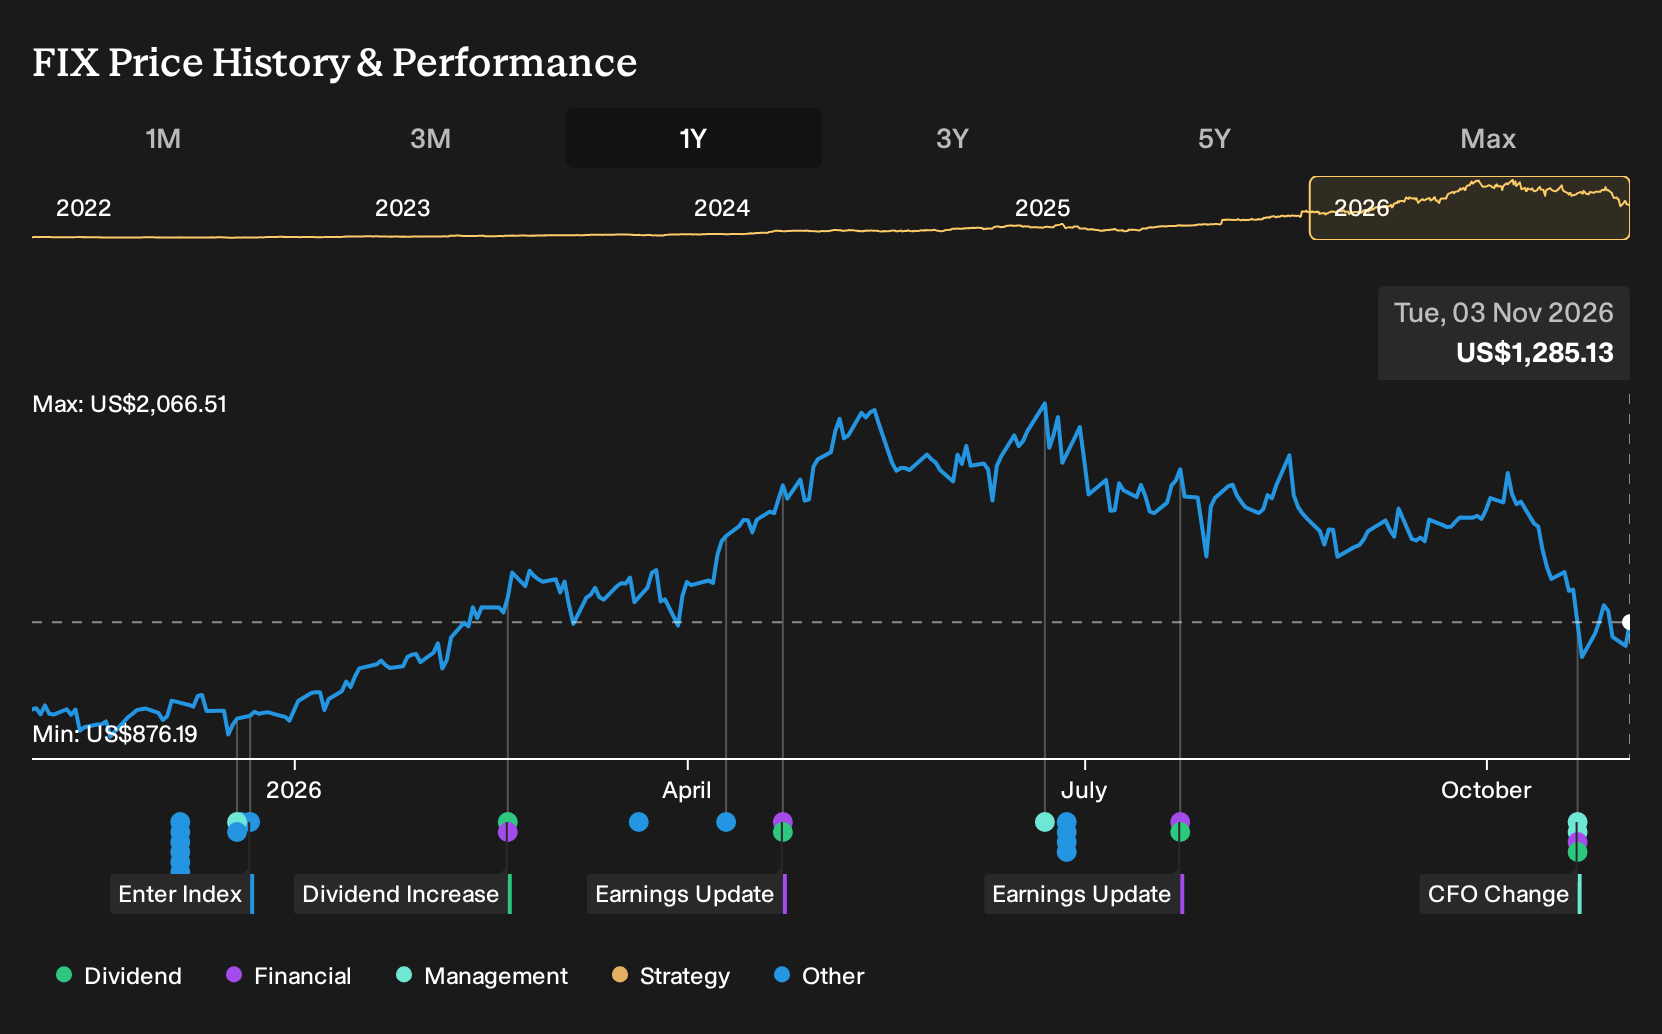
Exploring Other Perspectives
One alternate view focuses less on the CFO transition at Comfort Systems USA and more on how reliant your returns could be on tech and industrial demand staying strong. The most cautious analysts were only penciling in about US$20.8b of revenue and US$2.7b of earnings by 2029, so they saw far less upside than the consensus. These estimates were all set before this earnings beat and leadership change. You may want to compare several narratives and decide which assumptions feel realistic to you.
Explore 5 other Comfort Systems USA fair value estimates, including one that suggests it could be worth just $1808!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your Comfort Systems USA research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Comfort Systems USA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comfort Systems USA's overall financial health at a glance.
Looking for more Comfort Systems USA style investment ideas?
If Comfort Systems USA fits your checklist but you want a broader watchlist, the Simply Wall St Screener can help you quickly narrow down other candidates that share similar financial strengths or income profiles.
- If resilience matters most to you, start with a 30 resilient stocks with low risk scores that tilt toward balance sheet strength and more measured risk scores.
- If income is your priority, scan a 4 dividend fortresses that combine higher yields with fundamentals you can scrutinize in detail.
- If you are hunting for opportunities that are not yet widely followed, sift through a 19 high quality undiscovered gems that pair solid metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com