


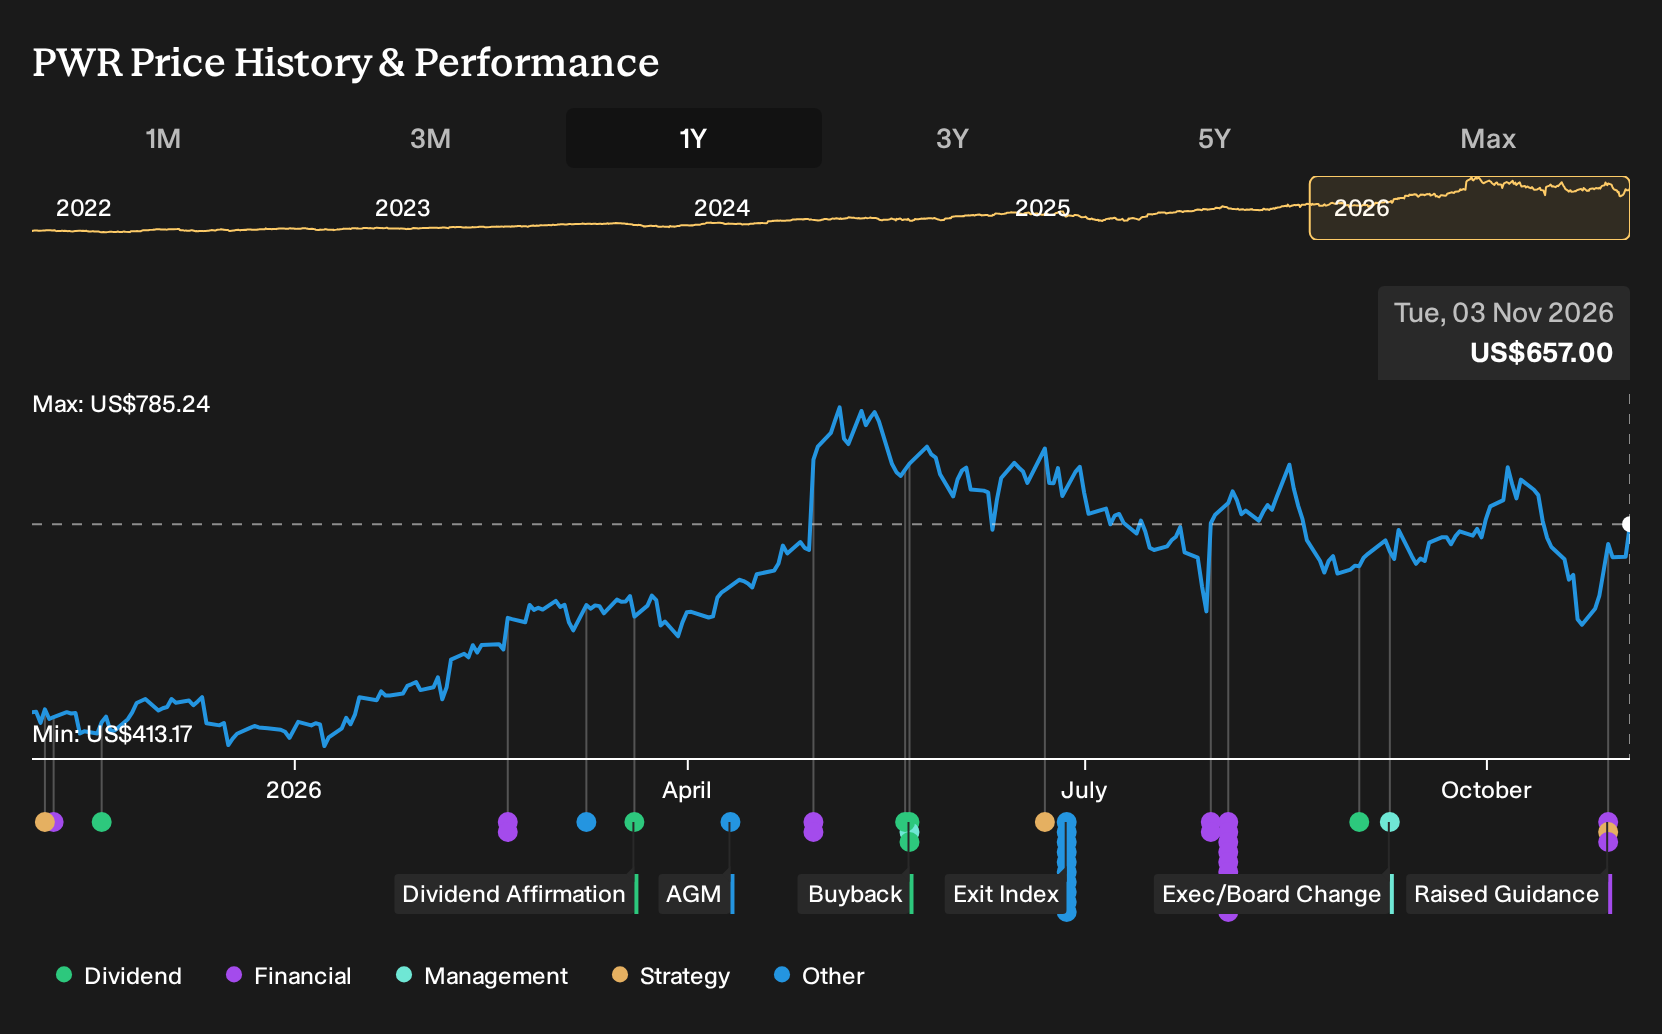
Quanta Services did not just talk about AI data centers and grid work during the period. It signed and executed on projects that helped lift revenue and profit in Q3 2026, while a record backlog tied to large-load power needs kept hitting the headlines. For Quanta Services shareholders, the return over the past year was 49.9%, including dividends. If you were deciding whether to buy in November 2025, what level of confidence in future contracts and margins would that outcome quietly imply?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond Quanta Services. See which of 42 power grid technology and infrastructure stocks may still merit a closer look.
The Argument You Would Have Been Weighing On Quanta Services
The shares cost US$451 at the start of the period. Anyone looking at Quanta Services then had to decide how durable the power grid and data center story might be.
The bullish Narrative put Fair Value at US$490, 9% above the start price. It leaned on rising grid upgrades and utility scale renewables, assuming Quanta could push into higher margin solution based work through integrated engineering, procurement, technology and labor.
The more cautious view set Fair Value at US$419, 7% below the start price. That case highlighted aggressive acquisitions and complex transmission projects, where integration missteps, permitting delays or project cancellations could pressure earnings.
What The Quanta Services Evidence Actually Tested
Quanta Services reported Q3 2026 revenue of US$12.01b and net income of US$694.9m, with net margin at 5.8% versus 4.4% a year earlier. That moved closer to the higher margin, solutions focused story in the bullish case. Insider selling and repeated commentary about rich valuation kept the cautious view alive, so the evidence cut both ways.
The key assumption investors were really betting on was margin resilience as complex AI power projects scaled. For a different stock, test that same claim by tracking net margin alongside any backlog or guidance headlines, rather than looking at order wins in isolation.
What Today's Quanta Services Price Already Assumes
Quanta Services now trades at US$657 after a 49.9% gain over the past year. The selected Narrative’s Fair Value sits below the current price, which frames today’s quote as already reflecting strong execution on power grid and AI data center work.
The Narrative leans on a packed backlog, vertical manufacturing bets and acquisitions. This raises the question of what must keep going right for today's price to make sense, including the assumption that higher fixed costs and rapid headcount growth still translate into consistently stronger margins.
"The numbers imply the share price already embeds strong execution on multi decade power and data center demand, successful integration of over $1.2b of recent deals, and delivery on management’s 15 to 20% adjusted EPS growth framework, so there is limited room for disappointment if any of these pillars weaken."
The price and this Narrative do not agree. → Uncover what this Narrative says Quanta Services is actually worth
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 28% below our estimate - supplies custom silicon and connectivity chips for large-scale digital infrastructure.
- Company 2 - 16% below our estimate - targets complex regulated programs that support an expanding qualified manufacturing pipeline.
- Company 3 - 25% below our estimate - expands photonics production capacity to address AI data center and automotive needs.
Three companies from the same screener. Open the full list of 34 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com