


National Bank Holdings (NBHC) just reported third quarter results that combined higher net interest income with a net loss, and also completed a share buyback program that retired roughly 2.29% of its stock.
The latest quarter has come with pressure on National Bank Holdings’ share price, with a 1-day move down of 1.50% and a 90-day share price return down 13.30% to US$37.49. However, the 1-year total shareholder return remains positive at 7.81% and the 3-year total shareholder return is 27.08%, suggesting longer term holders have still seen gains despite the recent earnings setback and completion of the buyback program.
Compare National Bank Holdings' latest setback with other banks that still pass strict balance sheet and earnings filters by scanning the list of solid balance sheet and fundamentals (24 results) today.
After a quarter that mixed higher net interest income with a loss and buybacks that trimmed the share count, the question around National Bank Holdings now shifts: Has most of the easy upside already played out, or is the valuation still leaving room ahead?
Most Popular Narrative: 18.5% Undervalued
On the most followed view, National Bank Holdings carries a fair value of $46, which sits above the latest close at $37.49 and puts the recent loss-making quarter in a wider earnings and capital story.
The main thing that has to go right is that National Bank Holdings converts its loan growth, Vista integration, and digital investments like 2UniFi into durable, high quality earnings without eroding its conservative credit profile or near 4% net interest margin.
The current valuation implies the market is discounting National Bank Holdings' guidance for stronger EPS and its capital-supported shareholder returns.
See why 4 investors see National Bank Holdings as 18% undervalued.
Result: Fair Value of $46 (UNDERVALUED)
Still, National Bank Holdings faces two pressure points that could break this thesis if they worsen: credit concentration in sectors like trucking and commercial real estate, and the early stage 2UniFi spend that currently outweighs its revenue.
Find out about the key risks to this National Bank Holdings narrative.
Another View: What The P/E Ratio Says About National Bank Holdings
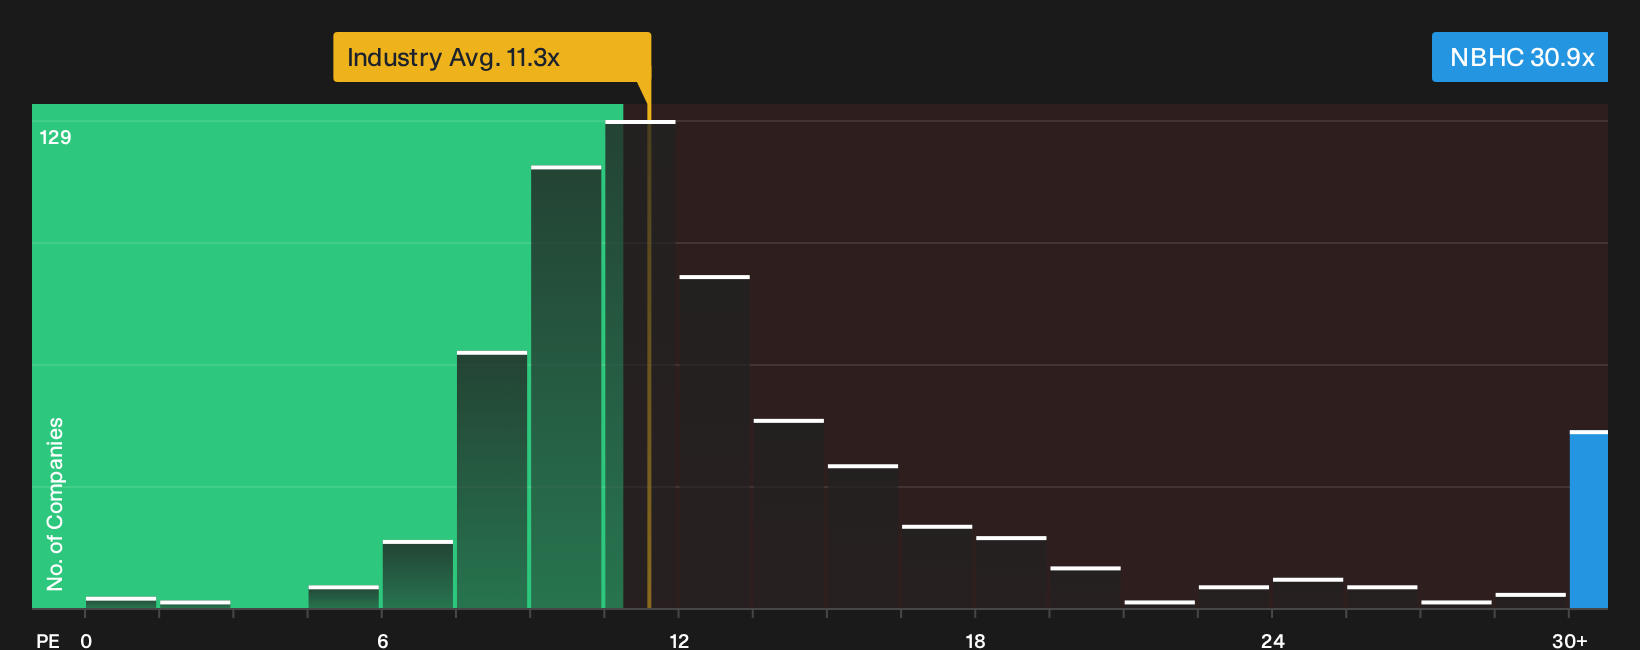
There is a very different story when you look at National Bank Holdings through its P/E ratio instead of a fair value estimate. The stock trades on about 30.9x earnings, compared with 12.3x for peers and a fair ratio of 23.6x. This tilts this method toward an expensive verdict and raises the question of how much optimism is already in the price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around National Bank Holdings can tempt investors to lean on headlines instead of hard numbers. Consider reviewing the figures promptly, weighing both the concerns and the potential upsides, and grounding your view in the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond National Bank Holdings?
Do not stop with one bank. Use the Simply Wall Street Screener to surface fresh ideas now, before the next wave of opportunities moves without you.
- Target dependable cash generators by zeroing in on companies with strong balance sheets and resilient fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential value opportunities by focusing on stocks that combine quality metrics with discounted prices through the 34 high quality undervalued stocks.
- Build a steadier income stream by scanning for companies offering higher dividend yields and solid profiles via the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com