


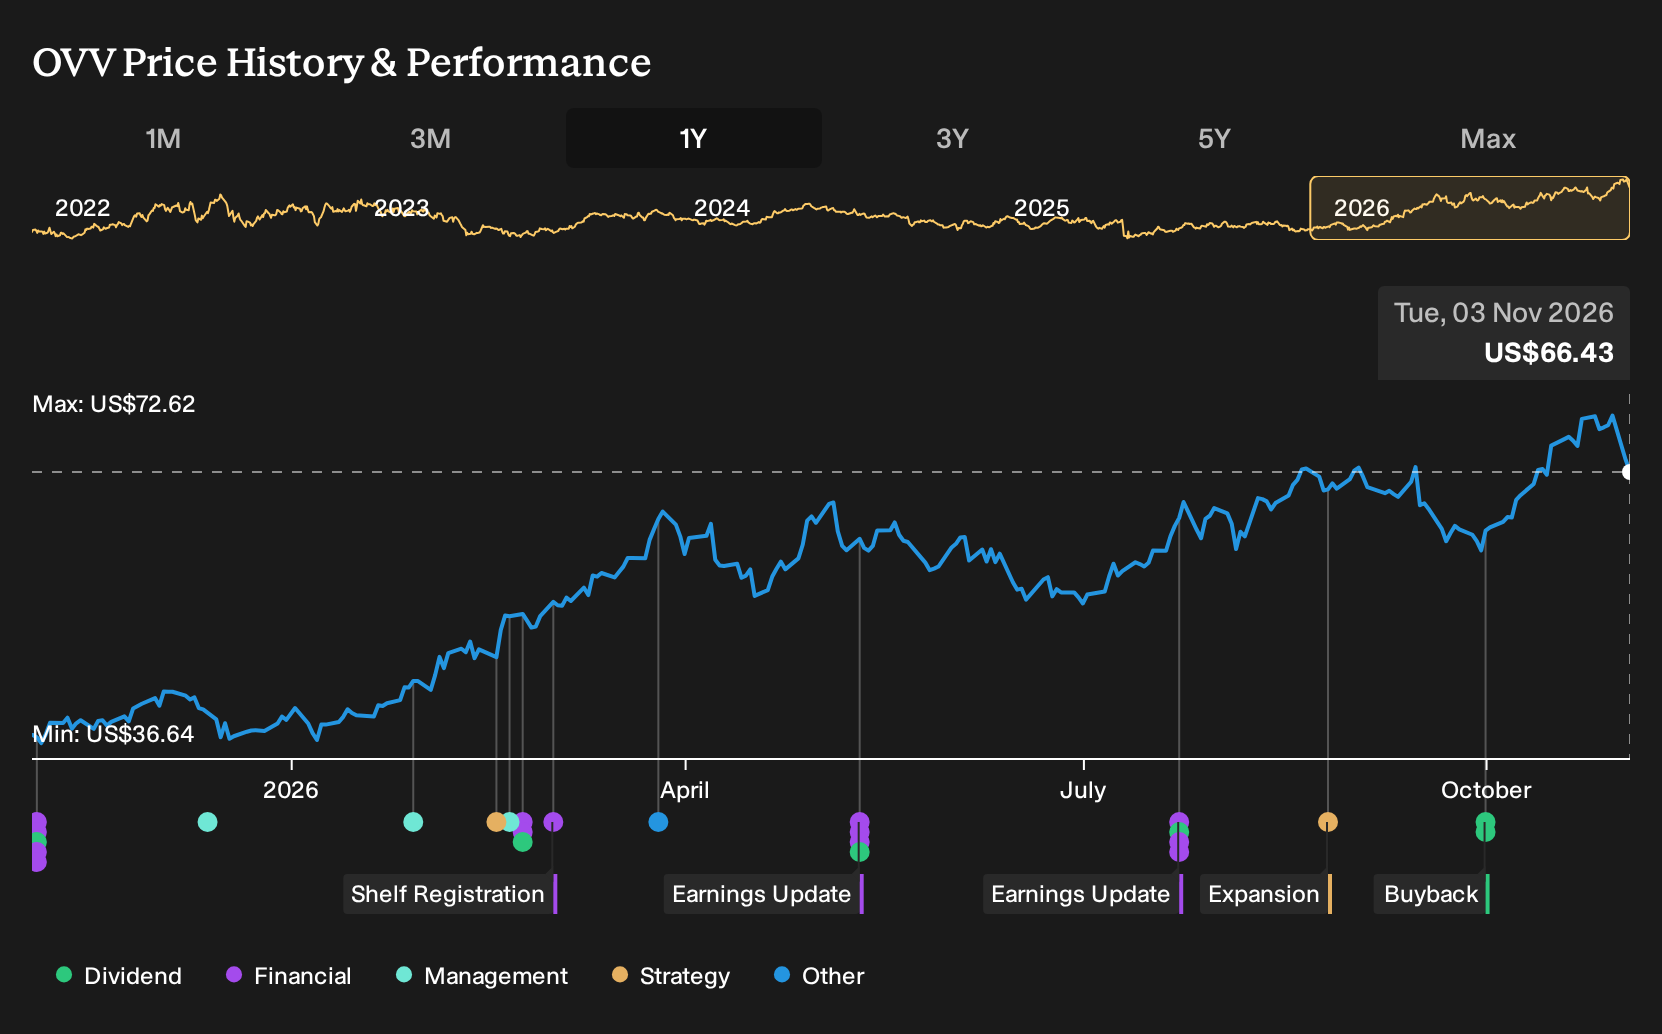
- Ovintiv reported third quarter 2026 revenue of US$2.6b and net income of US$549 million, with basic earnings per share from continuing operations of US$2.01, and confirmed an agreement to acquire Logan Energy Corp. alongside new acreage in key oil and gas basins.
- The combination of higher reported profit, active share repurchases and dividends, and the Logan Energy Corp. deal gives you a clearer view of how Ovintiv is using current cash generation to reshape its portfolio while keeping full year 2026 guidance unchanged.
- We will now examine how Ovintiv's stronger reported earnings and the Logan Energy acquisition agreement could influence the broader investment narrative.
Ovintiv Investment Narrative Recap
To stay invested in Ovintiv, you need to be comfortable with a cash flow story built on operational efficiency, a large drilling inventory and disciplined capital returns. The latest quarter, with US$2.6b of revenue and US$549 million of net income, supports that narrative but does not remove the core near term swing factor: commodity prices and well performance in key plays.
The biggest short term catalyst remains execution in the Permian and Montney, where efficiency gains and cost control feed directly into cash generation. The main risk is that recent strength sits against a history of one off items and impairments, so any weaker pricing or volumes could quickly feed into softer reported earnings.
The most relevant update here is Ovintiv’s decision to return roughly 69% of quarterly free cash flow through buybacks and dividends, while keeping full year 2026 guidance unchanged. That indicates management is leaning on the same playbook: use efficiency and premium inventory to support cash returns, even as earnings include some non recurring items.
For you as an investor, that capital return framework only works if the operational side keeps delivering, including the integration of recent acquisitions such as Logan Energy Corp. Execution missteps, weaker realized pricing or fresh impairments could test the payout level, so the sustainability of those distributions is tightly linked to how well Ovintiv runs its expanded asset base.
Ovintiv's outlook projects US$8.9b in revenue and US$1.9b in earnings by 2029, based on analysts assuming revenue will decrease by 2.4% per year. This implies earnings would roughly double, increasing by about US$980 million from US$920.0 million today.
Uncover how Ovintiv's fair value indicates a 22% potential upside to its current price, a gap that could narrow quickly as sentiment shifts.
Exploring Other Perspectives
One alternate angle focuses on Ovintiv’s bullish catalyst around long term earnings power. The most optimistic analysts were modelling revenue of about US$10.4b and earnings of US$3.2b by 2029, well above the US$8.9b and US$1.9b that consensus used. Those views were set before this quarter’s results and the Logan Energy deal, so you may see narratives shift as fresh numbers filter through. Opinions can differ widely, so it is worth comparing these assumptions with your own expectations.
Explore 5 other Ovintiv fair value estimates, including one that suggests up to 96% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ovintiv research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ovintiv. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ovintiv's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ovintiv?
If Ovintiv's cash generation and capital return plan appeals to you, it can help to line it up against other opportunities using the Simply Wall St Screener. That way you can see how this stock compares with peers that have different income profiles, balance sheet strength or upside potential.
- If you want potential value on your side, scan through 34 high quality undervalued stocks that pair strong fundamentals with prices that still look conservative.
- If resilience matters most to you, filter for 30 resilient stocks with low risk scores where balance sheets and risk scores aim to prioritize downside protection.
- If you are hunting for ideas that the market may have overlooked, review 19 high quality undiscovered gems that combine quality metrics with relatively low visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com