


Carrier Global (CARR) has put fresh capital plans on the table, pairing new fixed rate notes with a broad shelf registration that covers common equity, preferred shares, and multiple debt securities.
The latest funding plans land after a busy few weeks for Carrier Global, with a sharp goodwill impairment, higher full year sales guidance and fresh investment in data center capacity all landing in quick succession. Despite this, the 90 day share price return is down 15.38%, while the 3 year total shareholder return of 14.36% points to a much steadier long run experience for investors. This suggests recent momentum has cooled even as the longer term story remains intact.
Scan beyond Carrier Global's latest moves in data centers and capital markets by sizing up a hand-picked lineup of 42 power grid technology and infrastructure stocks positioned for the same long-term infrastructure build-out.
The recent drop in Carrier Global’s share price sits against higher sales guidance and fresh capital plans. Is this move really about business fundamentals, or has sentiment simply swung too far?
Most Popular Narrative: 38% Undervalued
Carrier Global’s most followed narrative pegs fair value at $90 per share against a last close of $55.37, framing the recent sell off as a valuation gap rather than a broken story.
The Carrier Global thesis has been reviewed and reaffirmed, with the updated narrative shifting the focus from existing data center, heat pump and cost reduction trends to a broader view that now highlights future earnings potential from new U.S. capacity, energy platform partnerships and underpenetrated digital and services opportunities.
Previously the emphasis was on current data center HVAC orders and backlog through 2028 supporting revenue and service earnings. The focus is now on the Fort Worth investment and new U.S. capacity, which could extend equipment and service revenue beyond the visible backlog.
See why 1 investors see Carrier Global as 38% undervalued.
Result: Fair Value of $90 (UNDERVALUED)
Still, the bullish Carrier Global story depends on recent margin pressure easing and on any securities investigation not dragging into costly, confidence sapping litigation.
Find out about the key risks to this Carrier Global narrative.
Another Take On Carrier Global’s Valuation
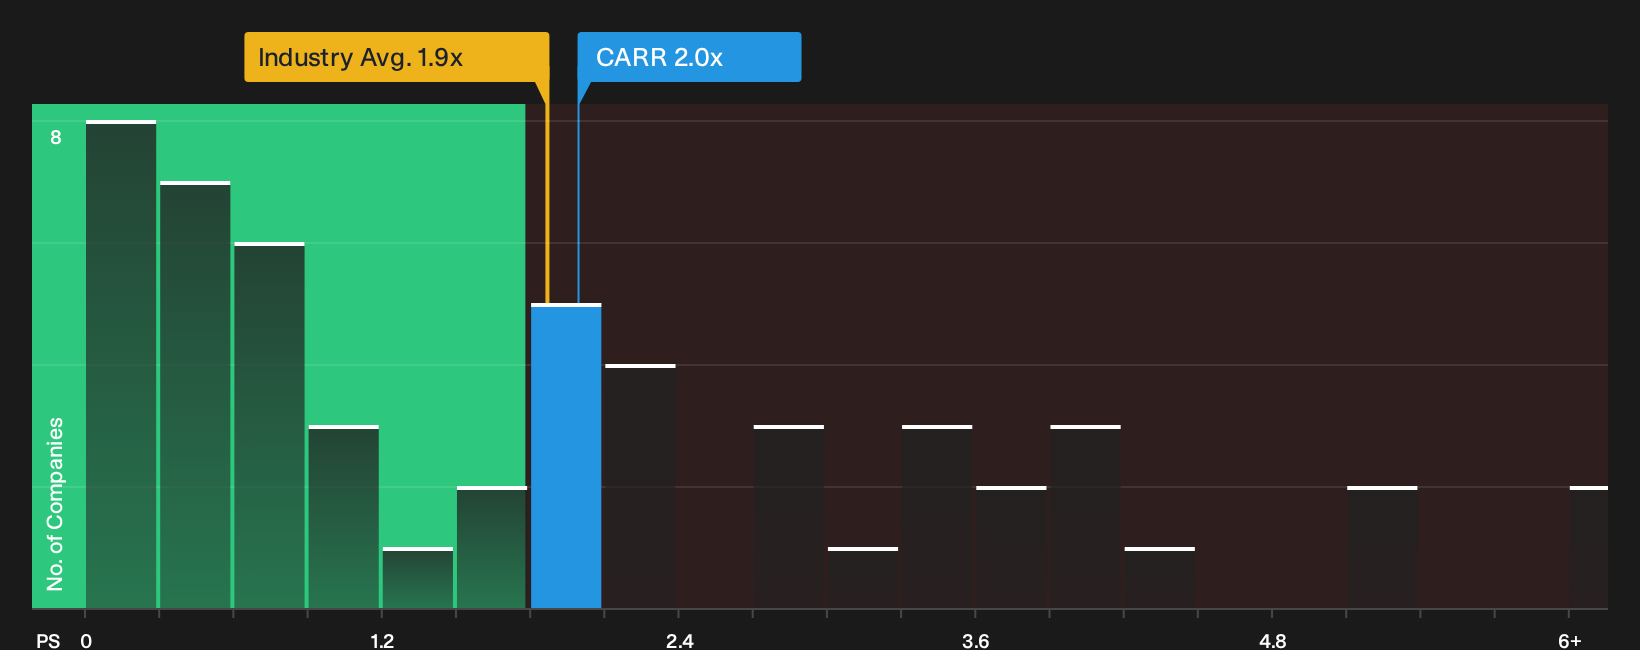
DCF and narrative targets lean toward upside for Carrier Global. The simpler P/S lens is more cautious. CARR trades at roughly 2x sales, slightly above the US Building industry at 1.9x, yet below peers at 3.5x and under its own fair ratio of 2.3x. That mix hints at both a quality premium and some valuation risk. Which signal matters more for you right now?
To unpack what this pricing gap could mean in practice, including how it might close toward that fair ratio over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment on Carrier Global feels mixed after this, that is the point, and it is exactly why fresh data matters more than headlines. Take a moment to weigh the upside and downside for yourself, then run through the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Carrier Global?
If Carrier Global has sharpened your thinking, let that momentum carry into a wider watchlist built around clear themes and hard numbers.
Use the Simply Wall Street Screener to spot fresh opportunities that fit your style before they move out of reach.
- Target durable quality by zeroing in on companies with strong finances and clean balance sheets through our list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunity by scanning a curated 34 high quality undervalued stocks that blend solid fundamentals with appealing price tags.
- Build a smoother ride by focusing on 30 resilient stocks with low risk scores that may help steady your portfolio when markets feel choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com