


- Bowhead Specialty Holdings reported third quarter 2026 results with revenue of US$171.77 million, net income of US$12.94 million, and diluted EPS of US$0.38 from continuing operations.
- The nine month figures show revenue of US$491.32 million and net income of US$45.09 million, so the weaker quarter lands against a stronger year to date earnings picture.
- We will now see how the mixed quarter for Bowhead Specialty Holdings, with higher revenue but lower net income, could influence its investment narrative.
Scan beyond Bowhead Specialty Holdings and compare this earnings story with a curated group of insurers and financials that pair resilient balance sheets with consistent profitability using the list of solid balance sheet and fundamentals (24 results)
Bowhead Specialty Holdings Investment Narrative Recap
For Bowhead Specialty Holdings, the core belief is that a focused specialty insurer can keep growing its underwriting footprint while holding the line on profitability. The latest quarter shows that this is not automatic. Revenue reached US$171.77 million but net income of US$12.94 million and diluted EPS of US$0.38 were lower than a year ago.
The short term hinge now is underwriting discipline in long tail lines while the book scales. The biggest current risk remains adverse claims trends and reserving accuracy, especially with social inflation pressures. This quarter nudges that concern into sharper focus but does not yet reshape the broader business thesis.
The most relevant fresh data point for you is the full nine month 2026 picture. Bowhead Specialty Holdings reported revenue of US$491.32 million and net income of US$45.09 million, both above the prior year periods, with diluted EPS of US$1.33 from continuing operations. That puts the softer quarter in the context of a stronger year to date result.
That contrast matters for assessing catalysts. Execution around growth in specialty casualty and healthcare, plus scaling platforms like Baleen, still hinges on keeping loss ratios and expenses contained. The key watch item after this update is whether the third quarter margin pressure proves temporary or starts to signal more persistent claims or pricing strain in the portfolio.
Bowhead Specialty Holdings' current analyst narrative points to forecast revenue of US$980.4 million and earnings of US$102.9 million by 2029, based on an assumed 18.8% yearly top line expansion. That profile implies earnings today of US$58.4 million would need to increase by roughly US$44.5 million to reach the consensus forecast for 2029.
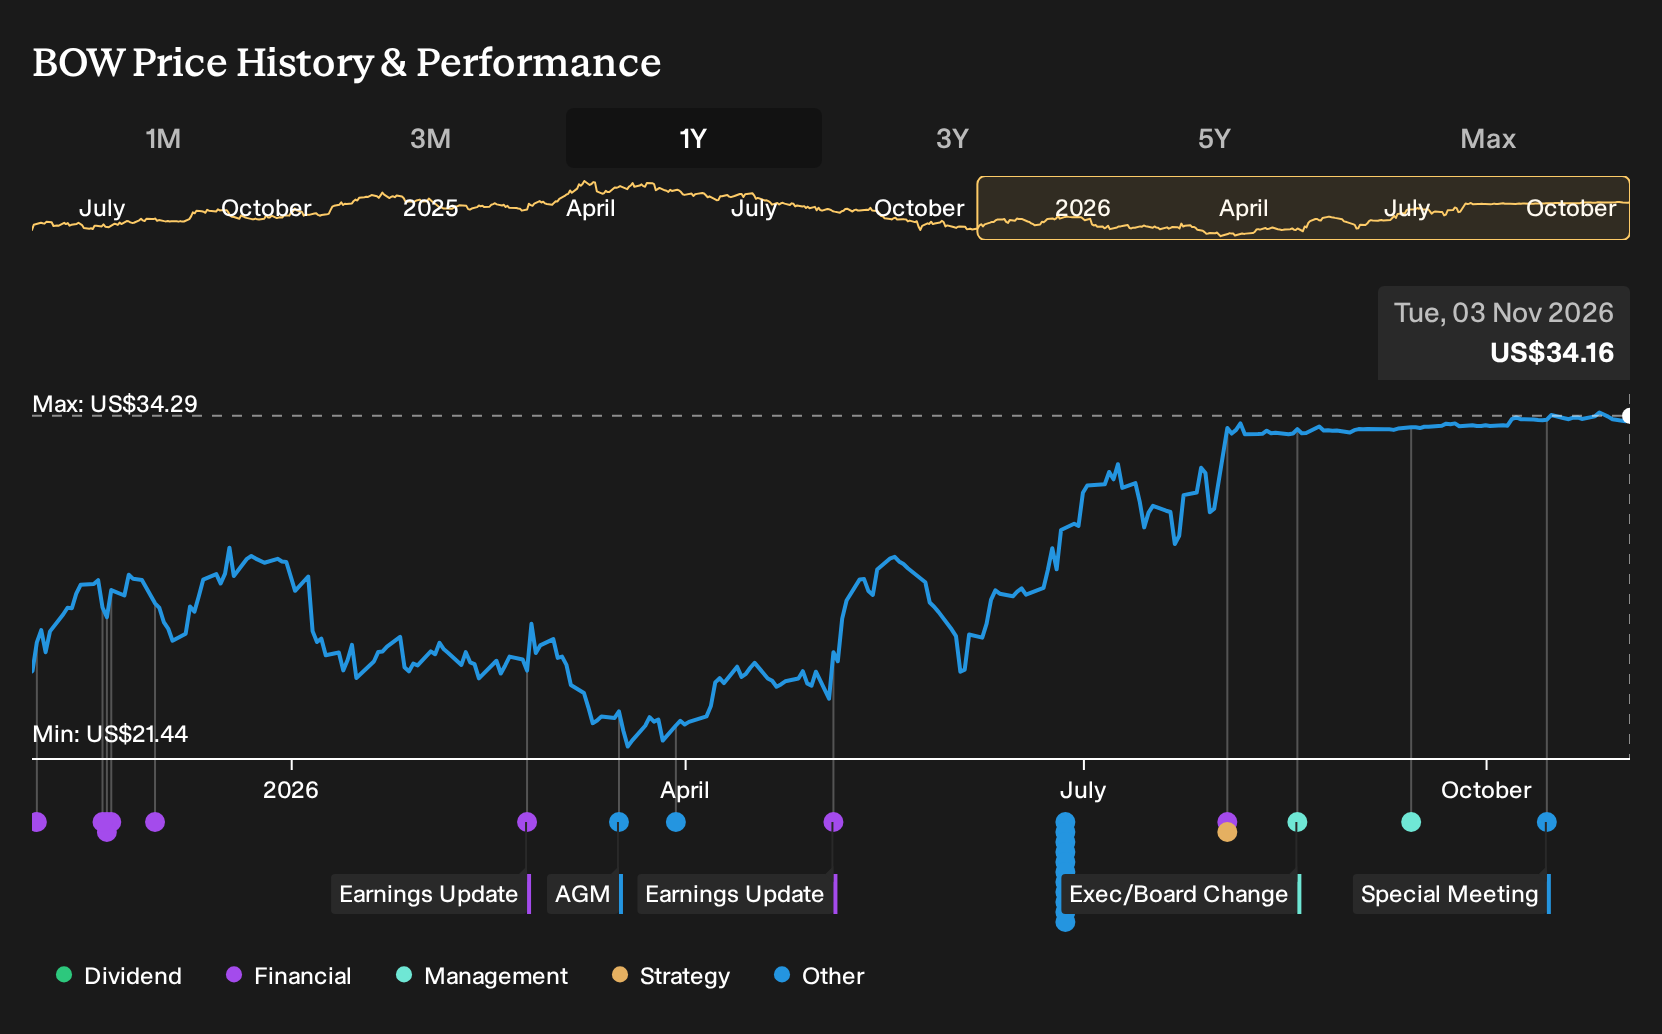
Uncover why Bowhead Specialty Holdings' fair value indicates a valuation gap that is approximately aligned with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Bowhead Specialty Holdings' digital platforms as the real swing factor. Before this earnings release, that bullish group was modeling roughly 21.1% annual revenue growth and earnings of US$120.9 million by 2029. This latest quarter may either reinforce that optimism or prompt a rethink, so it makes sense to compare how different forecasts line up before you decide which story feels more realistic.
Explore another Bowhead Specialty Holdings fair value estimate, including one that suggests there may be as much as 66% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Bowhead Specialty Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Bowhead Specialty Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bowhead Specialty Holdings' overall financial health at a glance.
Looking for more Bowhead Specialty Holdings investment ideas?
If the Bowhead Specialty Holdings story has you thinking about portfolio upgrades, it can help to line it up against other companies with different strengths. The Simply Wall St Screener gives you a way to quickly scan for stocks that share some of the qualities you care about, then narrow in on the ones that best fit your own approach.
- For investors who care most about quality and valuation, use the 34 high quality undervalued stocks that combine healthy fundamentals with prices that may not fully reflect them.
- If capital preservation is front of mind, focus on resilience first and growth second with the 30 resilient stocks with low risk scores that have stronger risk profiles.
- Those hunting for under-the-radar opportunities can start with the 19 high quality undiscovered gems that pair solid financials with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com