


Kraft Heinz has delivered a mixed journey for shareholders over the last few years, and the question now is whether the current share price around US$24.52 is properly backed by its sales power. With the stock showing modest gains in the past year but a clear drag over longer horizons, investors are asking how much revenue muscle the business really brings to justify today’s valuation.
- The share price decline of 15.5% over 5 years keeps the spotlight firmly on whether Kraft Heinz's current valuation can be explained by the revenue profile the business produces today.
- Recent commentary around debt reduction and a dividend payout that sits near half of free cash flow suggests management may have some room to reinvest in the product portfolio. This can influence how much sales growth investors are effectively paying for at this price.
- There is a second opinion on Kraft Heinz worth weighing. See what analysts think Kraft Heinz's shares could be worth.
The issue now is whether Kraft Heinz's market value is appropriately anchored to the level and quality of its sales.
If you want to test the same sales based valuation question you are asking of Kraft Heinz across a broader set of companies, take a look at 34 high quality undervalued stocks.
Is Kraft Heinz Still Cheap on Sales?
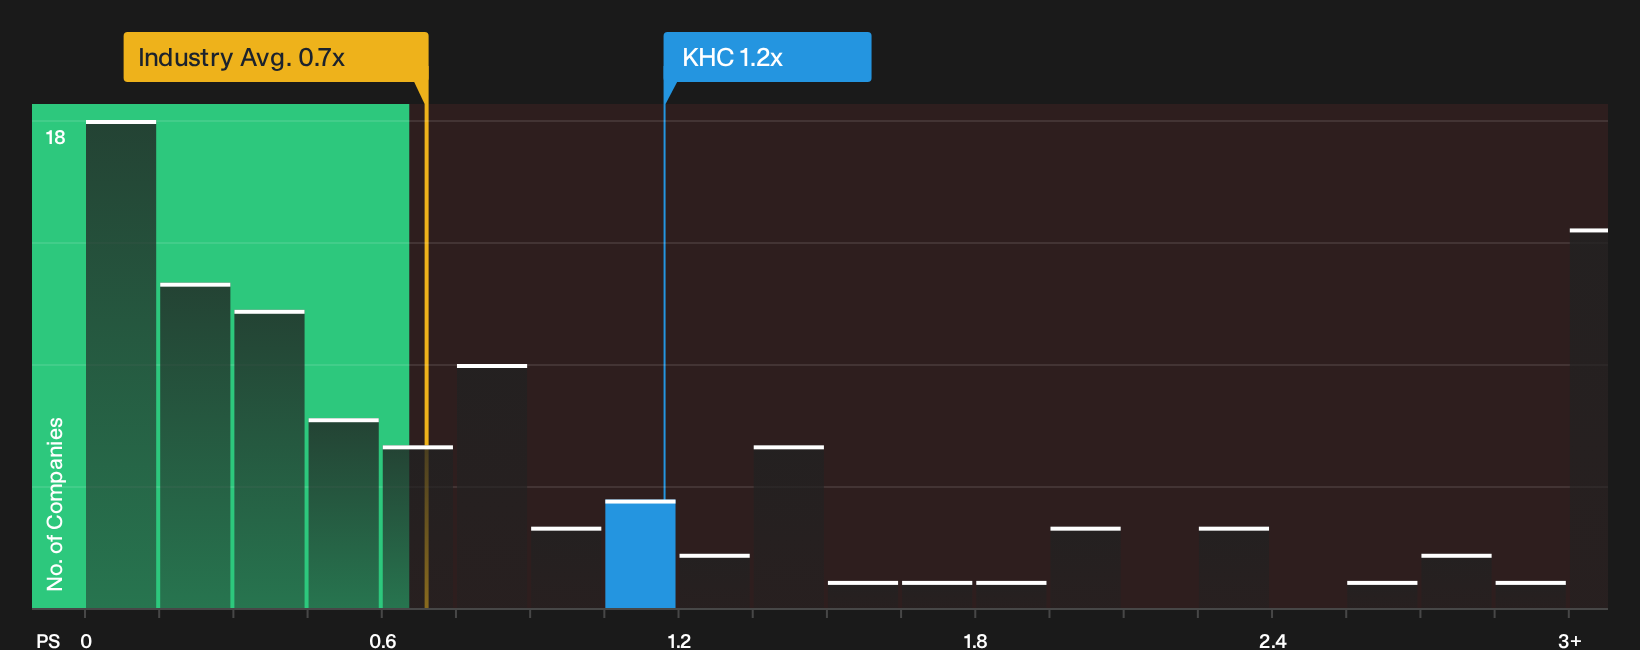
P/S is a clean way to look at Kraft Heinz because it ties the share price directly to the cash the business brings in from selling food products. At a P/S of 1.2x, Kraft Heinz trades above the broader food industry average of 0.7x, yet modestly below its peer group on about 1.4x.
Because the Fair Ratio reflects what investors might expect to pay for a company with Kraft Heinz's mix of growth prospects, margins, size and risk, the current 1.2x reading screens below that reference point and therefore as undervalued on this lens. Despite the recent guidance raise and debt reduction helping sentiment, the market is still pricing Kraft Heinz on a lower sales multiple than that Fair Ratio signal suggests. Explore the numbers behind Kraft Heinz's P/S valuation.
The Kraft Heinz Narrative: What Would Justify Today's Price?
Narratives for Kraft Heinz pick up where the valuation puzzle leaves off by spelling out which combinations of future growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than today's price, and they sit on Simply Wall St's Community page. Each narrative treats Kraft Heinz's implied fair value as a thesis about the business that you can watch over time, rather than a one-off snapshot.
Kraft Heinz draws sharply different reads in the community, with one group seeing a contrarian income opportunity and another focusing on margin and volume pressure.
Bull case: 30% undervalued
"Kraft Heinz is not suddenly a glamour stock, and that is precisely what makes it interesting, the first-quarter update did not offer some miraculous reinvention…"
Discover why this Narrative puts Kraft Heinz at 30% undervalued.
Bear case: 29% overvalued
"Although Kraft Heinz is lifting brand, marketing and R&D spend to a new base level, the risk is that higher promotion intensity simply defends share rather than reverses volume declines…"
Explore why this Narrative puts Kraft Heinz at 29% overvalued.
One more Kraft Heinz angle investors often overlook
Kraft Heinz is not just about valuation math, and the internal checks on this business have also raised a separate set of concerns that deserve a closer look before you commit fresh capital. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com