


Kyocera came into this earnings day on the back foot, with the stock down about 15% over the past three months and trading at a P/E of 26.1x, above the broader Japanese electronics sector but below direct peers. The Q2 2027 report then landed with a jolt. Quarterly basic earnings per share dropped to ¥10.06 on net income of ¥12,854 million, a sharp step down from Q1’s profitability, even though revenue held at ¥552,954 million. For investors who bought into a clean earnings recovery story, that profit squeeze is the real headline behind today’s price action.
Like Kyocera’s technology and market reach but concerned about earnings per share compression at a 26.1x P/E? Compare this setup with companies that pair resilient profitability with stronger balance sheets in our list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥552,954 million vs. ¥513,347 million (up about 7.7%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥12,854 million vs. ¥18,397 million (down about 30.1%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥10.06 vs. ¥13.18 (down about 23.7%)
- Trailing 12-Month Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥158,859 million vs. ¥43,559 million (very large year over year increase, a bit above 3.6x)
Ask Charlie what drove Kyocera’s big earnings rebound.
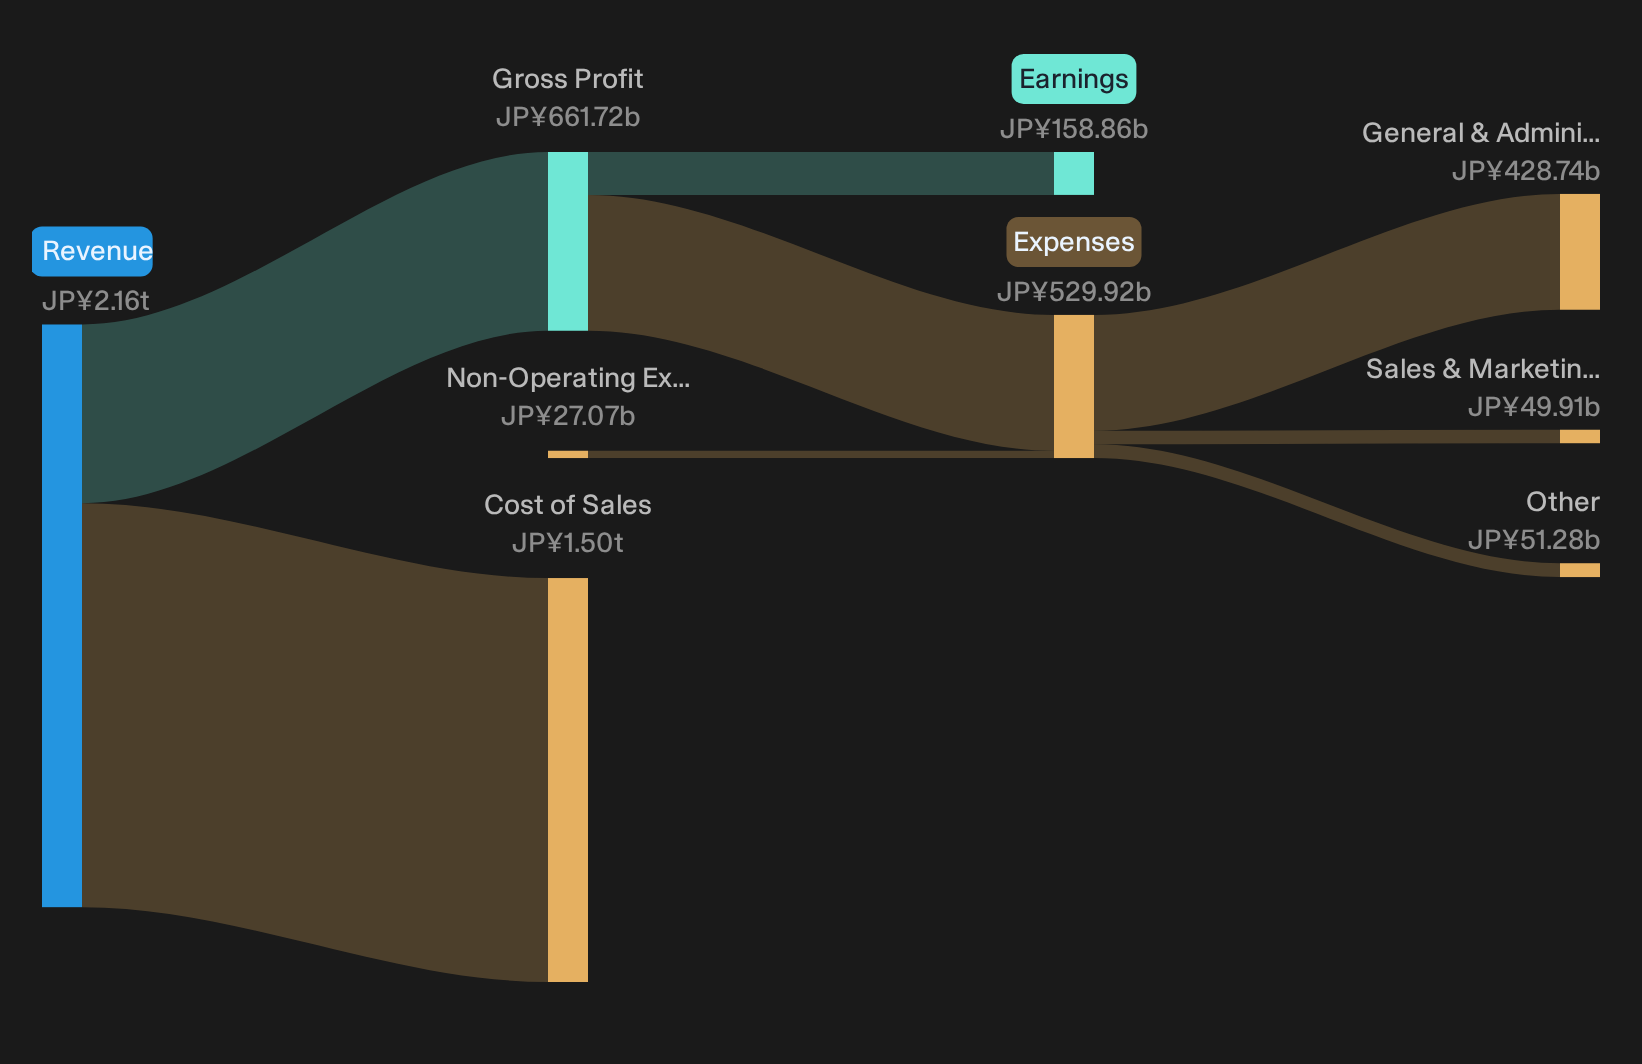
Kyocera’s Diversification Tested but Growth Pockets Intact
For anyone leaning bullish on Kyocera as a diversified components supplier, the latest figures cut both ways. Revenue of ¥552,954 million is higher than the prior year, and trailing 12 month net income excluding extra items is very large versus a year ago. That sits alongside fresh news of raised full year sales guidance tied to AI and semiconductor demand and a series of data center focused projects. The top line and longer run profit pool still point to meaningful exposure to digital and industrial spending.
Profit Squeeze Keeps Kyocera Risk Debate Alive
The bear case gets real support from this quarter. Net income excluding extra items fell about 30% year over year and basic EPS declined about 24%, even as sales moved up. The share price has fallen across 7, 30 and 90 day windows, which indicates investors are reacting to that earnings pressure. Management kept full year profit guidance unchanged despite lifting revenue, highlighting cost and mix headwinds. Diversification supports the story over time, but near term profitability appears fragile enough to justify caution around execution risk.
With profit guidance flat, a P/E of 26.1x and the share price above the DCF reference, the central issue is balance sheet resilience. Verify whether Kyocera’s cash, debt and coverage ratios truly support this valuation in the financial health analysis of Kyocera stock.Hunt For Stronger Balance Sheets
Kyocera reminds investors that earnings momentum can feel uncertain when profit guidance stalls. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 48% below our estimate - uses an AI centric security platform to turn heavy cloud and incubation spending into recurring software and services contracts.
- Company 2 - 17% below our estimate - adds salespeople to win maintenance contracts that deepen route density and enhance returns on installed elevator and modernization projects.
- Company 3 - 40% below our estimate - pushes AI driven hiring tools and marketing platforms that link fees to job placements and transaction volume across employment and local services.
Three companies from the same screener. Open the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com