


- PPL is preparing to report third quarter 2026 results, with expectations for higher total revenue and earnings per share supported by a US$275 million rate increase in Pennsylvania and execution of its US$23b capital program through 2029.
- The same regulatory decisions that underpin PPL’s near term earnings outlook also help fund grid investments tied to growing data center electricity demand, which could influence how its long term capital plan translates into regulated returns.
- We will look at how PPL's investment narrative may be affected by anticipated stronger quarterly earnings supported by Pennsylvania rate relief.
Scan how PPL's grid spending story compares with other regulated utilities gearing up for heavier power demand using our hand picked 42 power grid technology and infrastructure stocks
PPL Investment Narrative Recap
To own PPL, you need to be comfortable with a straightforward utility story. The business is leaning hard into regulated grid and generation spending tied to large data center and industrial load across Pennsylvania and Kentucky, with the Pennsylvania rate increase supporting that plan. The near term catalyst is simple: investors are watching whether stronger quarterly earnings confirm that regulators are still backing this buildout.
The biggest risk sits on the other side of that same equation. A less generous stance from regulators on large load tariffs or base rates would leave more of PPL's roughly US$23b capital plan exposed. Higher interest and operating costs sit in the background, but the recent news mainly fine tunes expectations rather than changing the thesis.
The Pennsylvania rate decision remains the announcement that matters most around this earnings update. It directly affects how PPL can fund its 2026 capital spending of about US$5b within the broader US$23b program through 2029, and it helps shape expectations for how much of that investment flows into allowed returns.
For you as a shareholder, this ties into both the upside and the pressure points. Constructive regulatory support helps PPL convert accelerating data center and economic development pipelines into rate base growth. Any shift toward tighter policies, including more cautious treatment of very large customers, would test that plan and could weigh on earnings coverage of interest and dividends.
What The Current Forecasts Assume For PPL
PPL's narrative projects US$11.1b revenue and US$1.9b earnings by 2029. This rests on analysts factoring in 5.8% yearly revenue growth and an earnings increase of about US$600m from US$1.3b today.
Uncover why PPL's fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
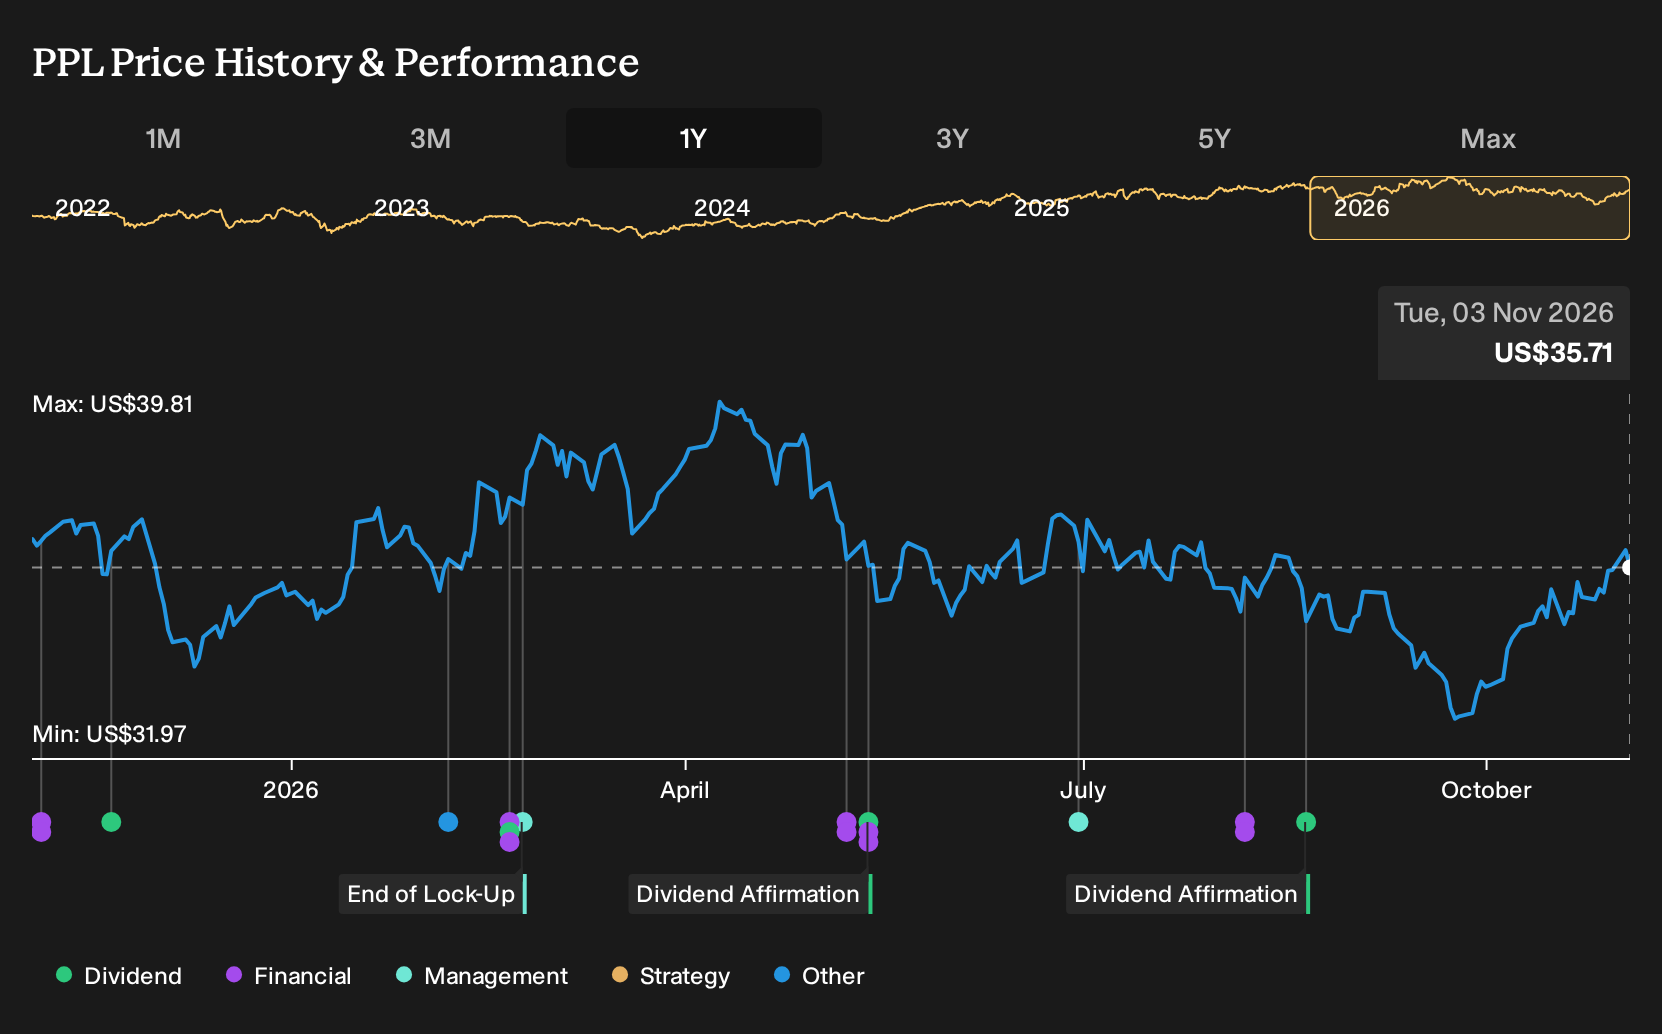
The Simply Wall St Community only has two fair value views on PPL so far, yet they already span from about US$19.80 to just over US$40. That split sits next to the recent technical optimism around a break above the 200 day moving average and a 9.7% four week rally, which you should weigh against unresolved regulatory and data center policy risks. Explore those contrasting opinions before deciding how PPL fits your own expectations.
Explore another PPL fair value estimate, including one that suggests potential upside of up to 12% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your instincts.
- A great starting point for your PPL research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for PPL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PPL's overall financial health at a glance.
Looking for more investment ideas beyond PPL?
If PPL's setup has sharpened your thinking but you want a broader watchlist, use this as a springboard to scan other opportunities with different risk and income profiles.
- If you want resilient balance sheets to help you sleep at night, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions.
- For investors who care most about valuation and quality together, filter for 34 high quality undervalued stocks that combine sound cash flows with disciplined balance sheets.
- If you prefer to focus on regular income, build a watchlist anchored in 4 dividend fortresses that currently offer yields above 5%.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com