


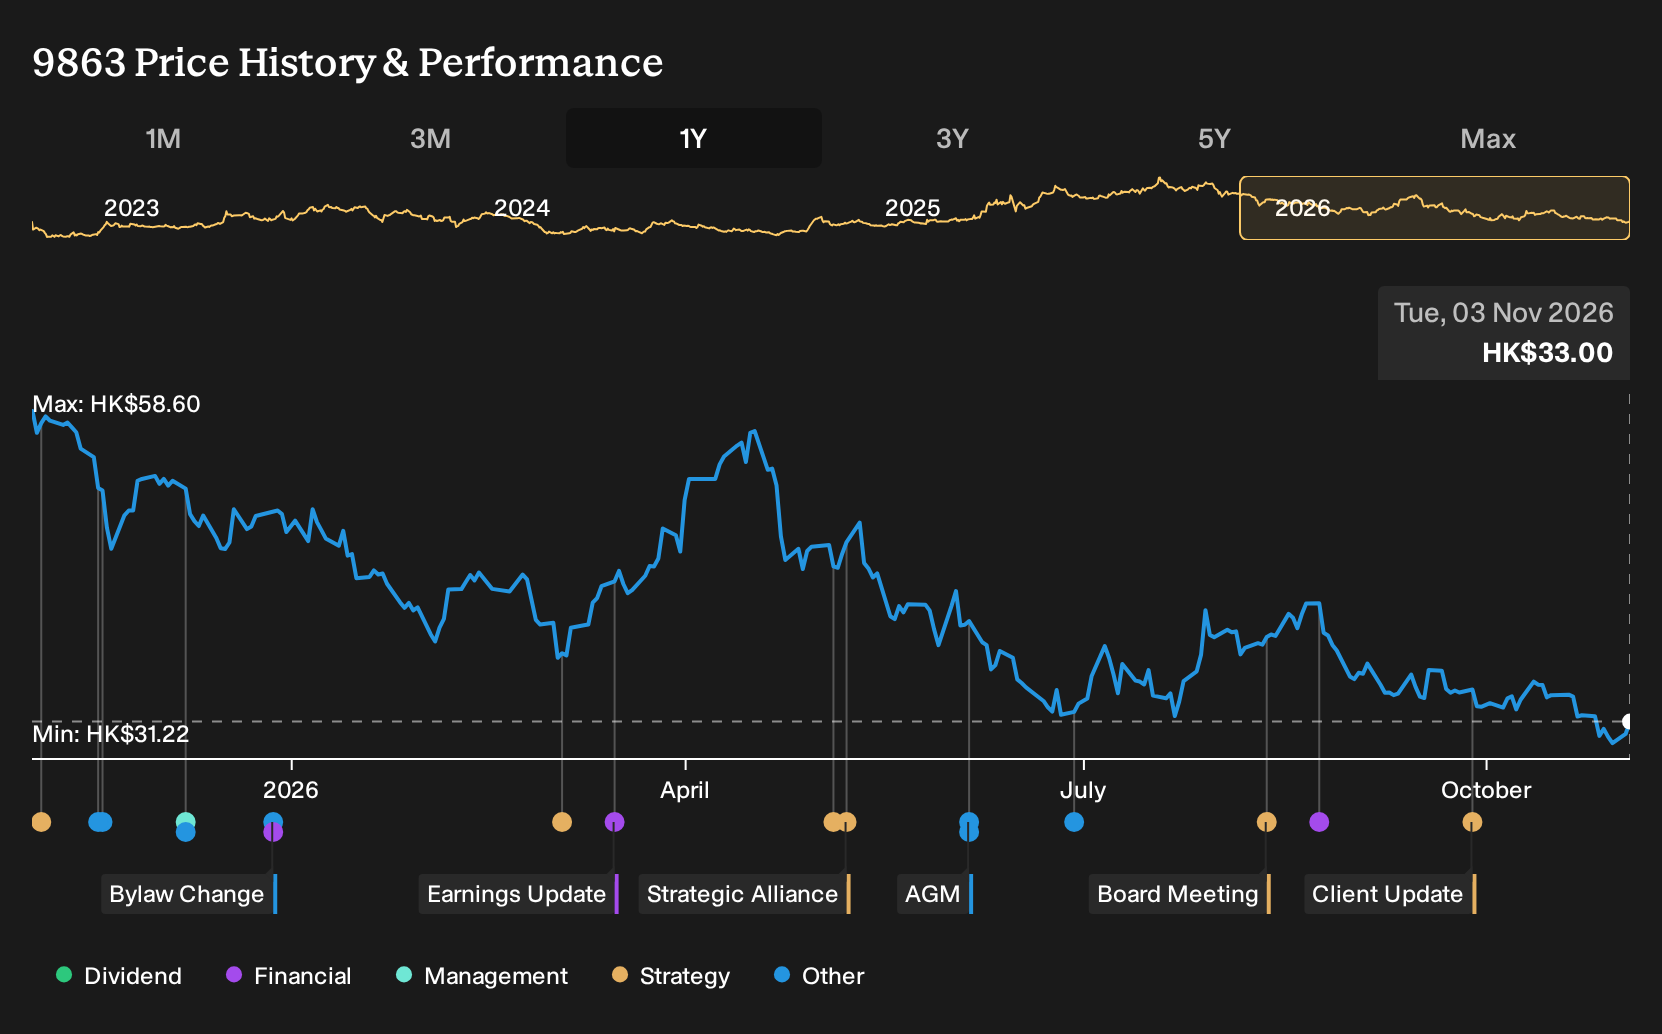
- Zhejiang Leapmotor Technology has experienced a 45.4% share price loss over the past year even as unit sales, revenue and net income all move higher. Management is targeting a 6.0% profit margin that remains out of reach.
- The disconnect between Zhejiang Leapmotor Technology's broader model lineup, overseas push and still thin profitability highlights investor focus on execution quality rather than headline delivery growth.
- We will now examine how Zhejiang Leapmotor Technology's investment narrative is affected by rapid unit growth that still trails profit margin ambitions.
Balance your view on Zhejiang Leapmotor Technology's profitability efforts by exploring other electric vehicle opportunities that combine volume growth with firmer margins in our curated 217 resilient stocks with low risk scores
Zhejiang Leapmotor Technology Investment Narrative Recap
To hold Zhejiang Leapmotor Technology, you need to believe the current gap between rapid volume growth and a still modest profit margin can gradually narrow without sacrificing pricing discipline. The near term story hinges on whether management can push vehicle mix, cost control and overseas operations in a way that moves closer to the 6.0% margin goal.
The biggest swing factor right now is execution on overseas expansion through partners like Stellantis, while sector wide input cost pressure and tariffs remain live risks. The recent share price decline against rising revenue and net income does not materially change that core debate. It simply sharpens attention on profitability quality rather than units alone.
Recent commentary around keeping Leapmotor International margins low in the early years is the announcement that really matters here. It directly intersects with today’s concern that Zhejiang Leapmotor Technology is still some distance from management’s 6.0% profit margin aspiration even as deliveries scale.
For you as a shareholder or potential shareholder, that policy frames both the main catalyst and the main risk. Execution that turns this low margin overseas push into better economies of scale and a richer earnings mix would support the profit story. Prolonged discounting or partner misalignment could instead cap returns on rising unit volumes.
Zhejiang Leapmotor Technology's narrative projects CN¥159.9b revenue and CN¥8.3b earnings by 2029, which analysts link to a 26.7% yearly revenue growth rate and an earnings increase of roughly 11.6x from CN¥713.8m today.
Uncover why Zhejiang Leapmotor Technology's fair value indicates a potential 87% upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on cash generation, not just Zhejiang Leapmotor Technology’s margin target. The most cautious analysts previously expected 3 year revenue growth of around 21.9% and 2029 earnings of approximately CN¥6.1b before this news, painting a tighter story. Their view could shift, so treat it as one of several viewpoints to evaluate for yourself.
Explore 2 other Zhejiang Leapmotor Technology fair value estimates, including one that suggests it could be worth just HK$36.58.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Zhejiang Leapmotor Technology research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Zhejiang Leapmotor Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zhejiang Leapmotor Technology's overall financial health at a glance.
Looking For More Ideas Beyond Zhejiang Leapmotor Technology?
If the Zhejiang Leapmotor Technology story has sharpened your thinking on risk, reward and execution quality, it can help to compare it with other opportunities that fit different profiles. The Simply Wall St Screener lets you filter by balance sheet strength, valuation or income focus so you can build a wider watchlist that matches your own approach.
- If capital preservation is high on your list, start with a 217 resilient stocks with low risk scores that aims to prioritise resilience when markets get choppy.
- If you prefer to anchor decisions in valuation and quality, scan through a 196 high quality undervalued stocks that blend strong fundamentals with more modest pricing.
- If income matters to your plan, shortlist potential payers using a 220 dividend fortresses that focuses on higher yielding options.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com