


- Aisin reported half year results for the period ended September 30, 2026, with sales of JPY 2,653,133 million and net income of JPY 49,667 million, alongside new full year fiscal 2027 guidance and a higher second quarter dividend of JPY 35.00 per share.
- The combination of stronger revenue, lower profit, explicit earnings guidance, and a dividend increase provides a clearer view of how Aisin is balancing reinvestment needs with cash returns to shareholders.
- The focus now turns to how Aisin's updated full year guidance may influence the broader investment narrative around the business.
Compare how Aisin balances earnings guidance with dividends against a curated group of similar opportunities by scanning the 28 dividend fortresses.
What Is Aisin's Investment Narrative?
Aisin’s story hinges on whether you think a global tier one auto supplier can keep funding heavy product spend while living with thinner profitability. The new full year guidance, with revenue of ¥5,250,000 million and profit attributable to owners of ¥135,000 million, signals management is willing to be explicit about near term earnings power. The half year results showed higher sales but weaker net income, so the short term catalyst is really execution, especially around cost control and product mix, rather than a sudden demand swing.
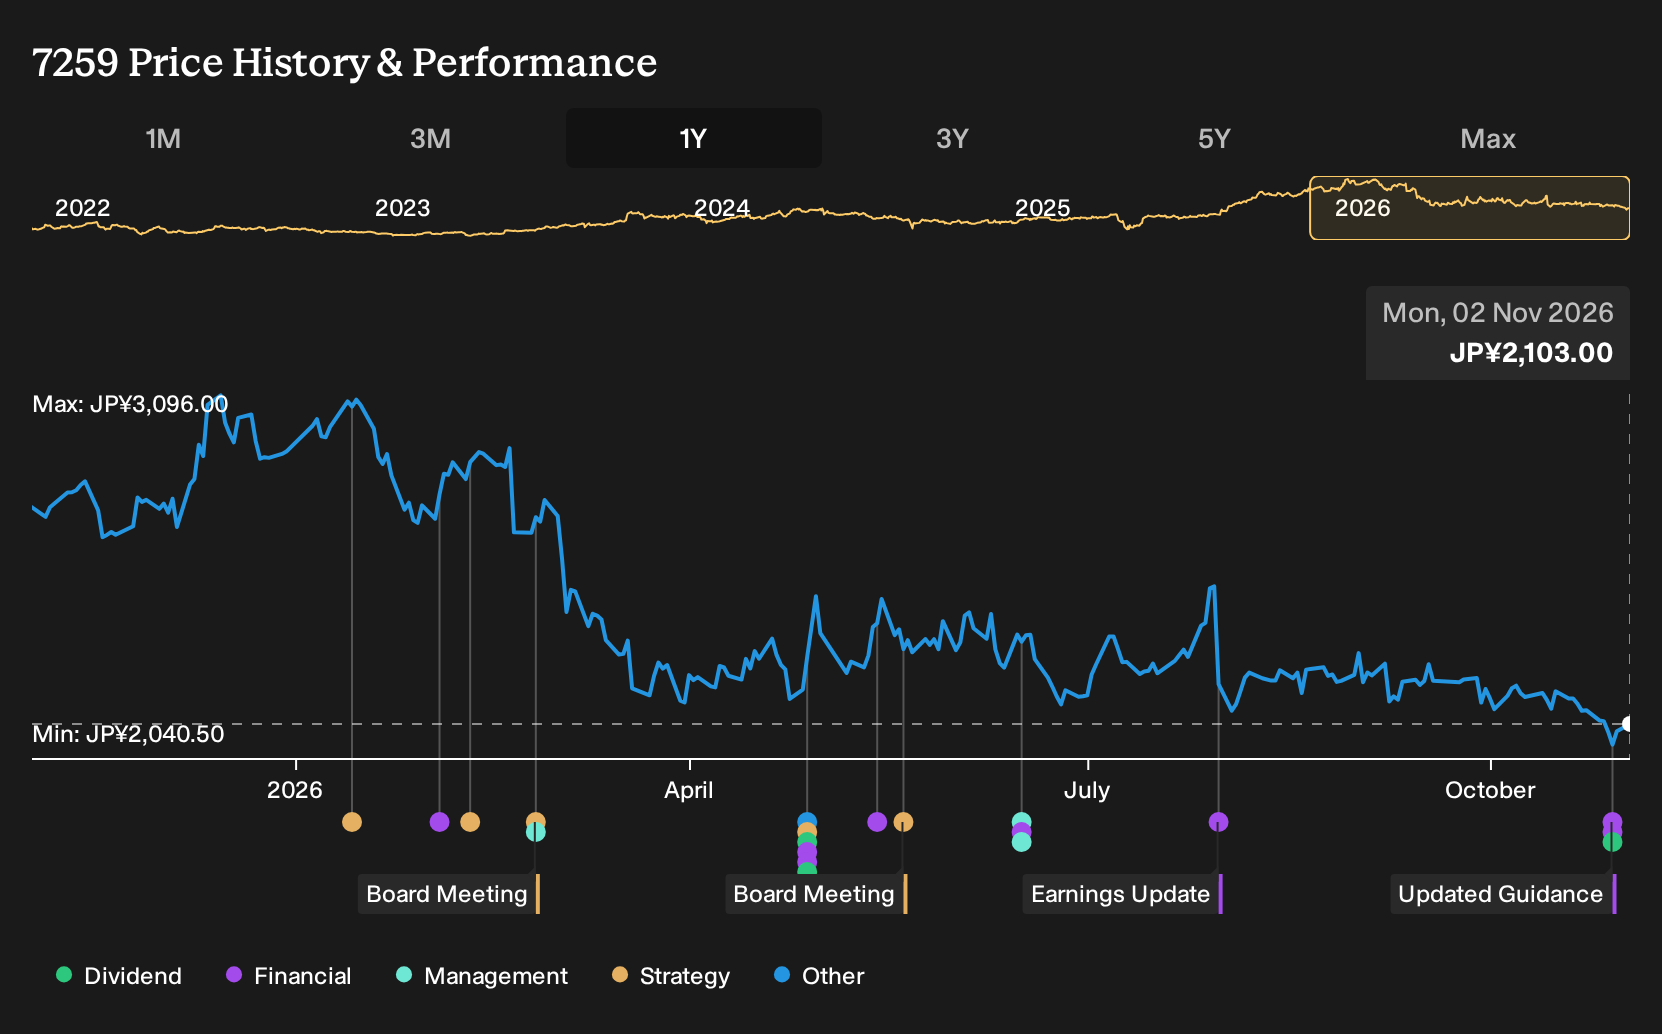
The higher second quarter dividend of ¥35.00 per share, against a past flag for an unstable payout record, indicates that Aisin is leaning a bit harder into shareholder returns even as margins feel pressure. That choice can support sentiment after a share price that has fallen about 30% year to date, although it also tightens the room for error if auto volumes or pricing soften further.
That said, the picture becomes less comfortable once you weigh that dividend stance against ...
There's only one way to know the right time to buy, sell or hold Aisin. Head to Simply Wall St's company report for the latest analysis of Aisin's Fair Value.
Exploring Other Perspectives
Aisin’s fair value range from the Simply Wall St Community runs from about ¥2,615 to ¥5,375 across just 2 shared estimates, so you are looking at a very wide gap in expectations. Those views were formed before the October 29 earnings call and new guidance. As a result, reassessing them now can surface sharply different paths for future performance.
Explore another Aisin fair value estimate, including one that suggests it could be worth just ¥2615!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aisin research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aisin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aisin's overall financial health at a glance.
Looking For More Ideas Beyond Aisin?
If Aisin has sharpened your focus on where earnings power, dividends, and balance sheet strength intersect, it can help to line it up against a wider field of candidates using the Simply Wall St Screener.
- If you want potential value with quality fundamentals, line up contenders using the 17 high quality undervalued stocks to see which stocks currently screen as both financially robust and priced below their assessed worth.
- If capital preservation sits high on your priority list, filter for steadier profiles by scanning the 22 resilient stocks with low risk scores and compare how their risk scores stack against what you see in Aisin.
- If you are hunting for resilient balance sheets, build a shortlist with the list of solid balance sheet and fundamentals (22 results) so you can focus your time on companies that already clear a basic financial strength hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com