


Unity Software (U) just announced a new partnership with PvX that offers eligible growth-stage studios in its ecosystem access to non-dilutive user acquisition financing, pairing PvX’s capital with Unity Vector’s advertising reach and data tools.
Unity Software’s latest PvX tie-up lands as the share price trades at US$40.48, with a 1-day share price return of 4.14% and a 90-day share price return of 14.12%, while the year-to-date share price is down 8.52% and the 1-year total shareholder return sits at 12.85%. This hints at momentum rebuilding after a softer recent month and a still challenging five-year total shareholder return that has declined 76.41%.
Scan beyond Unity Software and this PvX financing push by checking out a curated list of 19 high quality undiscovered gems that could be quietly building similar funding and growth flywheels.
Unity Software now pairs a recovering share price with a fresh PvX funding engine. Is this the moment to accept today’s terms, or does it make more sense to wait for a cheaper entry once the dust settles on valuation?
Most Popular Narrative: 272% Overvalued
Unity Software closed at $40.48, while the most widely followed narrative pegs fair value at $10.88, which frames today’s price as richly valued and puts extra weight on whether the Vector growth story fully holds up.
The business case for Unity is the strongest it has been since the IPO, but at about $43 the stock already prices in a good outcome. My base case lands near today's price, and real upside needs the bull scenario, where Vector keeps growing 30% to 50% a year through 2028.
See why 1 investors see Unity Software as 272% overvalued.
Result: Fair Value of $10.88 (OVERVALUED)
Still, the Unity Software story could flip fast if the AppLovin arbitration strengthens data misuse claims or if Vector growth cools enough to puncture that premium multiple.
Find out about the key risks to this Unity Software narrative.
Another View: Unity Software Through The Cash Flow Lens
The narrative community flags Unity Software as richly priced against a $10.88 fair value, yet the SWS DCF model points the other way. At $40.48, that approach suggests shares trade about 54.5% below an $88.99 future cash flow value, which raises a clear question. Is the market underestimating the durability of Unity’s cash generation story, or are the narrative assumptions simply too cautious?
Look into how the SWS DCF model arrives at its fair value.
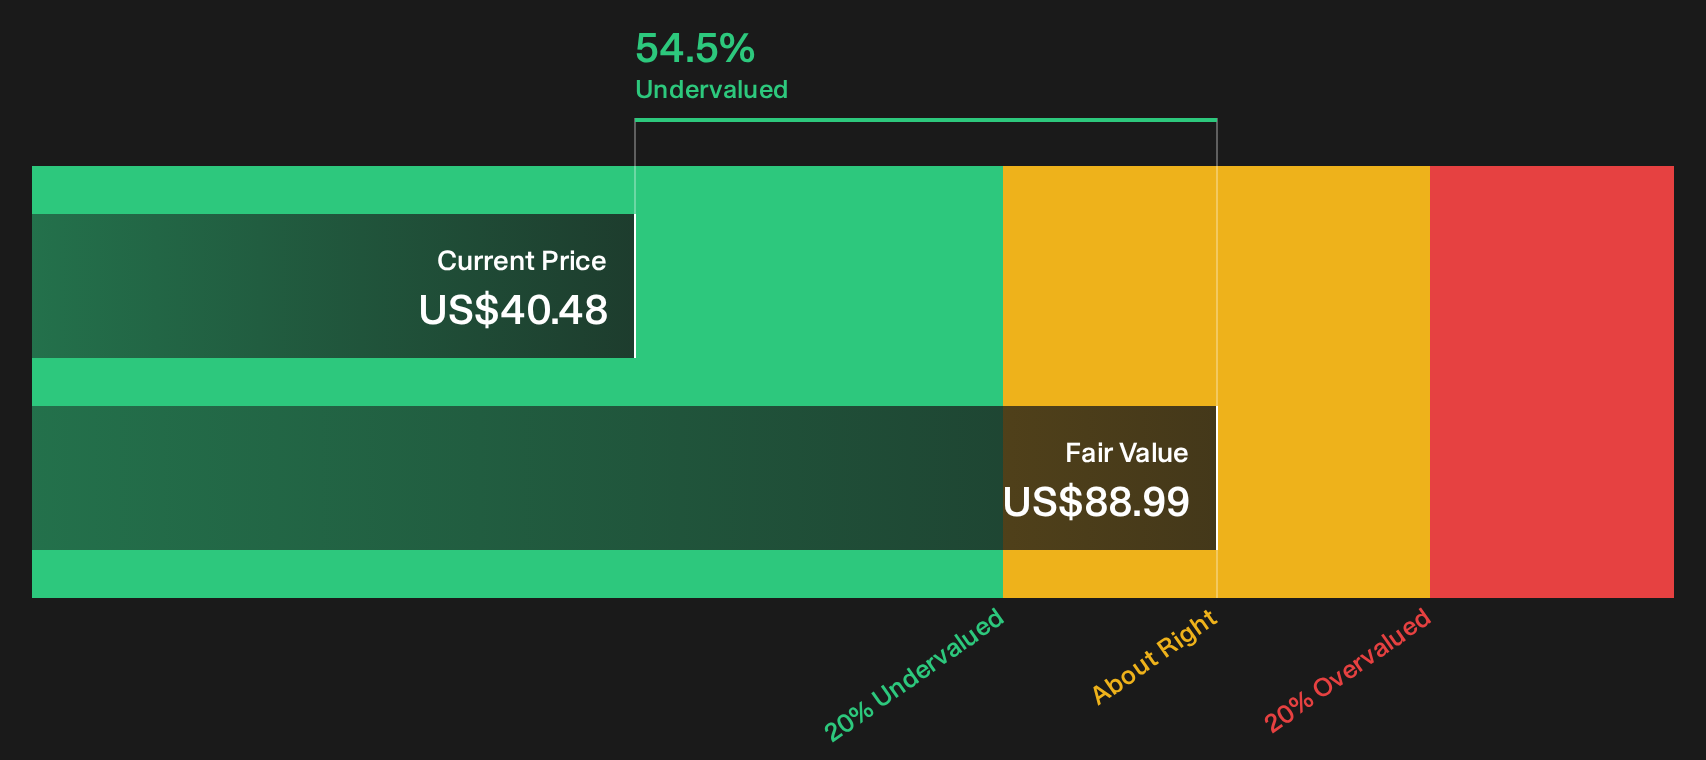
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Unity Software for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Unity Software’s value story. If you want to move fast and build your own conviction from the numbers, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more Unity Software investment ideas?
If Unity Software has put fresh ideas on your radar, do not stop here. Spread your research across sectors and styles so you are not tied to one story.
- Target steadier opportunities by reviewing companies flagged as resilient on quality and risk through the 30 resilient stocks with low risk scores.
- Hunt for potential mispricings by scanning the 34 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- Anchor your watchlist with financially grounded operators by focusing on the list of solid balance sheet and fundamentals (24 results) that can better handle pressure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com