


- RPM International has announced plans to host an Investor Day on November 9, 2026, to outline its MAP 2030 operating improvement program and provide updates on broader business initiatives, with a public webcast available through its investor relations site.
- The focus on MAP 2030 indicates that RPM International management is concentrating on further operating efficiency and execution discipline. This ties directly into previous cost and SG&A programs that have been central to the company's operating model.
- We will now look at how RPM International's investment narrative could be influenced by the MAP 2030 focus at its Investor Day.
RPM International Investment Narrative Recap
To own RPM International, you need to believe management can keep tightening the operating model through its MAP programs while still pushing higher value coatings, sealants and building solutions. The big near term swing factor is whether MAP 2030 can extend earlier cost and SG&A work without hurting service levels or organic demand, especially in more price sensitive channels.
The largest near term risk remains a mix of cost pressure and uneven end market demand. Raw material inflation, health care expenses and ongoing consumer volume softness have all been highlighted as headwinds. If those stay heavy while MAP savings arrive more slowly than hoped, margin progress could stall. The Investor Day does not materially change that risk balance on its own.
The upcoming Investor Day built around MAP 2030 is the key fresh disclosure for RPM International. Management plans to walk through the next phase of operating improvement and broader business initiatives. That update matters because previous MAP efforts and SG&A programs are central to how the group has been lifting efficiency and funding reinvestment.
For catalysts, investors are watching whether MAP 2030 can reinforce efforts already under way, such as system selling in high performance buildings, SG&A optimization expected to support fiscal 2027, and continued reinvestment of operating cash flow into acquisitions and growth capex. Execution details from the event should help you judge how realistic those operational and earnings efficiency goals look against the known risks around debt levels, funding mix and cost inflation.
RPM International's narrative projects US$8.9b revenue and US$969.4m earnings by 2029. That profile lines up with analysts penciling in 3.9% yearly revenue growth and an earnings increase of about US$281.9m from the current US$687.5m base.
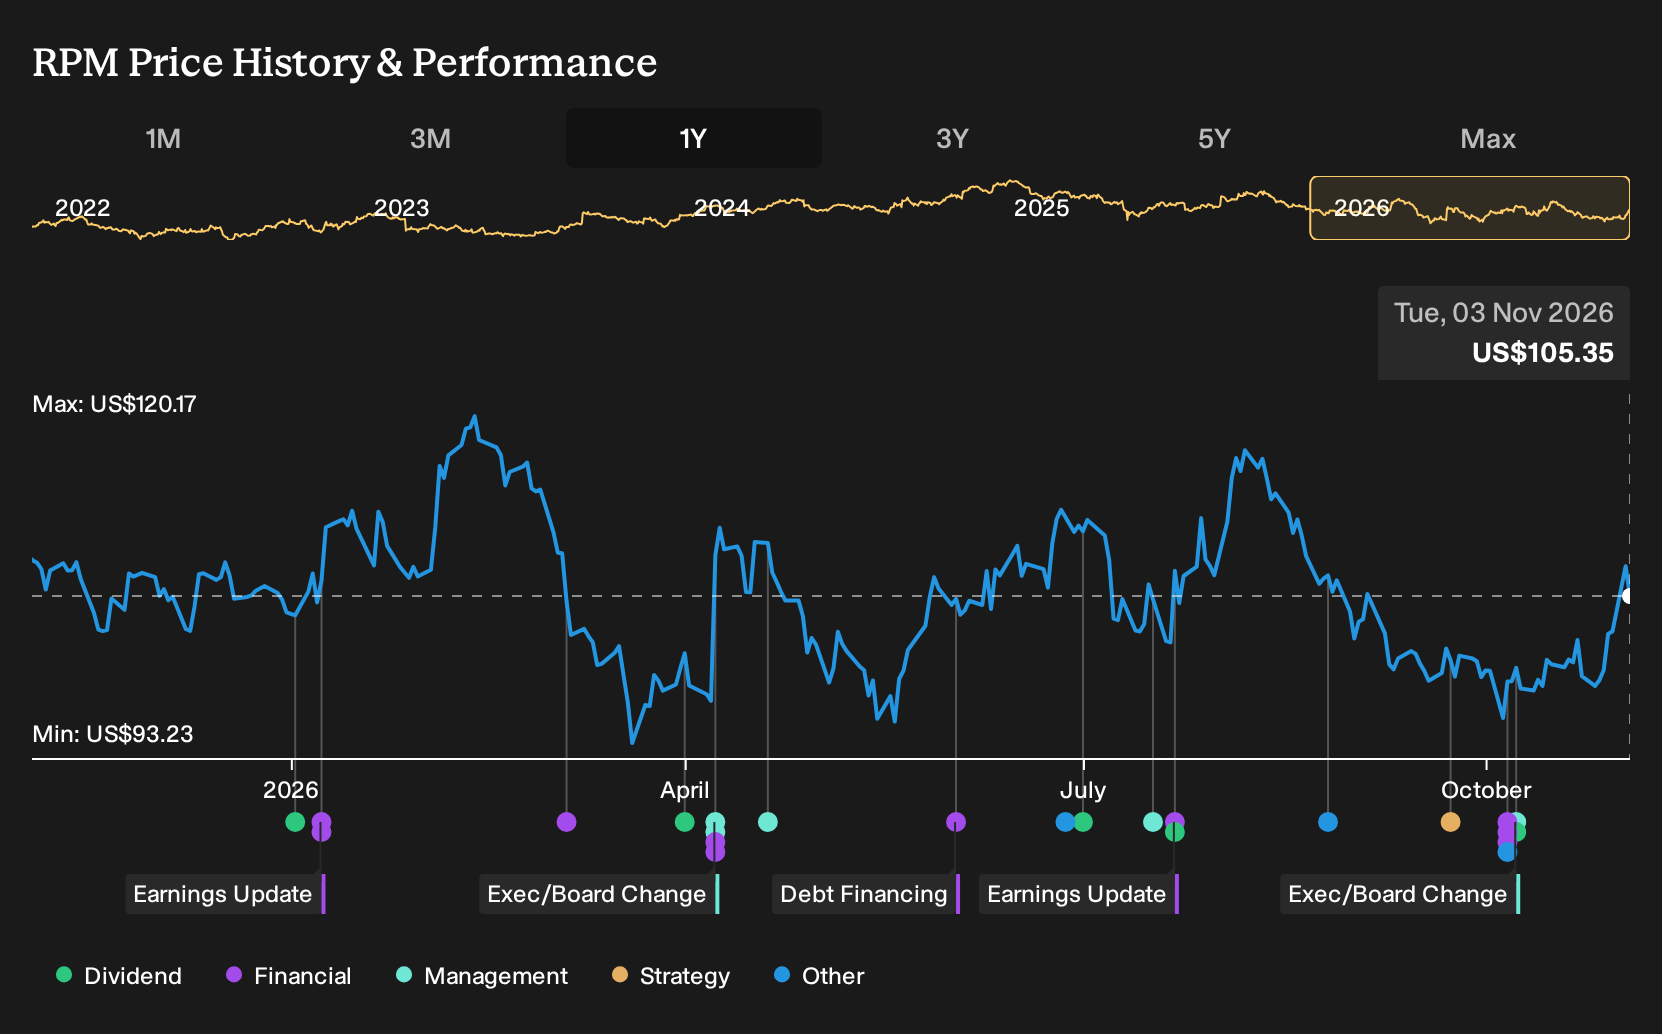
Uncover why RPM International's fair value indicates a 17% potential upside to its current price, a discount RPM International investors may see close sooner than expected.
Exploring Other Perspectives
Some of the lowest RPM International forecasts lean hard into raw material and health care cost risk. Those analysts were only looking for about US$8.7b of revenue and US$938.0m of earnings by 2029, compared with the higher consensus figures. With MAP 2030 now in focus, those more cautious views may evolve once fresh detail lands at Investor Day.
Explore 4 other RPM International fair value estimates, including one that suggests it could be worth just $107.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your RPM International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RPM International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RPM International's overall financial health at a glance.
Looking For More Investment Ideas Beyond RPM International?
Once you have a view on RPM International, it can help to compare it with a wider watchlist of businesses that fit different risk and return profiles. The Simply Wall St Screener lets you quickly filter for qualities that match how you like to invest.
- If you care most about resilient balance sheets and steady fundamentals, start with a curated list of solid balance sheet and fundamentals (24 results) that screens for financial strength first.
- For investors hunting for value opportunities supported by quality metrics, scan a focused 34 high quality undervalued stocks that can surface candidates trading at a discount to their fundamentals.
- If dependable income is high on your checklist, review a targeted 4 dividend fortresses that filters for higher yield potential with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com