


- IPG Photonics reported third quarter 2026 sales of US$287.5 million and net income of US$20.27 million, with both basic and diluted EPS from continuing operations above the prior year period.
- The nine month figures show higher sales and net income than a year earlier, which reflects changes in operating efficiency and earnings contribution from the broader IPG Photonics portfolio.
- We will now look at how this third quarter profit picture may influence IPG Photonics' investment narrative from here.
Scan beyond IPG Photonics and size up other potential beneficiaries of the same industrial and automation themes by reviewing our curated list of 94 robotics and automation stocks that are already on the move.
IPG Photonics Investment Narrative Recap
To own IPG Photonics, you really need to believe the shift toward higher value welding, cleaning, medical, and defense systems can translate into steadier earnings over time. The latest quarter, with US$287.5 million of sales and US$20.27 million of net income, supports the idea that margin repair and mix improvement are gaining some traction.
The near term swing factor remains execution on that margin recovery and on ramping newer applications fast enough to offset past revenue volatility. The biggest risk is that the recent profitability proves patchy, especially in Advanced Solutions, which could leave earnings choppy just as investment and expectations stay elevated.
The fresh earnings release for the third quarter and the nine month period to September 30, 2026 sits alongside those earlier expectations that IPG Photonics could broaden growth across automation, EV, medical, and defense uses. Revenue of US$831.58 million and net income of US$27.1 million for the year to date provide a clearer baseline for assessing that thesis.
Relative to earlier commentary that highlighted margin recovery, the higher basic EPS from continuing operations, at US$0.48 for the quarter and US$0.64 for nine months, speaks directly to the key catalyst, which is improved profitability from the existing revenue base. It also sharpens the risk that any reversal in pricing, cost control, or demand mix would quickly show up in earnings per share.
IPG Photonics' analyst narrative points to revenues of US$1.5b and earnings of US$171.0 million by 2029, built on assumed 10.8% yearly top line growth and an earnings increase of about US$143 million from current earnings of US$27.6 million.
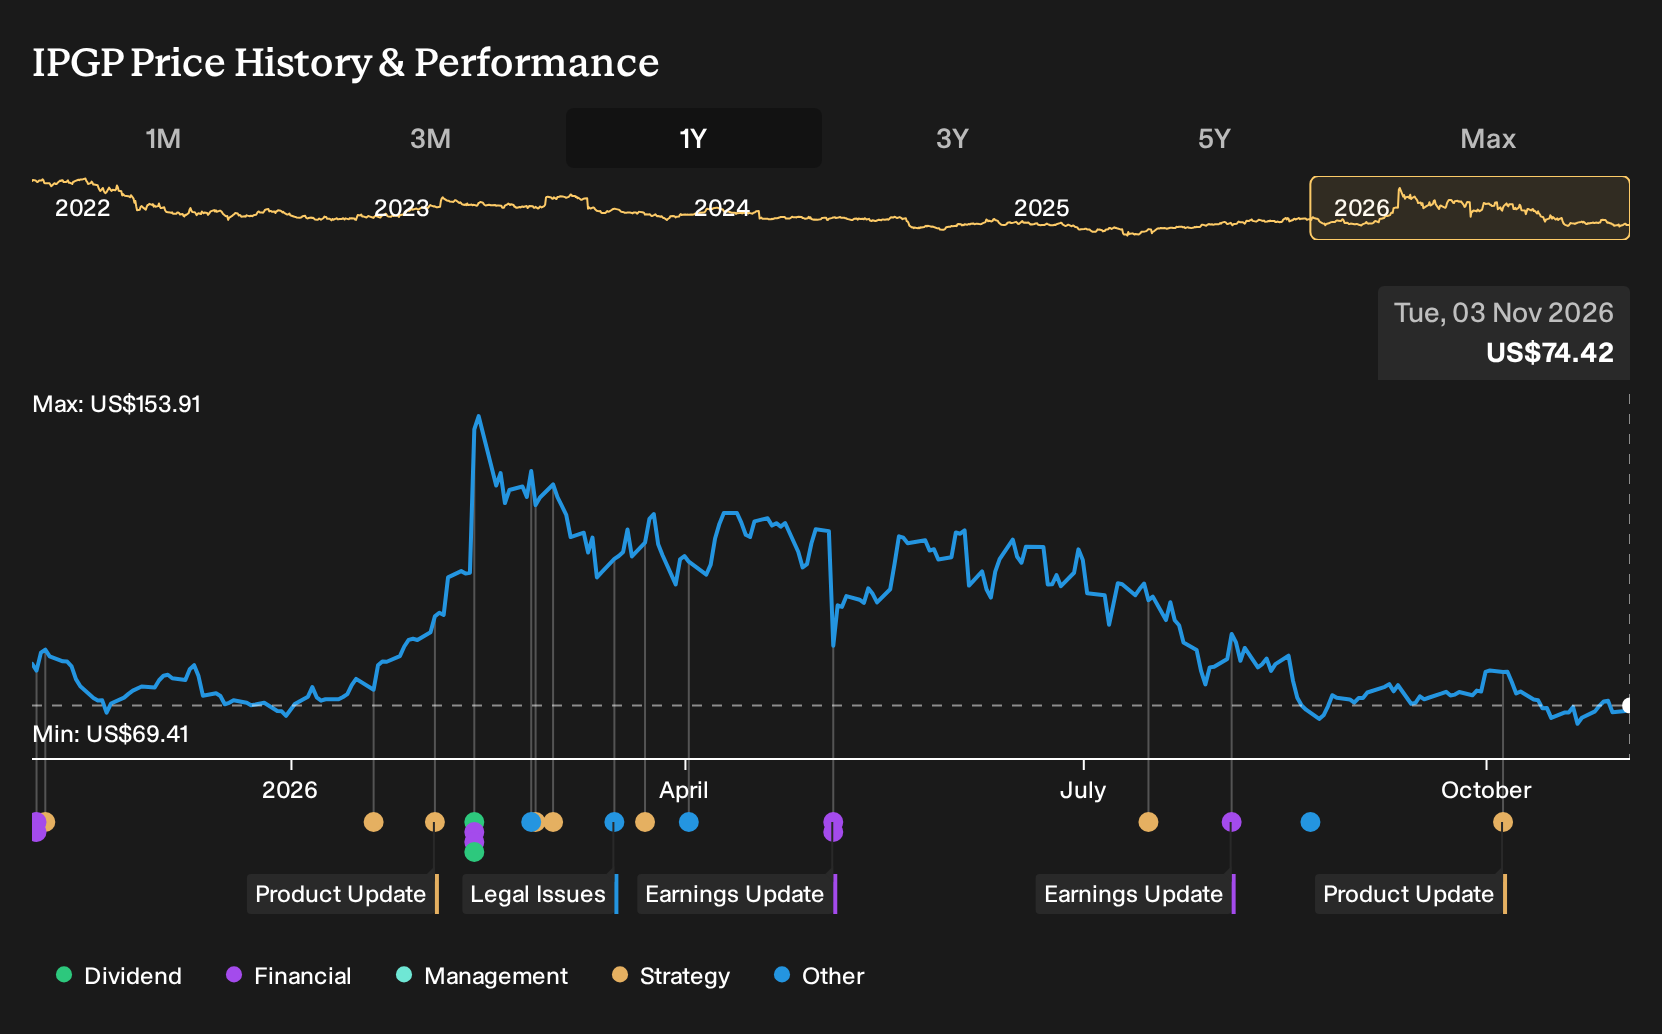
Uncover why IPG Photonics' fair value indicates a 67% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate read on IPG Photonics leans hard into the bullish catalyst of medical and battery related lasers. That camp was modelling revenue of about US$1.6b and earnings near US$176.1 million by 2029 before this latest report. If you are curious how far that optimism goes, compare it with more cautious forecasts and see which story fits your view after the new numbers.
Explore 3 other IPG Photonics fair value estimates, including one that suggests as much as 67% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your IPG Photonics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for IPG Photonics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IPG Photonics' overall financial health at a glance.
Looking for more IPG Photonics style investment ideas?
If IPG Photonics has sharpened your interest in focused, thesis driven opportunities, widen the lens and use the Simply Wall St Screener to build a watchlist that matches your risk tolerance and return goals.
- For investors who want quality at a marked down price, start with a 34 high quality undervalued stocks that combines solid fundamentals with more reasonable valuations.
- If capital preservation matters just as much as upside, you may prefer a 30 resilient stocks with low risk scores that scores well on balance sheet strength and earnings stability.
- Those hunting for lesser known opportunities with robust financials can scan a 19 high quality undiscovered gems that have not yet drawn broad market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com