


Camtek (NasdaqGM:CAMT) heads into its Q3 2026 earnings release and call today, with investors focused on a different catalyst: Morgan Stanley’s recent downgrade tied to competition in 2D chip inspection.
Camtek’s recent share price swings reflect that tension. The stock has fallen 32.05% on a 30 day share price return and 23.95% on a 90 day share price return. However, the 3 year total shareholder return of 103.63% and 5 year total shareholder return of 152.81% still point to a much stronger longer term story than the current pullback suggests.
Scan beyond Camtek and stress test your thesis against a curated set of 53 AI infrastructure stocks facing similar tailwinds in chip demand as well as potential pressure points in inspection and metrology.
Camtek now trades well below the average analyst target after a sharp pullback, yet fresh doubts around 2D inspection and services ambitions linger. Is that gap a genuine margin of safety or a warning sign?
Most Popular Narrative: 34% Undervalued
Camtek closed at $112.25 while the most followed narrative anchors fair value at $170.20. The debate is whether the current discount properly reflects execution risk in AI driven advanced packaging and HBM orders.
Accelerating AI and high performance computing demand is feeding through to advanced packaging and HBM orders for Camtek, with roughly 80% of more than US$600 million of 2026 year to date orders tied to these applications and scheduled for delivery through 2026 and into 2027, which can support multi year revenue growth.
See why 34 investors see Camtek as 34% undervalued.
The most widely referenced narrative applies a 14.82% discount rate and still arrives at that $170.20 fair value, even after trimming the estimate from $176.20 as competition concerns and richer pricing have crept in. Analysts inside that narrative framework are assuming revenue growth of 26.2% a year and a profit margin profile reaching 69.0%, which explains why they are comfortable with a future P/E of 18.05x against today’s much higher multiple.
Those same assumptions also build to earnings of $706.2m by about November 2029, compared with $37.7m today, and imply that the current gap to the consensus target only closes if Camtek keeps converting its more than $600m of 2026 year to date orders into shipments while holding the margin line. Readers can stress test that story against the trimmed fair value, the slightly higher discount rate, and the updated growth and profitability assumptions to judge whether that 34% discount looks like mispricing or simply a demanding bar.
Result: Fair Value of $170.20 (UNDERVALUED)
Still, Camtek’s heavy reliance on AI linked HBM orders and rising competition from China could quickly challenge that 34% undervalued narrative if customer spending or pricing shifts.
Find out about the key risks to this Camtek narrative.
Another View: Camtek On Rich Earnings Multiples
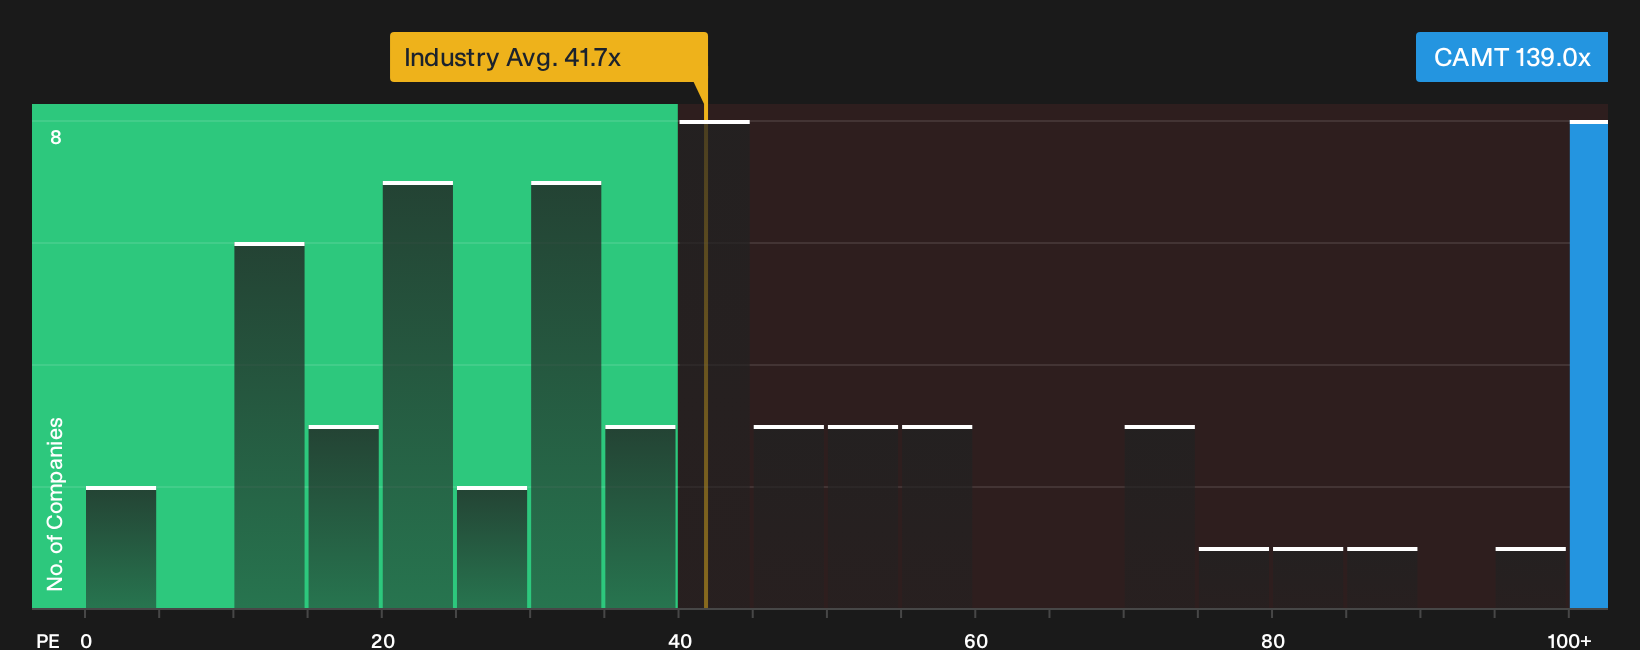
The first narrative leans on ambitious growth and margin forecasts for Camtek. A simple earnings multiple check indicates a very different picture. The stock trades on a P/E of 139x, compared with 41.7x for the US Semiconductor industry and a fair ratio of 77.3x, which suggests that many factors would need to align for that premium to remain justified. Does that resemble a safety buffer or a thin margin for error?
For investors cross checking these signals, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Camtek can feel messy. Move quickly past the headlines and test the story against the underlying numbers and assumptions yourself. To weigh both sides of the debate, review the 2 key rewards and 3 important warning signs.
Looking for more Camtek investment ideas?
Do not stop with a single ticker. Use the Simply Wall Street Screener to compare Camtek with other ideas and keep fresh opportunities on your radar.
- Target potential upside by lining up Camtek against a 34 high quality undervalued stocks that combine quality fundamentals with prices below estimated worth.
- Prioritise resilience by comparing Camtek to a 30 resilient stocks with low risk scores that focus on sturdier balance sheets and more stable business profiles.
- Hunt for earlier stage opportunities alongside Camtek with a 10 elite penny stocks with strong financials that already show stronger financial footing than most tiny caps.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com