


Marqeta has seen its stock reshaped over the past few years, which puts a fresh spotlight on whether the current US$17.80 share price lines up with what the business is generating in sales. For anyone looking at payment infrastructure plays, the key issue is how much revenue power this platform really supports at today's valuation.
- Over the past 5 years the share price has fallen 83.2%, which puts a lot of weight on whether the present valuation can still be explained by its sales base.
- The business model leans heavily on processing volumes and commercial partnerships, so future sales potential and the cost to support that growth can shape what investors are willing to pay for each dollar of revenue.
- The analysts covering Marqeta have run their own numbers. See what analysts think Marqeta's shares could be worth.
The stock's next move may depend on whether the current price can be squared with what Marqeta is generating in sales today and what that revenue line may reasonably support over time.
If you want to stress test the same sales based valuation question that hangs over Marqeta against a wider set of payment and fintech stocks, scan 34 high quality undervalued stocks.
Has Marqeta Run Too Far on Sales?
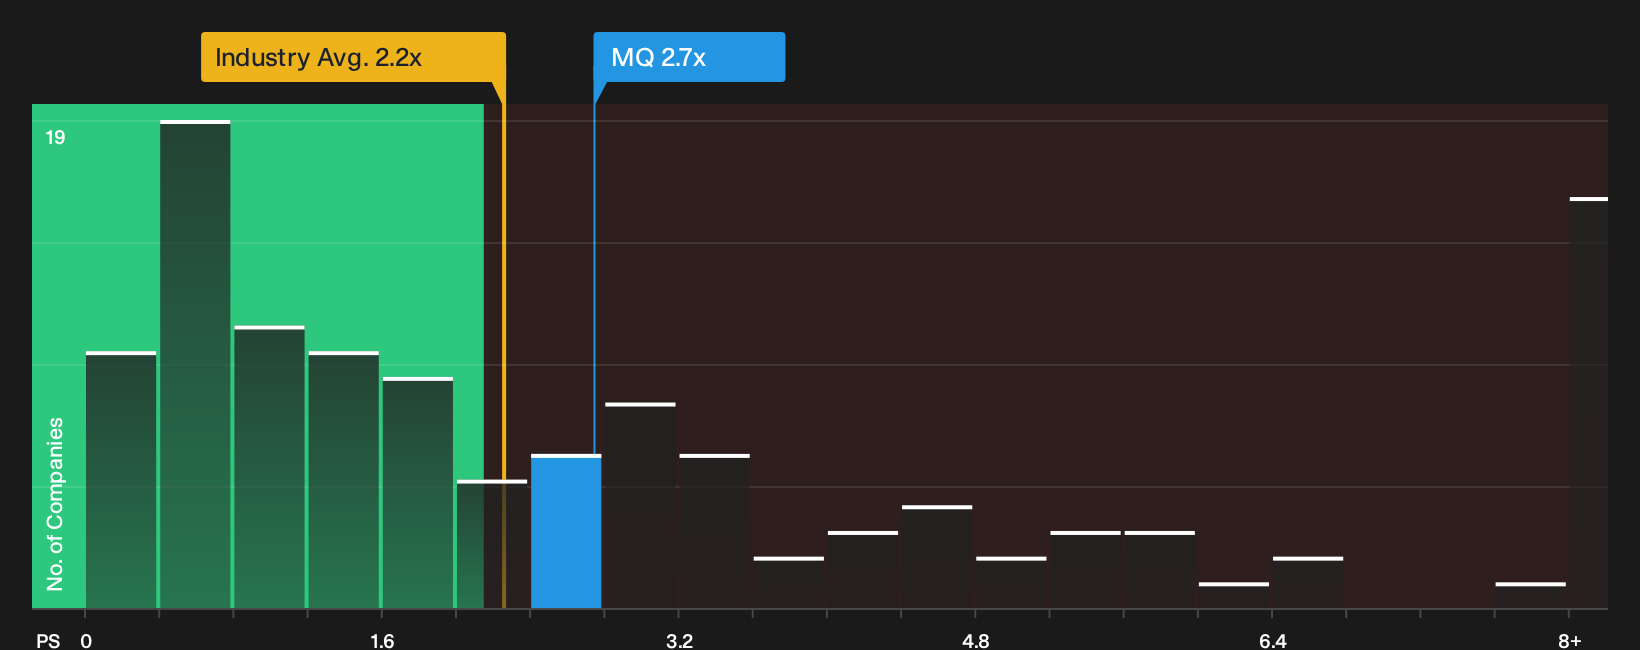
P/S fits Marqeta because investors often focus on what each dollar of payment volume can translate into for the top line. On this yardstick, the stock trades on a P/S of 2.7x, which is above both the diversified financials industry average of 2.2x and the peer group on 0.9x.
The modelled fair P/S ratio suggests a level that is lower than where Marqeta is currently changing hands, so the shares screen as overvalued on this framework. That reflects a market price that gives the business a richer tag per dollar of revenue than the tailored benchmark implies, and it leaves you weighing whether Marqeta’s platform strength and commercial relationships justify paying that premium or whether expectations have moved ahead of what present sales can support. Explore the numbers behind Marqeta's P/S valuation.
The Marqeta Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Marqeta's P/S puzzle leaves off. They spell out the combinations of future growth, profitability and earnings power that would need to play out for the stock to be worth materially more or less than today’s market value. Instead of giving a single output, they unpack the expectations behind it so you can watch whether those assumptions still match what the business is actually delivering on the Community page.
Community views on Marqeta are split between those who see more upside left in the current model and those who think the upside is already largely priced in.
Bull case: 14% undervalued
"Rising demand from large enterprises and financial institutions for embedded finance programs, reflected in average deal size growing more than 90% year over year..."
Discover why this Narrative puts Marqeta at 14% undervalued.
Bear case: roughly fairly valued
"The sequential and year over year decline in gross profit take rate tied to larger customers and lower economics segments suggests that a mix shift toward multinational issuers and on demand delivery could cap future net revenue per dollar of volume..."
Explore why this Narrative puts Marqeta at roughly fairly valued.
One more piece of the Marqeta puzzle before you move on
Price to sales tells you what people are paying for Marqeta today, but analyst models sketch out where they think this business could be a few years down the road. Explore where analysts expect Marqeta to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com