


CarMax (KMX) has put its new Shift into GEAR plan at center stage, outlining a multi-year roadmap focused on earnings growth targets, cost efficiency goals and a more integrated used-car retail experience.
Recent price action has been choppy. The share price fell 5.39% on the day to US$53.38 and is down 5.81% over the past 90 days. However, the year-to-date share price return of 35.86% and 1-year total shareholder return of 30.99% still mark a strong rebound against weaker 3 and 5 year total shareholder returns. This suggests that enthusiasm around CarMax’s Shift into GEAR plan is being tempered by changing views on execution risk and longer term cyclicality.
Scan for other used-car and retail auto plays showing similar execution stories by reviewing the hand picked 19 high quality undiscovered gems alongside CarMax's Shift into GEAR plan.
Bulls point to CarMax’s efficiency metrics and fresh "Shift into GEAR" roadmap, while bears focus on the weak multi year return record and execution risk. Which side does the current valuation lean toward?
Most Popular Narrative: 1% Undervalued
CarMax’s most followed narrative pegs fair value at $54.09, just above the last close at $53.38. This frames the current Shift into GEAR story as a low-margin valuation gap rather than a deep discount or clear premium, according to LunaRodas.
TheGapReport: CarMax, Inc. (NYSE:KMX) Q2 2027 (jun 17 - sep 29) CarMax reports fiscal second-quarter 2027 results, with used comps at 13%, up from a 0.8% decline the quarter before, and a full-year guide that still has gross profit per used unit falling by less than $200. The line worth reading sits beneath both numbers: the June pledge to fund lower prices through efficiency rather than margin now surfaces mainly in analyst answers, with a fiscal 2028 date, a softer verb, and two more quarters of lower margin in front of it.
See why 1 investors see CarMax as 1% undervalued.
Result: Fair Value of $54.09 (ABOUT RIGHT)
Still, the CarMax story could be knocked off course if cost cuts underdeliver or FTC driven tailwinds fade faster than management expects.
Find out about the key risks to this CarMax narrative.
Another View: CarMax Looks Expensive On Earnings
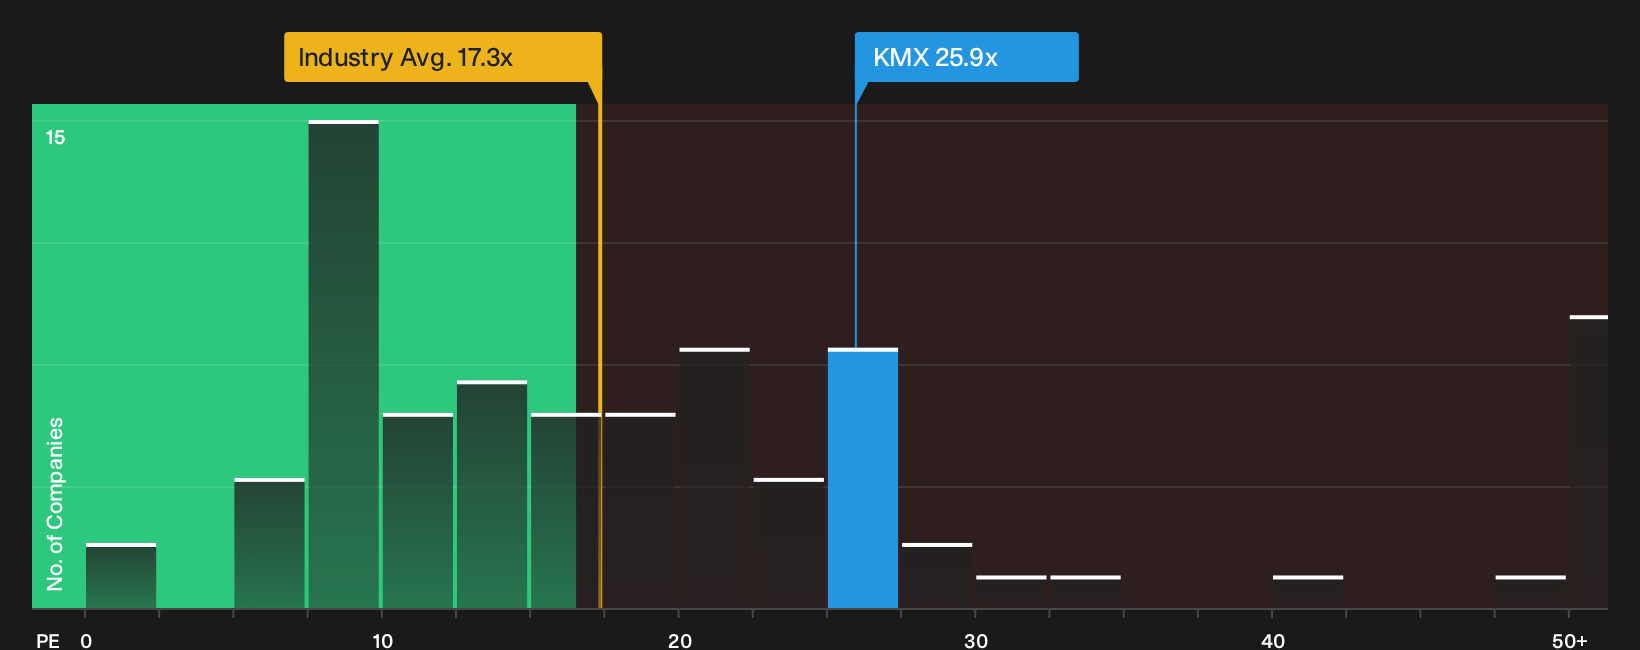
That 1% undervalued fair value narrative clashes with what the earnings multiple is saying. CarMax trades on a P/E of 25.9x, compared with 18.1x for the US Specialty Retail group and 11.4x for direct peers, while the fair ratio sits at 22.7x.
This gap means investors are already paying a premium for KMX despite weaker multi year earnings trends and a 1% net margin. The question is whether forecast 21.7% annual profit growth justifies that premium or leaves little room if the Shift into GEAR plan stumbles.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on CarMax's valuation story so far. If you want to move fast and build your own view off the data, start with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond CarMax?
If CarMax has sharpened your focus on execution stories and valuation tension, let the data guide you toward other opportunities that fit your checklist quickly.
- Target steady cash generators by reviewing the 35 high quality undervalued stocks that combine quality fundamentals with prices that still look reasonable on the numbers.
- Protect your downside first and explore the 30 resilient stocks with low risk scores that is built around resilient balance sheets and more defensive business profiles.
- Look for ideas outside the spotlight by scanning the 19 high quality undiscovered gems where solid financials meet thinner coverage and fewer eyes on the story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com