


Recent headlines around a potential breakup are landing on a stock that has already seen a sharp reset and partial recovery. CVS Health’s share price has a year to date return of 14.08% to US$91.41, while the 1 year total shareholder return is 20.67%, and the 3 year total shareholder return is 45.70%. This points to momentum that has cooled over the past quarter, despite the latest 1 day share price return of 3.28% and 30 day share price return of 5.73%, as investors reassess both the risks and potential benefits of separating the retail, insurance and health services arms.
Spot potential breakups, rebounds, or under-the-radar healthcare peers to compare with CVS Health by scanning our curated 35 high quality undervalued stocks.For CVS Health, after this sharp reset and partial rebound, the practical question is simple: Do you lean into the current price or wait for a clearer discount before stepping in, based on what the valuation says next?
Most Popular Narrative: 26% Undervalued
According to the most followed valuation narrative for CVS Health, a fair value of $124 sits well above the recent $91.41 close, which frames the breakup chatter against a story that already assumes meaningful upside in the core business.
CVS Health is no longer the broken Aetna plus drugstore story the market used for most of 2024 and 2025. Through the first half of 2026 the company has raised full-year guidance twice, Aetna’s medical benefit ratio has improved, cash flow is running well ahead of plan, and all three operating segments are growing. The stock still trades as if the insurance rebuild is temporary and the PBM is about to be regulated into irrelevance.
See why 4 investors see CVS Health as 26% undervalued.
The author of this narrative, Andrei_Niculescu, arrives at a fair value of $124 per share using an estimate of about $8.00 of 2026 earnings and a 15.5x multiple, which leaves a discount of roughly 26% versus that anchor. This view prices CVS Health as a diversified healthcare platform with Aetna, Health Services and Pharmacy & Consumer Wellness all contributing, rather than as a single line insurance recovery story.
Within that framework, the potential separation of retail pharmacies from the insurance and health services units becomes one more test of whether the integrated model is being mispriced or whether investors are correct to assign a lower valuation to a complex structure with moving regulatory parts. Either way, the fair value estimate of $124 is based on earnings power and cash generation already visible in the guidance, not on unproven benefits from any breakup scenario.
Result: Fair Value of $124 (UNDERVALUED)
Still, this hinges on Aetna keeping its medical costs in check and on pharmacy benefit reforms not compressing CVS Health’s Health Services margins faster than expected.
Find out about the key risks to this CVS Health narrative.
Another View: CVS Health Through The P/E Lens
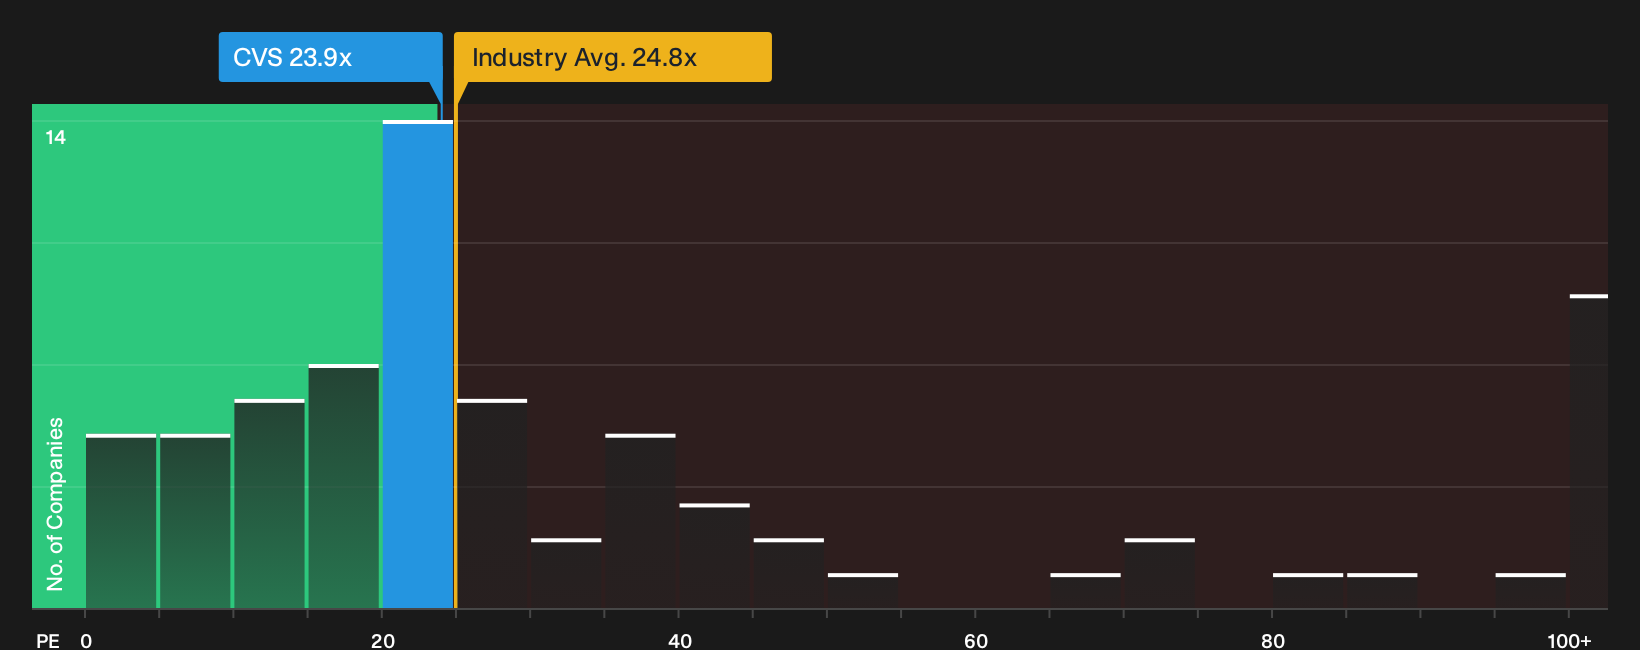
The $124 fair value story leans on earnings power and a mid teens multiple. A quick cross check using CVS Health’s current 23.9x P/E tells a different story. The stock trades richer than its peer average of 19.4x, yet below a 37.4x fair ratio that our model suggests the market could eventually move toward. That gap points to meaningful upside if sentiment improves, but also to real downside risk if the market decides to pull CVS Health back closer to peer levels instead of rewarding it with that higher fair ratio. Which side of that spread do you want your portfolio exposed to when the next big headline hits?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
This mix of optimism and concern around CVS Health only matters if you turn it into your own judgment. Move quickly, review the key metrics, and weigh the 4 key rewards and 2 important warning signs.
Looking for more ideas beyond CVS Health?
Do not stop with one ticker. Use the Simply Wall St Screener to surface fresh opportunities that fit how you like to build a portfolio.
- Target potential mispricings by scanning a curated pool of quality candidates through the 35 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that appear in the 4 dividend fortresses.
- Dial down portfolio stress by focusing on resilient businesses highlighted in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com