


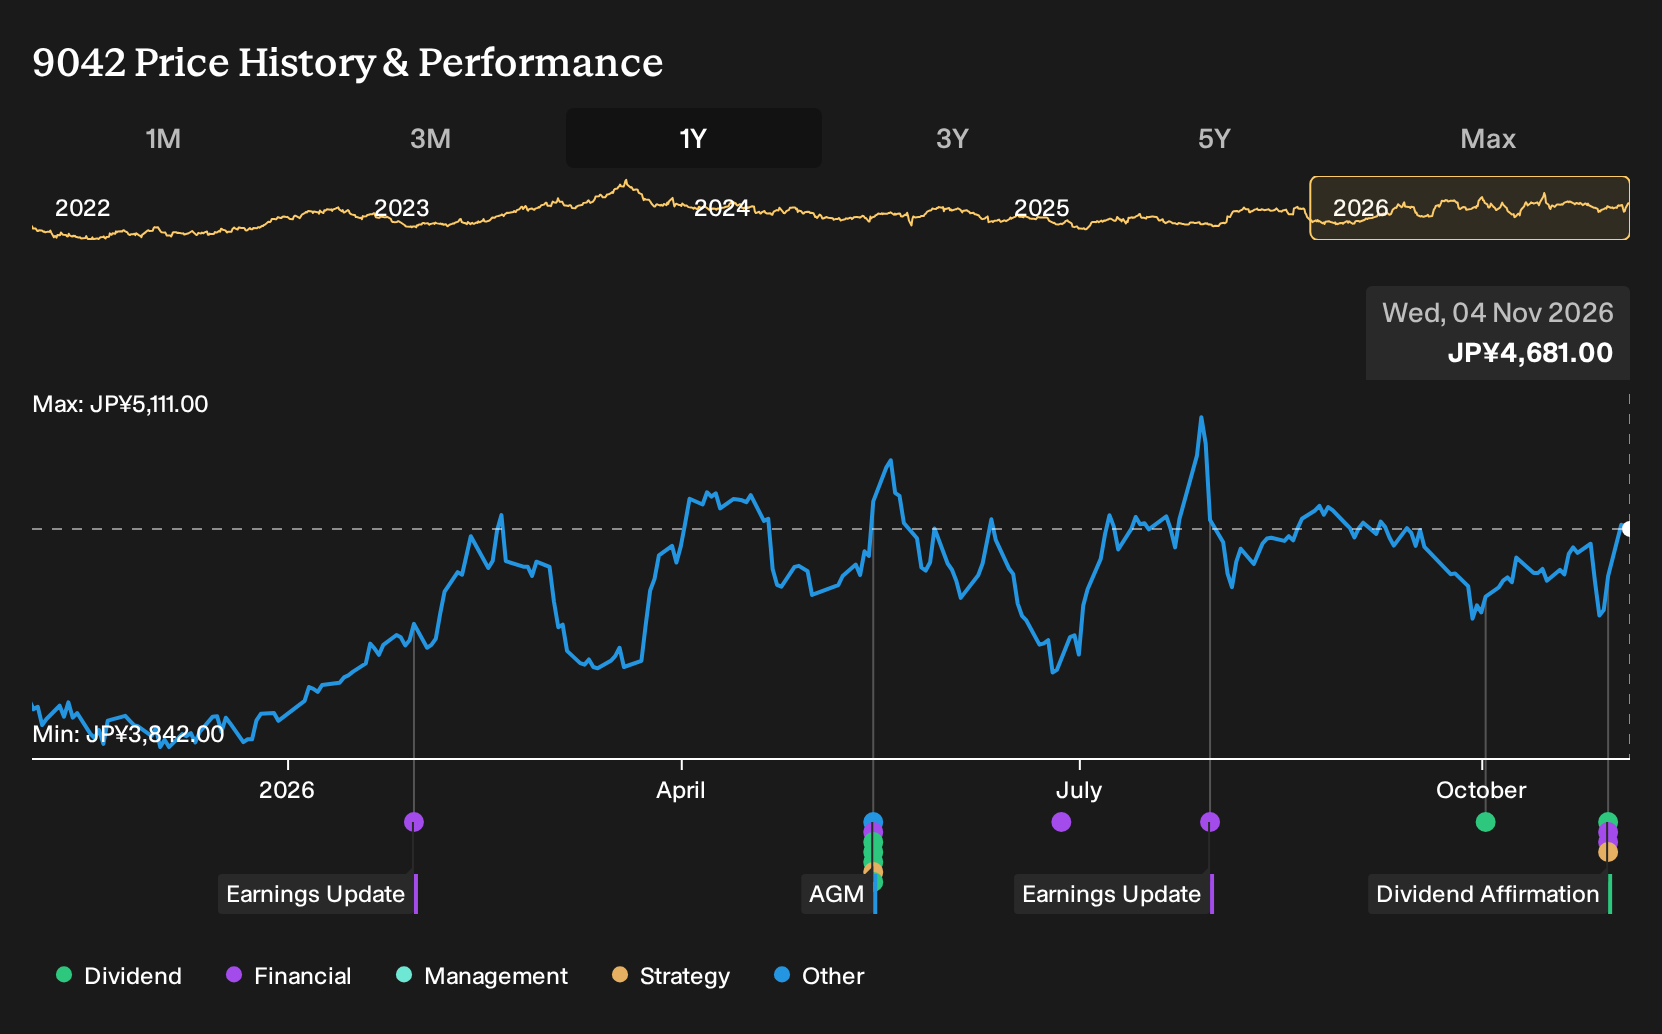
- Hankyu Hanshin Holdings reported half year sales of ¥641,454 million and profit attributable to owners of parent of ¥52,562 million, issued earnings per share figures for continuing operations, reaffirmed dividends of ¥50 per share at mid year and year end, and set full year revenue and profit guidance for the period to March 2027.
- The combination of fresh earnings data, explicit full year profit and earnings per share targets, and confirmed dividend plans gives investors a clearer picture of Hankyu Hanshin Holdings’ current business momentum, capital allocation stance, and management’s confidence level in the operating outlook.
- The focus now turns to how Hankyu Hanshin Holdings’ investment narrative lines up with this new earnings guidance and dividend confirmation.
Compare Hankyu Hanshin Holdings’ latest guidance, dividends, and completed buyback with a curated 18 high quality undervalued stocks that also pair shareholder returns with solid fundamentals.
What Is Hankyu Hanshin Holdings' Investment Narrative?
To own Hankyu Hanshin Holdings, you need to be comfortable with a steady, capital intensive urban ecosystem rather than a fast growth story. Rail, real estate, hotels and entertainment all demand ongoing investment, so execution on pricing, occupancy and passenger volumes matters more than big headline expansion. The fresh guidance for ¥1,260,000 million in operating revenues and ¥90,000 million in profit sets a concrete hurdle. The completed ¥29,999.88 million buyback and ¥100 per share annual dividend plan show management leaning into shareholder returns even as debt coverage by operating cash flow is flagged as a weak point.
In the short term, the key swing factors are operating profits versus that ¥127,700 million target and how smoothly Hankyu Hanshin Holdings reshapes itself after transferring Hankyu Hanshin Express to Mitsubishi Logistics. The sale reduces exposure to international transportation and may simplify the story, yet it also removes a business line that had its own growth levers. With earnings growth in the mid single digits and P/E around 14x, the stock leans on execution rather than rerating hopes.
Even so, there is a less comfortable angle to this return of cash story that hinges on...
There's only one way to know the right time to buy, sell or hold Hankyu Hanshin Holdings. Head to Simply Wall St's company report for the latest analysis of Hankyu Hanshin Holdings's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own judgment.
- A great starting point for your Hankyu Hanshin Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hankyu Hanshin Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hankyu Hanshin Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hankyu Hanshin Holdings?
If Hankyu Hanshin Holdings has sharpened your focus on earnings quality, dividends and balance sheet strength, broadening your watchlist can help you benchmark it against other potential opportunities on the Simply Wall St Screener.
- If you want businesses that already pair strong income streams with higher yields, take a look at 30 dividend fortresses that concentrate on sustaining shareholder payouts.
- For investors who put capital preservation first, consider companies in a 22 resilient stocks with low risk scores and see which stocks line up with a steadier risk profile.
- When you are hunting for quality that is not widely followed yet, scan through a 74 high quality undiscovered gems and compare their fundamentals to what you see at Hankyu Hanshin Holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com