


Eaton (NYSE:ETN) just posted new third quarter results, giving investors fresh numbers on sales, profit and earnings per share, alongside updated full year guidance for organic growth and adjusted EPS.
The third quarter earnings beat and raised guidance arrived after a choppy stretch, with the share price falling 10.18% over the past 30 days and 12.43% over 90 days, yet still showing a 19.67% year to date share price return and a 142.34% five year total shareholder return that points to long term momentum rather than a brief spike.
Spot fresh catalysts in Eaton's Q3 beat. Then scan a curated set of power and grid plays with the 41 power grid technology and infrastructure stocks.Eaton is posting record results while the share price has cooled over the past quarter. That mix of strong execution and a softer tape is what matters next. Is this business quality already fully priced in today?
Most Popular Narrative: 24% Undervalued
The most followed valuation narrative for Eaton pegs fair value at $517, well above the last close of $391.70. This frames the Q3 beat against a longer term grid to data center thesis that goes far beyond a single quarter.
Eaton Corporation (NYSE: ETN) is one of the rare institutions that has managed to turn the physical constraints of heavy industry and metallurgy to its advantage. Its monopolistic position, benefiting from high material constraints (GOES), years-long delivery times, and in-cabinet thermal densities of 120 kW, along the Voltage Cascades from a 400,000-volt grid to 1 volt on a chip, has provided the company with an unsurpassable economic moat.
See why 20 investors see Eaton as 24% undervalued.
Result: Fair Value of $517 (UNDERVALUED)
Still, Eaton’s thesis leans heavily on AI megaprojects and grid bottlenecks, so any slowdown in data center buildouts or easing transformer constraints could quickly challenge this 24% undervalued story.
Find out about the key risks to this Eaton narrative.
Another View: What Eaton’s P/E Is Saying
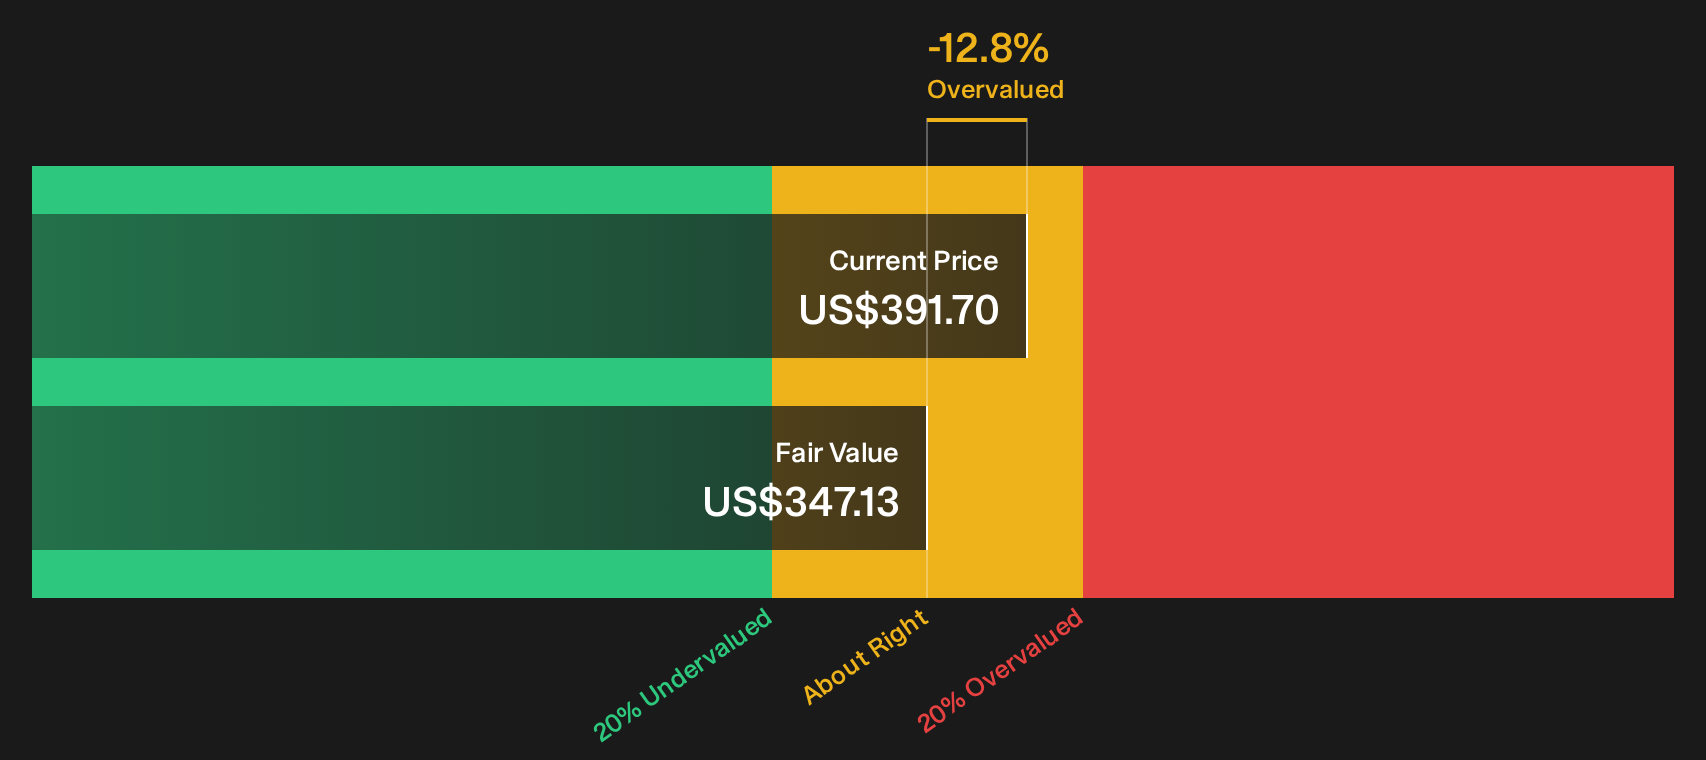
The SWS DCF model in that leading narrative lands on a fair value of about $347 per share, which points to Eaton trading above that estimate rather than below it. That clashes with the $517 Physical AI thesis and turns the question back on the inputs. Which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals or early setup: If Eaton’s story feels split between risk and reward, move quickly and weigh both sides through the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Eaton?
If Eaton has sharpened your focus on quality, do not stop here. Use fresh screeners to surface other opportunities before the crowd moves on.
- Target resilient returns and steady income by scanning companies that show up in our 4 dividend fortresses.
- Hunt for quality at a sensible entry point by reviewing the 35 high quality undervalued stocks that clear both fundamentals and valuation checks.
- Protect the downside first and shortlist sturdier prospects through the 30 resilient stocks with low risk scores before capital races elsewhere.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com