


Integer Holdings earnings event in focus
Integer Holdings (ITGR) just reported third quarter 2026 results, with sales of US$449.66 million and net income of US$14.98 million. The new figures give investors fresh data to reassess the medical device manufacturer.
Integer Holdings has barely moved in the last week, yet the share price sits at US$126.55 after a strong year to date, with a 64.82% year to date share price return and an 84.45% 1 year total shareholder return. This hints that investors have been reassessing both growth potential and risk around the latest earnings wobble rather than abandoning the longer term story.
Scan beyond Integer Holdings and explore other healthcare manufacturers showing strong momentum with our curated list of list of solid balance sheet and fundamentals (23 results)
After a sharp rerating and a softer quarter, Integer Holdings now asks you to weigh a richer share price against a thinner earnings run rate. Does that trade off still stack up on valuation?
Most Popular Narrative: 0% Undervalued
Integer Holdings now trades almost exactly in line with the most followed fair value estimate of $127, set against the last close at $126.55. For investors, the key question is whether the pipeline and outsourcing trends described in the prevailing narrative justify that pricing.
The much larger product development pipeline, with sales over 300% above 2017 levels and roughly 80% of projects tied to electrophysiology, neurovascular, structural heart and neuromodulation, provides a queue of potential design wins that can convert into launched programs and incremental revenue.
Growth in neuromodulation PMA customer sales from US$10 million in 2018 to US$125 million in 2024, together with management’s expectation for this portfolio to compound at 15% to 20% over the next 3 to 5 years based on current launches, points to an additional source of high margin revenue and earnings contribution.
See why 6 investors see Integer Holdings as 0% undervalued.
Result: Fair Value of $127 (ABOUT RIGHT)
Still, the Integer Holdings story can change quickly if key OEM customers cut orders again or if efficiency gains fail to support the current margin profile.
Find out about the key risks to this Integer Holdings narrative.
Another view on Integer Holdings valuation
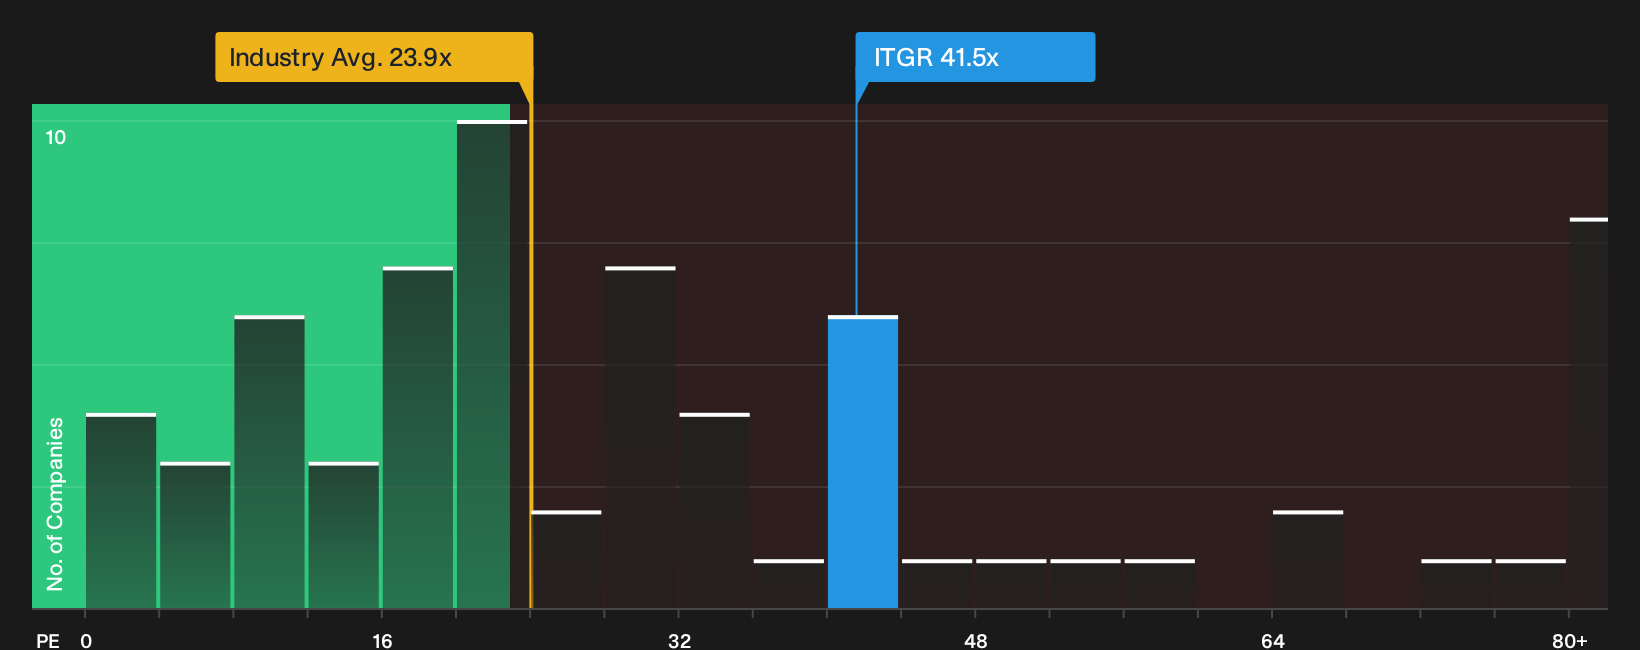
While the prevailing fair value narrative pegs Integer Holdings close to US$127, the P/E tells a different story. The stock trades on 41.5x earnings, compared with a fair ratio of 32.2x, the US Medical Equipment sector at 23.8x, and peers at 32.4x. That kind of premium raises a simple question: Is this pricing extra quality or extra risk?
See what the numbers say about this price in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Integer Holdings is mixed, with notable concerns and optimism appearing in the same data. Act while the information is fresh and consider both perspectives by reviewing the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Integer Holdings?
If Integer Holdings has sharpened your focus on quality and risk, now is the moment to broaden your watchlist with a few carefully filtered ideas.
- Target resilient balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that filters companies on financial strength first.
- Hunt for mispriced quality by reviewing a focused 35 high quality undervalued stocks built around strong cash flows and cleaner balance sheets.
- Stack income potential on top of price discipline by checking a hand picked 4 dividend fortresses of higher yielding companies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com