


Dropbox shares have climbed over recent years, and the current price around US$34.96 puts a spotlight on a simple question for you as an investor. Is the stock price you see on screen today adequately backed up by the company’s earnings power, or is the market asking you to pay too much for what the business currently earns?
- Over the past 3 years the stock has returned 35.0%, which makes it important to check whether that share price progress is supported by the underlying profit stream.
- Recent coverage highlighting positive technical signals and a sustained winning streak has fed into expectations about Dropbox’s ability to keep converting its file storage and collaboration user base into durable earnings and cash generation.
- There is a second opinion on Dropbox worth weighing. See what analysts think Dropbox's shares could be worth.
The issue now is whether Dropbox’s present share price is fairly explained by the earnings it produces today and what those profits may reasonably support over time.
If you are deciding whether Dropbox at US$34.96 is fairly priced based on its earnings, it can help to compare it using the same earnings lens across 35 high quality undervalued stocks
Is Dropbox a Bargain on Earnings?
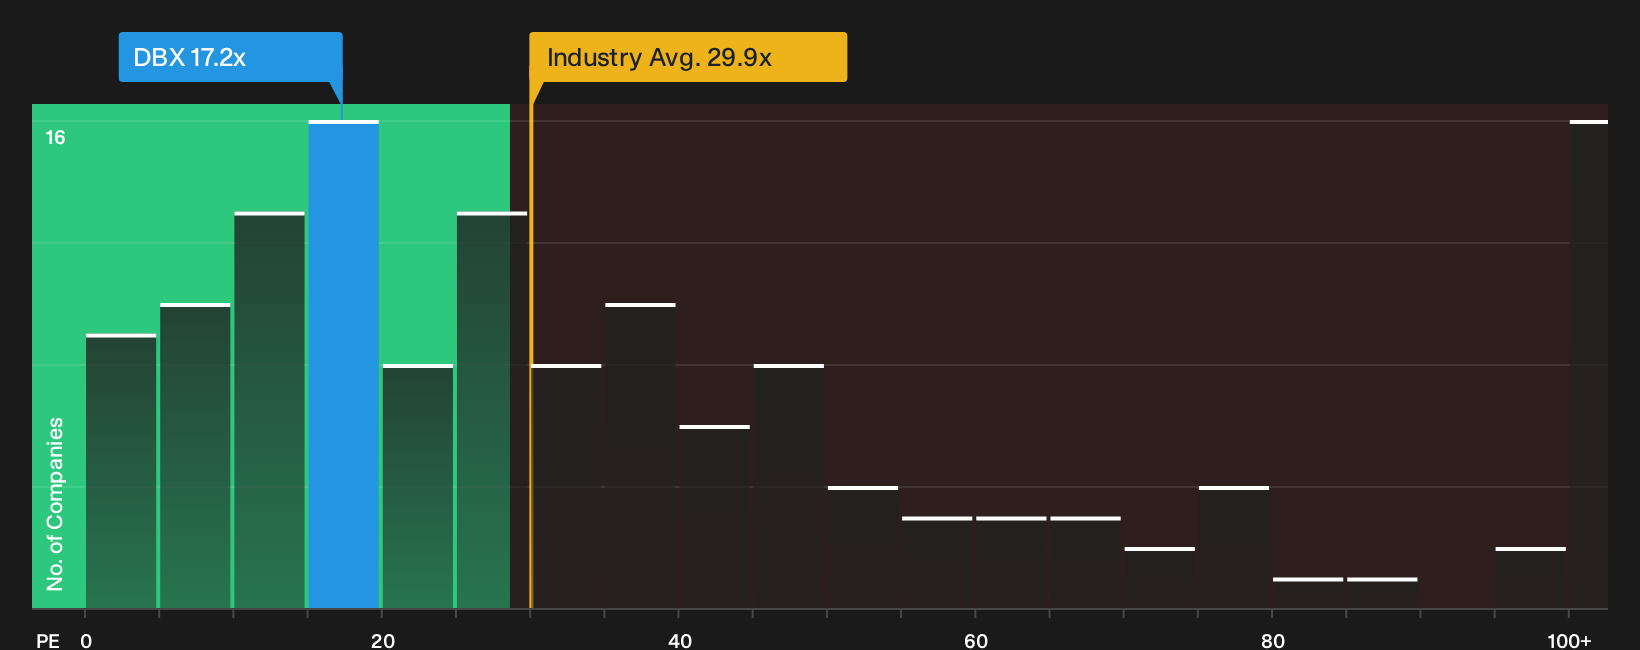
The P/E ratio works well for a business like Dropbox because earnings and cash generation are central to how investors judge its value today. At roughly 17.2x earnings, Dropbox trades at a lower multiple than the broader Software industry on 29.9x and also below the peer group average of 26.0x. That gap means the market currently values each dollar of Dropbox earnings at a discount to many comparable software stocks.
Based on the tailored fair P/E that factors in Dropbox’s sector, profitability profile and scale, the current 17.2x reading appears undervalued rather than stretched. Despite recent upbeat technical commentary and a short winning streak in the share price, the earnings multiple still prices Dropbox below what this framework suggests investors might typically pay for similar financial characteristics. Explore the numbers behind Dropbox's P/E valuation.
The Dropbox Narrative: What Would Justify Today's Price?
Dropbox Narratives on Simply Wall St pick up exactly where the P/E puzzle leaves off, by spelling out what kind of future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price. They sit on the Community page so you can follow those storylines over time. Where a single ratio or valuation model gives one number, Narratives describe the future that number rests on so you can watch whether reality lines up.
Community views on Dropbox are split between those who see more upside in the current setup and those who think most of the good news is already in the price.
Bull case: 17% undervalued
"Embedding Dash intelligence directly into the main Dropbox experience and expanding access to Teams customers, where more than 30% of weekly engaged users and over 50% of monthly engaged users are already using Dash features, creates scope for higher attach rates to paid AI workflows that can support recurring revenue growth..."
Discover why this Narrative puts Dropbox at 17% undervalued.
Bear case: roughly fairly valued
"Recent research argues that Dropbox shares already reflect a high level of confidence in the success of the AI pivot at a time when the core file sync and share business is only growing modestly and near term revenue expectations are flat..."
Explore why this Narrative puts Dropbox at roughly fairly valued.
Dropbox valuation leaves one big question hanging
All the current ratios tell you what Dropbox looks like today, but professional coverage also sketches where they expect earnings and cash flows to be a few years from now. Explore where analysts expect Dropbox to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com