


Mosaic has seen its share price weaken in recent years, which puts fresh attention on a simple question for investors who still follow the stock. Is the current market value supported by what the fertilizer producer is generating in sales today and what the market expects it to sell in the future.
- Over the past 5 years the share price has fallen 44.3%, so anyone looking at Mosaic now is effectively reassessing what its current level of sales is worth compared with that much lower equity value.
- The company has highlighted ongoing work on its biological solutions platform, which can shape how investors think about future revenue mix and the potential pricing power of its crop nutrient offerings.
- Your read on Mosaic is one view; the desks covering it have another. See what analysts think Mosaic's shares could be worth.
The issue now is whether Mosaic's current share price is justified by its sales when set against this weaker share performance and the recent business updates.
If you are reassessing Mosaic through the lens of sales and price, it can help to compare it with a broader set of companies by screening for 35 high quality undervalued stocks
Is Mosaic Still Cheap on Sales?
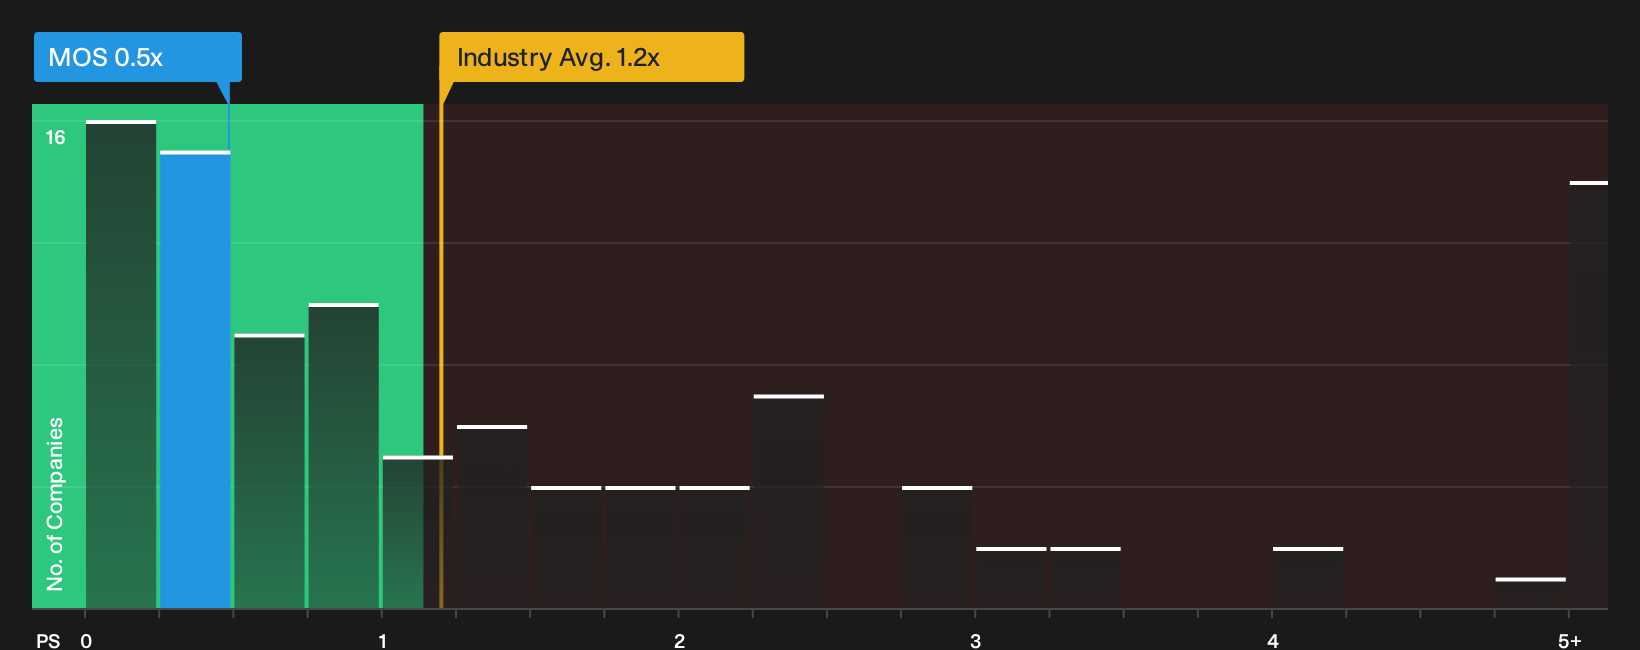
The P/S ratio suits Mosaic because investors are focusing on what they are paying for each dollar of current revenue rather than near term earnings swings. On that score, the stock trades on a P/S of 0.5x, compared with an industry average of 1.2x and a peer group around 1.4x. That is a steep discount on sales against both the broader chemicals sector and closer competitors.
Recent third quarter 2026 results kept attention on Mosaic's biological solutions push. Yet the share price still values the business below the P/S multiple implied by a tailored fair ratio model that factors in its growth profile, margins, size and risk. The current discount signals that the market is pricing Mosaic as undervalued on sales relative to what this framework suggests might be justified, and invites investors to weigh how durable those revenues look over a full cycle before drawing firm conclusions. Explore the numbers behind Mosaic's P/S valuation.
The Mosaic Narrative: What Would Justify Today's Price?
Narratives on Mosaic act as the missing link between its low P/S multiple and the expectations the market might be baking in for future growth, profitability and earnings power. Each scenario ties a fair value view to a clear storyline about Mosaic's possible catalysts and risk points, so you can track over time which version seems to be matching what actually happens, all hosted on Simply Wall St's Community page.
Community views on Mosaic split between investors who see the stock as undervalued on its future mix and those who think current pricing already bakes in plenty of risk.
Bull case: 29% undervalued
"The main thing that has to go right is Mosaic successfully shifting away from underperforming phosphate assets toward higher margin businesses such as Mosaic Biosciences and rare earth element projects..."
Discover why this Narrative puts Mosaic at 29% undervalued.
Bear case: 6% overvalued
"Although tight global phosphate supply and elevated DAP minus raw material margins currently support Mosaic’s realized pricing, prolonged sulfur availability and affordability constraints that have already taken Louisiana offline..."
Explore why this Narrative puts Mosaic at 6% overvalued.
One more Mosaic angle worth checking before you move on
Price tags on Mosaic only tell part of the story, because the people choosing capital projects, setting risk appetite and deciding buybacks or dividends, and how they are rewarded for those choices, can tilt your whole thesis. See who runs Mosaic and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com