


National Healthcare Properties (NHP) has moved in and out of the NASDAQ Composite Index several times in late October 2026, a rare pattern that can stir trading as index-tracking funds repeatedly rebalance.
Recent trading reflects that push and pull. National Healthcare Properties has a 1-day share price return of 2.65% and a 7-day share price return of 4.10%, while the 30-day and 90-day share price returns are down 3.73% and 3.37% respectively. However, the year-to-date share price return of 29.08% points to stronger longer term momentum as index changes briefly reshape how investors view its risks and prospects.
Scan how National Healthcare Properties compares to other real estate stocks reacting to index moves by reviewing our hand picked 30 resilient stocks with low risk scores with resilient profiles and lower risk scores.
After a sharp year to date run and whiplash index changes around National Healthcare Properties, the question is simple: Does it make more sense to pay up today or wait for a cleaner entry on the valuation math?
Most Popular Narrative: 20.9% Undervalued
On the numbers, the most followed narrative puts National Healthcare Properties’ fair value at $19.57 against a last close of $15.49. This frames the SHOP pivot and balance sheet reset as the key swing factors for anyone weighing patience versus paying up now.
Recycling about US$528.2 million from the planned sale of 86 outpatient medical facilities into senior housing communities concentrates National Healthcare Properties on a single operating model that could have a clearer link to future revenue and earnings growth.
Targeting SHOP acquisitions at a blended year 1 yield of 7.9% with an internal plan to reach 9.7% by year 3 points to a built in value add pipeline that can influence future cash NOI and margin expansion.
See why 1 investors see National Healthcare Properties as 21% undervalued.
Result: Fair Value of $19.57 (UNDERVALUED)
Still, the bullish story around National Healthcare Properties can crack if occupancy incentives linger, or if higher G&A and equity compensation eat into future margin progress.
Find out about the key risks to this National Healthcare Properties narrative.
Another View: Pricing National Healthcare Properties Off Sales
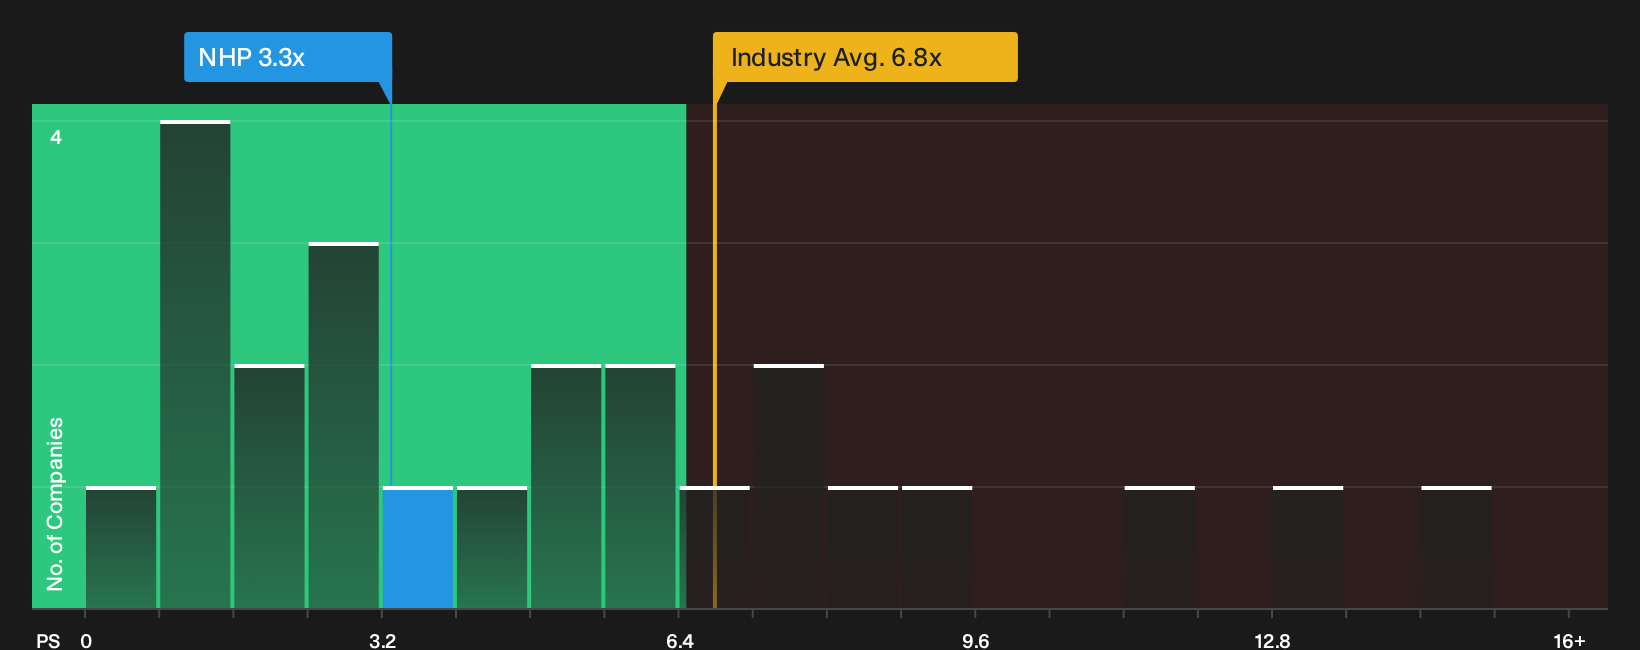
There is a catch to the bullish fair value story. On a P/S of 3.3x, National Healthcare Properties screens as expensive versus a fair ratio of 2x and a peer average of 2.2x, even though it is cheaper than the broader Global Health Care REITs group at 6.7x. That gap signals real valuation risk if sales or margins fall short of expectations.
For a closer look at how this sales based lens lines up with the rest of the numbers, including how the ratio might shift toward the fair ratio over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on National Healthcare Properties so far. If the bullish angle on future rewards has your attention, move fast and pressure test it against the data. Start by weighing those 3 key rewards
Looking for more investment ideas beyond National Healthcare Properties?
If you only stop at National Healthcare Properties, you miss a wider field of opportunities that could fit your risk profile and return goals more precisely.
- Target resilient performers by reviewing a list of solid balance sheet and fundamentals (23 results) and see which businesses back their story with financial strength.
- Hunt for mispriced quality through a 19 high quality undiscovered gems and spot companies the market may not be paying full attention to yet.
- Prioritize steady income by scanning a 4 dividend fortresses that focuses on high yields with more durable profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com