


- W. R. Berkley reported third quarter 2026 operating income of $1.17 per share, above the latest analyst consensus, with operating revenues of $3.76b and both net premiums earned and written showing year over year growth.
- The company’s ability to exceed profit expectations while recording only modest revenue expansion highlights how underwriting discipline and premium mix continue to shape W. R. Berkley’s earnings profile.
- We will now look at how W. R. Berkley’s earnings beat on operating income could influence the existing investment narrative around underwriting discipline.
Scan how W. R. Berkley’s underwriting discipline compares with peers by reviewing our hand picked 30 resilient stocks with low risk scores that prioritise balance sheet strength and controlled risk profiles.
W. R. Berkley Investment Narrative Recap
To own W. R. Berkley, you need to be comfortable with a specialty insurer that leans on underwriting discipline and reallocation between lines rather than chasing top line expansion. The recent operating income beat supports that message, while the modest 1.8% year over year revenue increase keeps attention on pricing, competitive pressure and how much growth management is willing to trade away to protect combined ratios.
The key near term swing factor is whether softening commercial pricing and slower rate momentum start to bite into underwriting margins as W. R. Berkley tilts more toward growth. The main risk is that competition in property and reinsurance, along with prior pullbacks in treaty business, leaves overall premium volume flatter than you might like if loss trends do not stay benign.
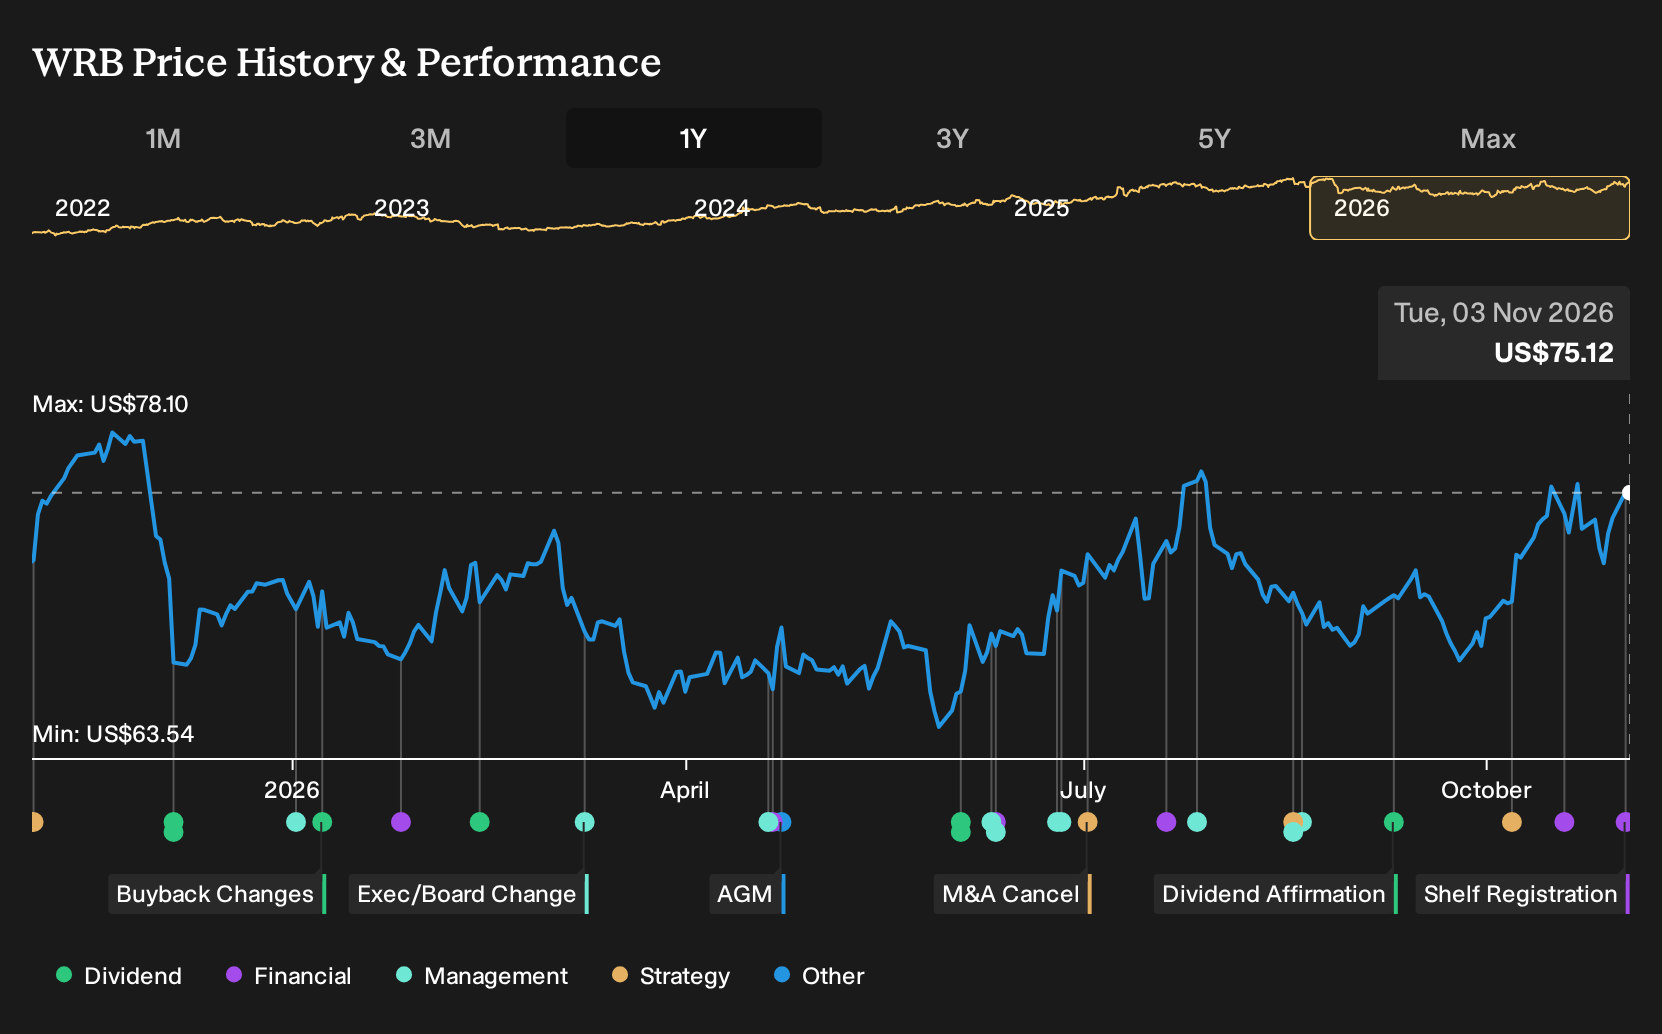
The shelf registration filed on 2 November 2026 matters because it refreshes W. R. Berkley’s ability to issue a wide range of securities, including debt, common and preferred stock, depository shares, warrants and stock purchase units. An omnibus or universal shelf does not change the story on its own, but it does expand the financing menu available if conditions or opportunities shift.
For you as a shareholder, the operational question is how any future issuance under this shelf might intersect with current catalysts such as underwriting discipline, capital intensity in insurance lines and investment income generated from new money yields above 5%. Potential use of debt or equity could influence leverage, per share metrics and the pace of capital return, so it is worth tracking alongside underwriting results rather than in isolation.
W. R. Berkley's narrative projects US$13.9b revenue and US$1.9b earnings by 2029, which implies that revenue declines 2.2% per year and earnings remain broadly unchanged from the current US$1.9b level.
Uncover why W. R. Berkley's fair value indicates an 8% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
Some of the lowest W. R. Berkley forecasts lean heavily on the risk that record net investment income fades. Those analysts were pencilling in revenue of about US$13.6b and earnings of roughly US$1.9b by 2029, yet still saw a much lower fair value. You can treat this earnings beat and fresh shelf as new information that might reshape both narratives.
Explore 2 other W. R. Berkley fair value estimates, including one that suggests up to 8% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your W. R. Berkley research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for W. R. Berkley. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate W. R. Berkley's overall financial health at a glance.
Looking for more W. R. Berkley style ideas?
If you like the blend of underwriting discipline and balance sheet focus that defines W. R. Berkley, it can pay to widen the lens and scan for other stocks with similar or complementary traits. The Simply Wall St Screener lets you filter for different risk, income and quality profiles so you can build a watchlist that fits how you prefer to invest rather than relying on a single story.
- For investors who want quality at a measured price, consider starting with a curated set of potential value opportunities through 35 high quality undervalued stocks that already clear basic fundamentals checks.
- If reliable balance sheets matter most to you, focus on financially resilient businesses by running a screen targeting stronger capital positions using the list of solid balance sheet and fundamentals (23 results).
- For those who care about getting paid while they wait, filter for higher yielding payout candidates by reviewing the income ideas in 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com