


Cheesecake Factory has had a powerful run, with the share price now in three-digit territory and recent news spotlighting record revenue and brisk traffic. With the stock at US$110.22, the key issue for investors is whether the cash the business can produce from its restaurants and concepts is strong enough to justify that market value.
- Over the past 3 years the Cheesecake Factory share price has returned 284.2%. This puts a lot of weight on the durability and growth of its future cash flows.
- Recent record revenue alongside 15.2% same-store sales growth, helped by higher guest traffic and menu initiatives, can influence how investors think about the level and timing of cash generation that underpins any intrinsic value estimate.
- What if you looked at Cheesecake Factory through its earnings instead? See what Cheesecake Factory's 26.4x P/E says about the price.
For investors, the debate is whether Cheesecake Factory's recent share price level is adequately backed by the cash flows implied in its intrinsic value under a Discounted Cash Flow (DCF) approach.
If you want a quick benchmark for Cheesecake Factory's run and its focus on cash generation, line it up against 35 high quality undervalued stocks for a broader view of value opportunities.
Has Cheesecake Factory Run Too Far on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at Cheesecake Factory through the cash it can return to shareholders over time. Latest twelve month free cash flow sits at about $187.1 million, with the model assuming that this stream grows from that base rather than shrinking.
Projected free cash flows in the coming decade rise into the mid $200 million range and then continue to build, which implies a business that the model treats as steadily expanding rather than peaking. Despite that constructive cash picture, the DCF outcome still puts Cheesecake Factory's estimated intrinsic value meaningfully below the current share price of US$110.22. Record quarterly revenue above $1.03b and 15.2% same store sales growth help explain why the market is willing to pay up here even though the cash flow model is more conservative. Find out what Cheesecake Factory could be worth using our Discounted Cash Flow (DCF) estimate.
The Cheesecake Factory Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Cheesecake Factory valuation puzzle leaves off and spell out which paths for revenue, margins and earnings would need to play out for the stock to be worth significantly more or less than it trades for today on the market. Each narrative treats Cheesecake Factory's estimated worth as a specific thesis about the business that can be revisited over time, rather than a one-off number. These narratives sit on Simply Wall St's Community page.
Cheesecake Factory inspires two very different readings of the same story, with one community view seeing more upside left than the other.
Bull case: 14% undervalued
"The main requirement for this thesis is successful execution of the multi-brand portfolio plan, that includes Flower Child scaling at attractive returns while North Italia stabilizes comparable sales and margins..."
Discover why this Narrative puts Cheesecake Factory at 14% undervalued.
Bear case: roughly fairly valued
"The current valuation implies the market is pricing Cheesecake Factory as if digital demand drivers, high-return growth at Flower Child, and mid single digit net income margins will continue to support the share price..."
Explore why this Narrative puts Cheesecake Factory at roughly fairly valued.
The Cheesecake Factory story has one more wrinkle investors should check
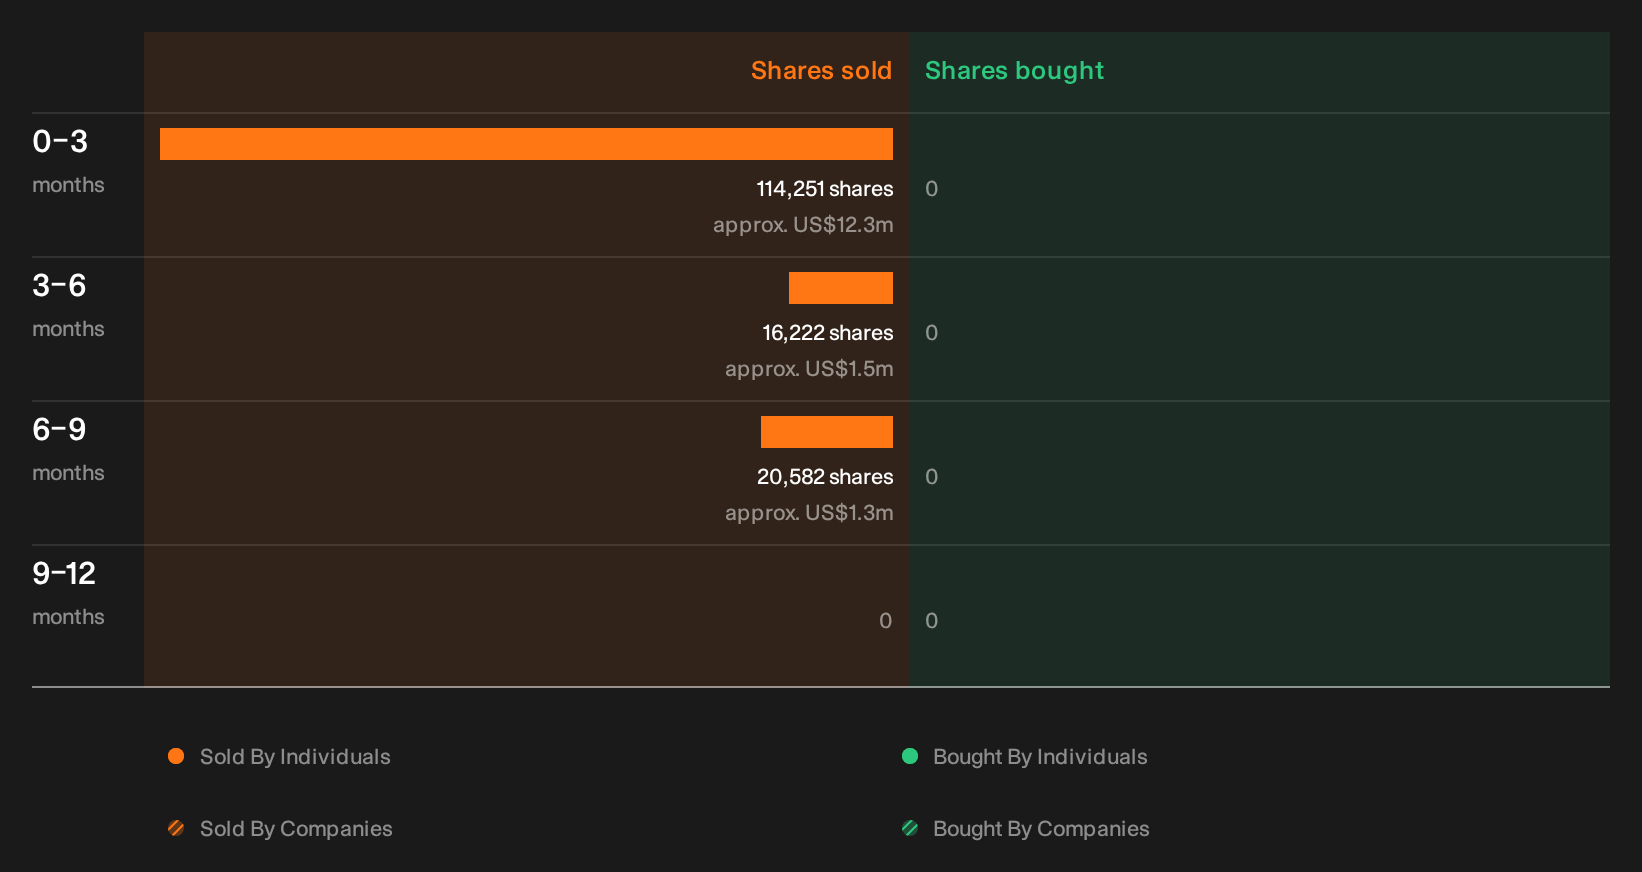
Valuation work only gets you so far when insiders have recently been selling, and the specific people involved, the size of those trades and what they might signal are the next piece you need to inspect. See the recent insider selling flagged for Cheesecake Factory.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com