


- JBT Marel (NYSE:JBTM) reported a record adjusted EBITDA margin for the third quarter of 2026, highlighting improved profitability metrics.
- The company expanded its share repurchase authorization, signaling a larger capital return program funded from its current resources.
- Management revised financial guidance to reflect what it described as stronger operational efficiencies across the business.
- The record third quarter margin and larger buyback come alongside refreshed guidance that sits against a wider backdrop our research has uncovered. We have also spotted 1 warning sign worth knowing about at JBT Marel.
For readers tracking how companies are using stronger cash generation to reward shareholders, it is worth comparing this update with 4 dividend fortresses.
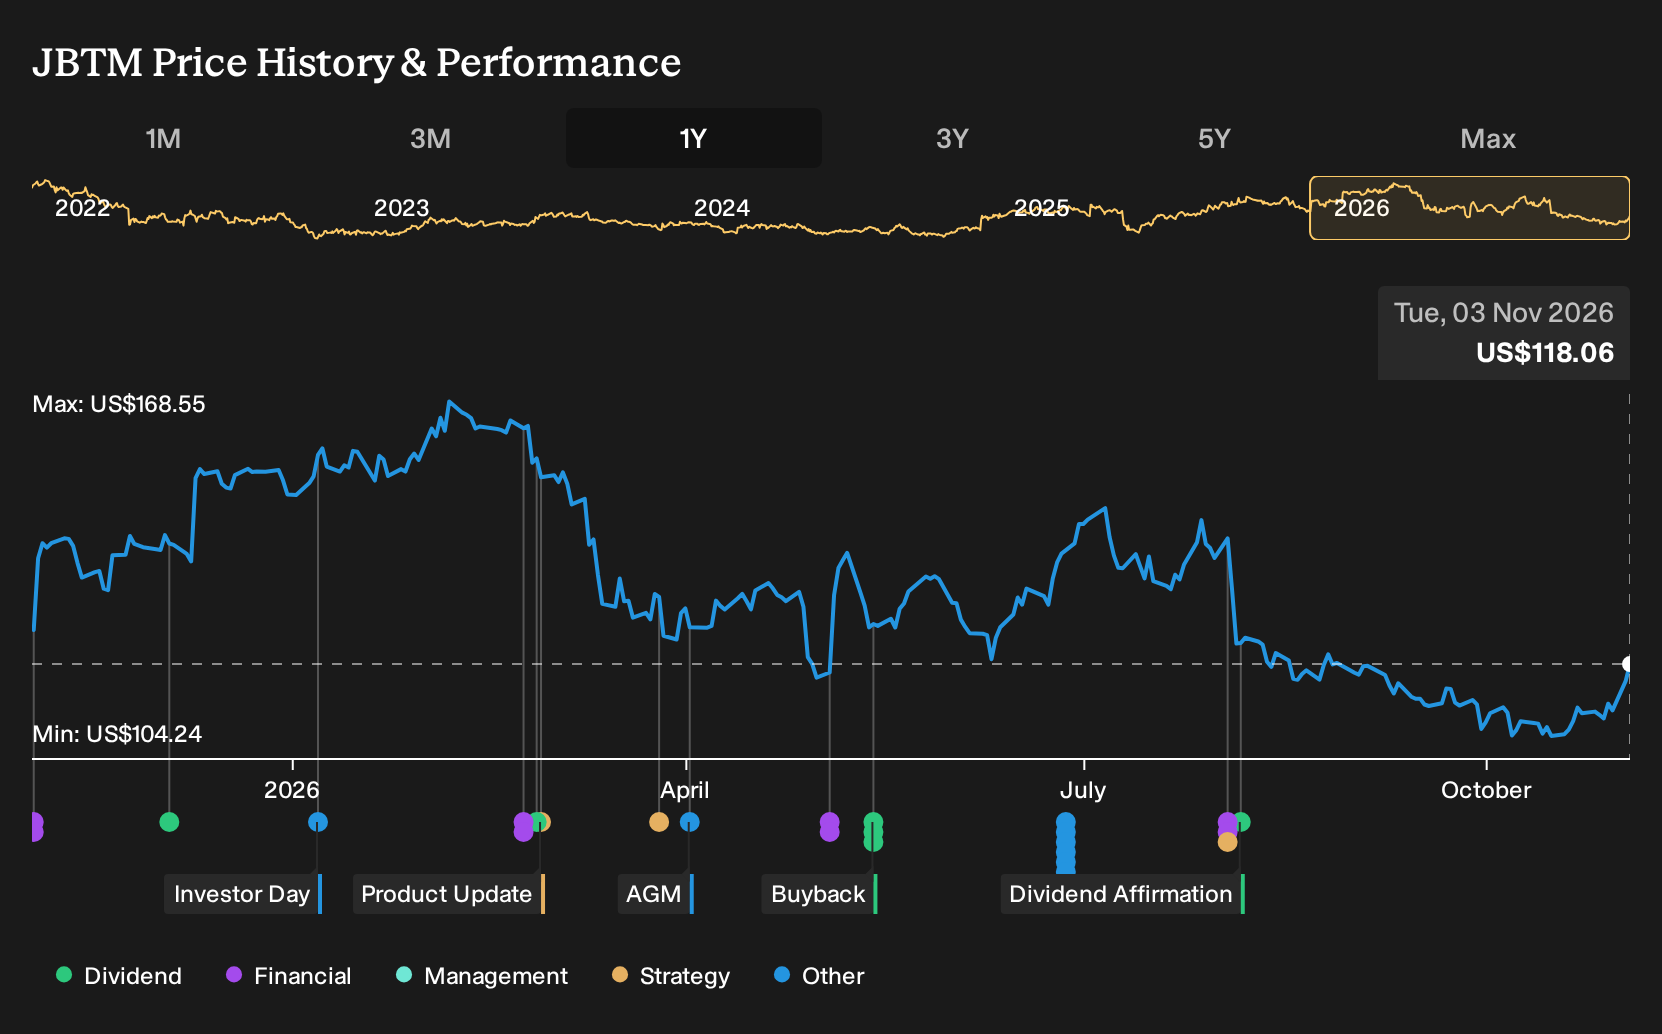
JBT Marel runs processing and automation systems for food and beverage producers across regions including North America, Europe and the Asia Pacific, so any shift in profitability or capital returns must be viewed in the context of a global customer base that relies on its machinery to keep high-volume plants running efficiently.
See which insiders are buying and selling JBT Marel following this latest news.
How strong were JBT Marel’s latest earnings in hard numbers?
For Q3 2026, JBT Marel reported sales of US$994 million versus US$1,001 million a year earlier, with net income of US$70 million compared with US$66 million. Basic EPS from continuing operations was US$1.35, slightly above US$1.26. Over the first nine months, the group moved from a US$104 million loss to a US$143 million profit.
Does this change the JBT Marel Narrative investors have been using?
The record 18.0% adjusted EBITDA margin and higher margin guidance align directly with the Narrative’s focus on cost and footprint programs. These include the US$150 million synergy target and US$25 million to US$30 million in expected annual footprint savings. At the same time, the cut to full year revenue guidance and the history of guidance misses keep the Narrative’s execution risk in clear focus rather than resolving it.
See how these catalysts shape JBT Marel's path to a $167 fair value.
What should you watch next to see if this is really working?
The clearest test is whether JBT Marel can keep adjusted EBITDA margins close to or above the latest quarter’s 18.0% level over the next few reporting periods while still generating the free cash flow needed to fund the US$700 million repurchase authorization. Consistent margin delivery through 2027 would indicate that the efficiency plan is holding.
Add JBT Marel to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com