


Expro shares closed at US$13.34 after several years of weak returns, which puts a spotlight on whether that price still lines up with what the business is earning today. With the stock having trailed over multiple time frames, the key issue for investors is how much of Expro's earnings power the current valuation already assumes.
- Over the past 5 years the share price has fallen 32.1%, which raises the question of how much the market has recalibrated expectations for the company's earnings profile.
- Management has paired improving profitability with a new US$100 million share repurchase plan. This combination can reshape how earnings per share and capital allocation feed into any valuation grounded in the company's income stream.
- There is a second opinion on Expro worth weighing. See what analysts think Expro's shares could be worth.
The stock's next move may depend on whether Expro's current earnings and their trajectory are strong enough to support today's share price on an earnings basis.
For context on how Expro’s earnings story compares with other opportunities, you can start a fresh idea list using 35 high quality undervalued stocks.
Does Expro Look Pricey on Earnings?
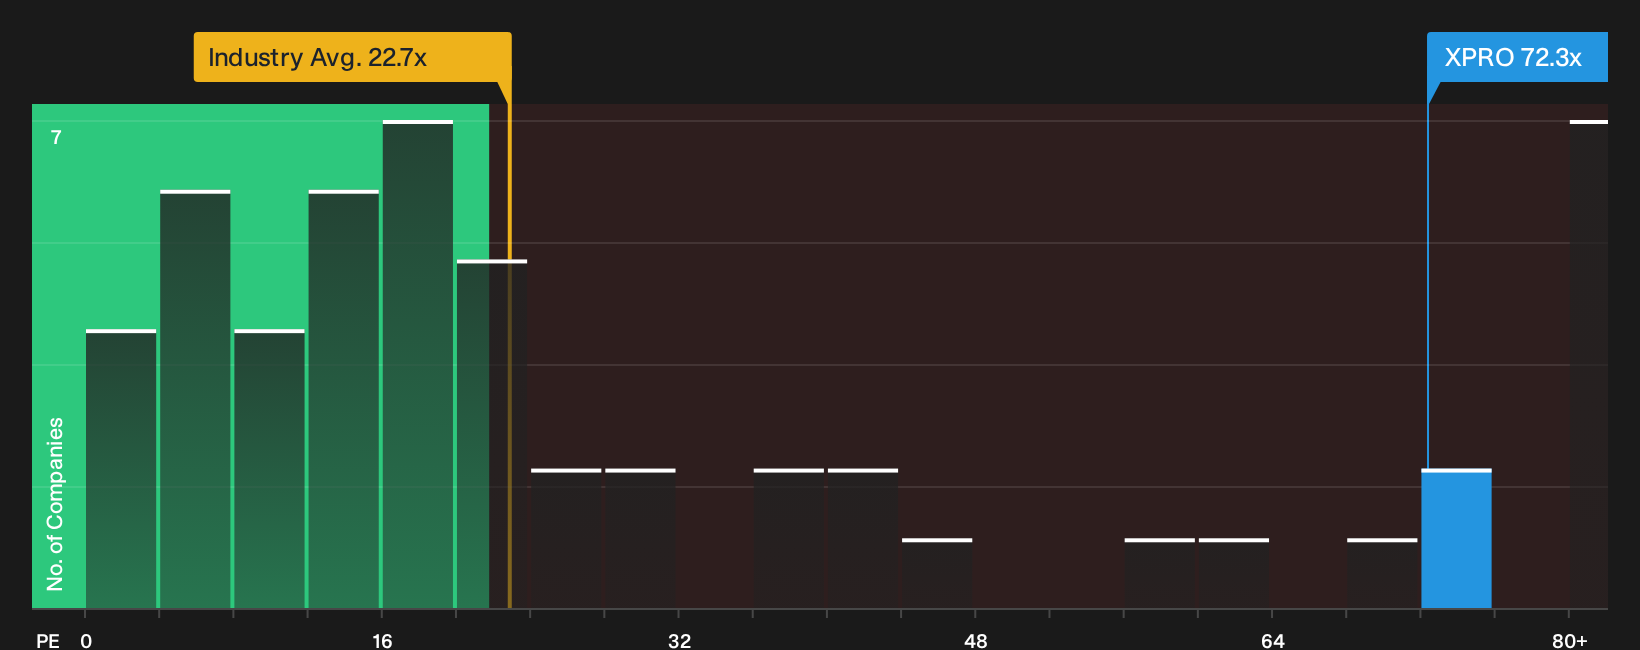
The P/E lens fits Expro because investors are heavily focused on how much of today’s share price is being justified by current earnings. At about 72.3x earnings, Expro trades well above the Energy Services industry average of roughly 22.7x and also above the peer group on roughly 32.2x. That type of gap means each dollar of profit at Expro is being valued far more richly than at many similar businesses.
The Fair Ratio model, which aligns the P/E you might expect with Expro’s margins, growth profile, size and risk, flags the current multiple as stretched. Despite the stronger Q3 2026 results and the new US$100 million buyback plan lifting sentiment, the valuation still prices the stock at a premium to what this framework implies for the earnings profile. Explore the numbers behind Expro's P/E valuation.
The Expro Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Expro's valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price. Each narrative sets out the assumptions behind its fair value so you can compare those inputs with Expro's actual results as they are reported.
One of the top community narratives on Expro: 24% undervalued
"The main factor that has to go right is successful execution on margin expansion plans, including structural cost reductions and a higher margin mix..."
Discover why this Narrative puts Expro at 24% undervalued.
One more thing about Expro that deserves your attention
Headline valuation only shows part of the story for Expro, because separate checks have raised specific concerns that can change how you weigh the opportunity once you see them. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com